
SalMar (OB:SALM) Harvest Update Puts The Undervalued Case Back In Focus
SalMar (OB:SALM) is back in focus after reporting third quarter 2026 operating results. Consolidated harvest volume reached 105,100 tonnes, a key operational datapoint many investors watch closely.
At a share price of NOK559.5, SalMar has seen short term momentum pick up, with a 90 day share price return of 13.58%. However, the year to date share price is still down 9.61% and the 1 year total shareholder return has fallen 8.35%. At the same time, the 3 year total shareholder return sits at 25.78% and the 5 year total shareholder return at 6.53%, suggesting recent enthusiasm around the latest harvest update is rebuilding from a weaker stretch rather than marking a fresh high point.
Scan how other salmon and protein producers are reacting to similar operating updates by tracking the hand picked list of solid balance sheet and fundamentals (202 results) alongside SalMar.
SalMar appears to be a solid salmon producer, supported by this harvest update and a long-term record of positive returns. The more difficult question is whether NOK559.5 already reflects that quality.
Most Popular Narrative: 9% Undervalued
At NOK559.5, the most followed narrative on SalMar puts fair value at NOK615.45, so the story hinges on whether recent biological and cost improvements can sustain that gap.
The main thing that has to go right is that SalMar sustains lower ongrowth costs and successfully integrates new Norwegian capacity, including the planned Måsøval acquisition, without repeating the biological challenges seen in Iceland and Scotland.
The proposed integration and consolidation with Wilsgård AS has been followed by additional capacity moves such as the planned acquisition of Måsøval and the conversion of offshore licenses, and the targeted cost synergies and added volume potential from these steps can support higher group revenue and operating earnings over time.
See why 16 investors see SalMar as 9% undervalued.
Result: Fair Value of NOK615.45 (UNDERVALUED)
Still, the story can break if environmental or biological problems return in key regions, or if higher production and resource taxes erode profitability faster than expected.
Find out about the key risks to this SalMar narrative.
Another View On SalMar’s Valuation
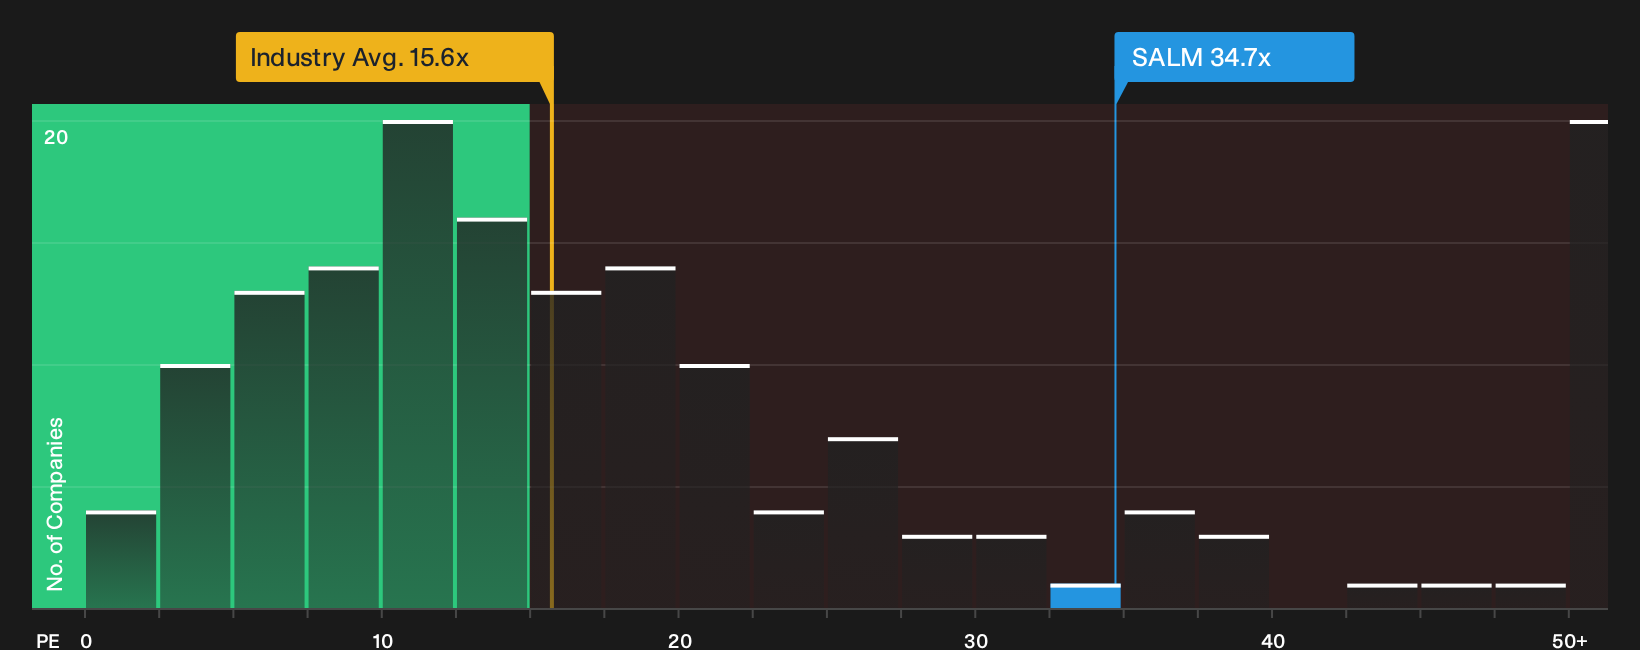
The first story frames SalMar as about 9% undervalued at NOK615.45. A different lens tells a tougher story. On a P/E of 34.7x versus a fair ratio of 24.7x, and compared with 15.6x for the wider European Food group and 22.4x for peers, the share looks expensive. That kind of gap can close through time either via stronger results or a lower price. Which outcome do you think is more realistic?
For a closer look at what the market is currently paying against underlying earnings power, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Plenty of mixed signals run through this SalMar story, which makes it a useful test of your own process and risk tolerance. If you want to size up both sides before making a call, start with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond SalMar?
If SalMar has sharpened your focus on quality and pricing, it is worth widening your watchlist to other opportunities built on clear fundamentals and disciplined balance sheets.
- Target resilient cash generators by scanning the 200 high quality undervalued stocks to find candidates that pair solid fundamentals with prices that may not fully reflect their underlying strength.
- Build a steadier income stream by reviewing the 218 dividend fortresses to identify opportunities that concentrate on higher yielding payouts supported by robust financial profiles.
- Lower portfolio stress by focusing on the 231 resilient stocks with low risk scores to highlight companies with stronger balance sheets and fewer red flags.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com