
Match Group (MTCH) Stock Climbed, What Is Behind The Fresh Attention?
Evercore ISI’s upgrade of Match Group (MTCH) to Outperform, tied to a reported operational recovery at Tinder and fresh growth in monthly active users, has pushed the dating platform back onto investors’ radars.
The upgrade follows a strong run in Match Group’s share price, with a 1-day move of 4.14% and a 7-day share price return of 7.73% helping extend the 40.93% year-to-date gain. Short-term momentum looks constructive compared with the 38.70% 1-year total shareholder return and the much weaker 5-year total shareholder return, which is down 72.07%. This suggests that recent enthusiasm is more about a shift in sentiment and perceived risk than a long track record of outperformance.
Scan how Match Group’s rebound compares with other potential breakouts using our curated list of 20 high quality undiscovered gems across the market.
Match Group now has improving Tinder fundamentals and a sharp share price rebound working in its favor. The real tension for investors is whether that mix is already fully reflected in today’s valuation.
Most Popular Narrative: 7% Overvalued
Match Group last closed at $44.73, while the most followed narrative framework anchors fair value at $41.88. This implies the recent rally has moved the stock above that reference point and pushed expectations higher.
The current valuation and the characterization of Match Group as fairly valued and bullish indicates that the market already reflects meaningful long term benefits from AI driven efficiency, user outcome centric design, and Hinge's path toward around US$1b of annual revenue.
See why 24 investors see Match Group as 7% overvalued.
Result: Fair Value of $41.88 (OVERVALUED)
Still, Match Group’s story could weaken if revenue pressure persists, with the latest quarter showing a 1.2% decline and total payers down 5.7% to 13.3 million.
Find out about the key risks to this Match Group narrative.
Another View: Match Group Through The DCF Lens
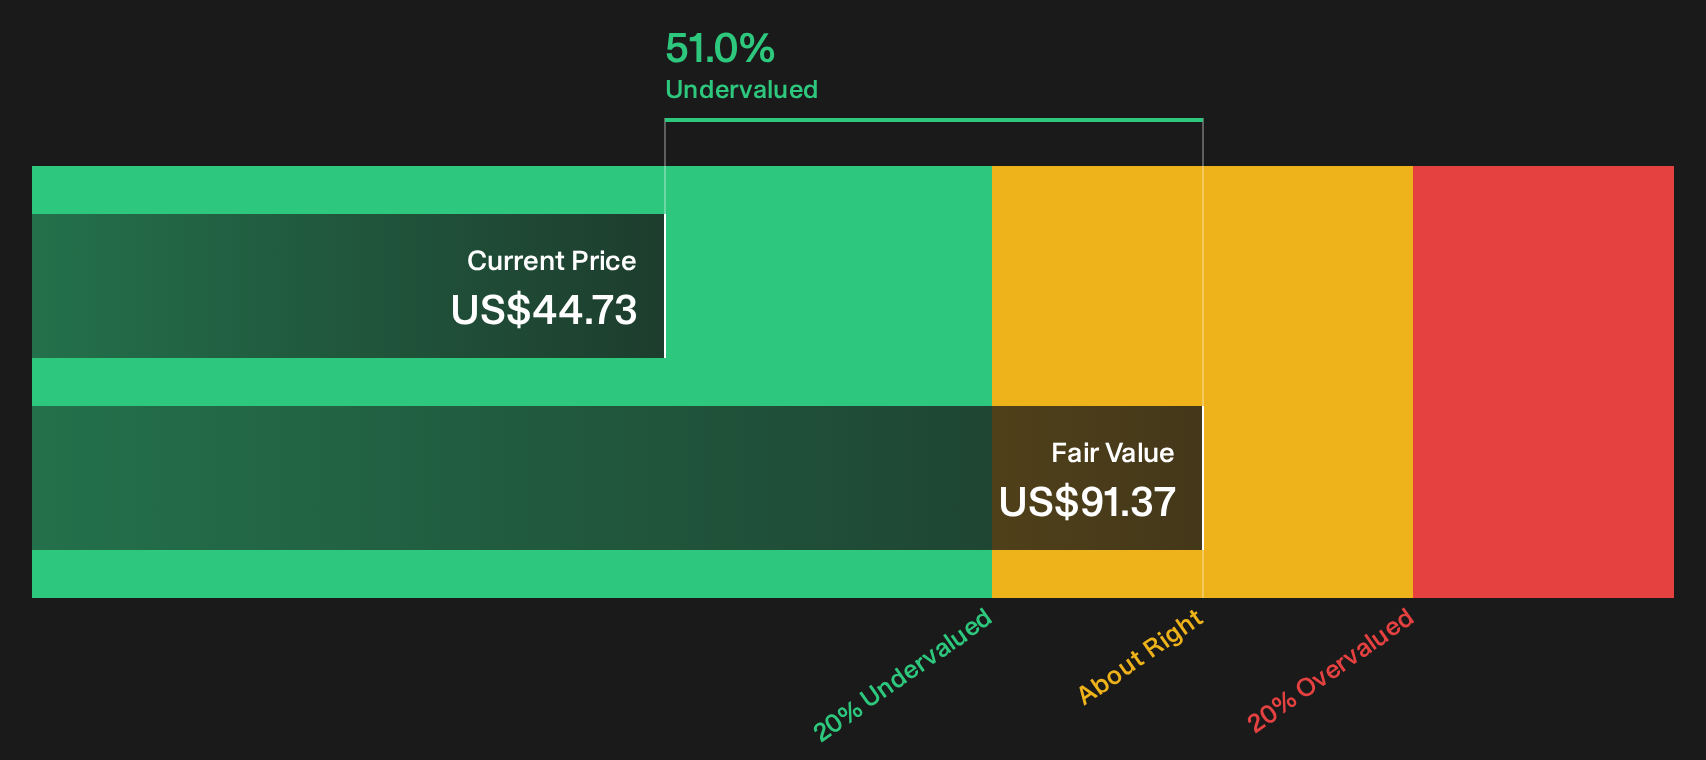
While the consensus narrative pegs Match Group as about 7% overvalued relative to a $41.88 fair value, the Simply Wall St DCF model lands in a very different place. On that framework, MTCH at $44.73 is trading at roughly a 51% discount to an estimated $91.37 future cash flow value, which points to a wide gap in how cash generation is being priced. For investors, the real question is which framework feels closer to how you think this business can actually perform over time.
To understand how those cash flow assumptions stack up against the narrative and analyst targets, take a closer look at how the SWS DCF model is built and what is driving that higher fair value estimate. Look into how the SWS DCF model arrives at its fair value.
Next Steps
Still evaluating how Match Group compares after this move and what really matters most in the story from here. Consider both the concerns and potential upside, and ground your own view with the 3 key rewards and 3 important warning signs.
Looking for more Match Group sized opportunities?
If you want to pressure test your view on Match Group and spot what the market could be missing elsewhere, line up a few fresh ideas side by side.
- Target income first and filter for companies built around steady cash returns using a focused group of 8 dividend fortresses.
- Hunt for quality at a discount and see which solid businesses still trade below their implied worth by scanning a curated set of 35 high quality undervalued stocks.
- Dial down portfolio stress and concentrate on durability by reviewing a 32 resilient stocks with low risk scores that screens for resilience when conditions change.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com