
EZCORP (EZPW) Stock May Be Overvalued Following Its 328% Run
EZCORP has delivered a powerful run over the past few years, so the obvious question now is whether the current share price lines up with the returns the business earns on its capital. With that kind of track record in the rear-view mirror, the key issue for you is whether the stock’s valuation is still grounded in the economics of the underlying pawn and lending operations.
- EZCORP has returned about 328.1% over the past 5 years, which puts a lot of weight on whether the capital the company invests is truly earning enough to support that kind of share price outcome.
- The business model relies heavily on how efficiently it can deploy cash into loans and inventory, so the sustainability of those returns on capital may support or limit how much value shareholders can reasonably ascribe to future reinvestment.
- Prefer to judge EZCORP on earnings? See why EZCORP's 12.7x P/E tells a different valuation story.
The issue now is whether the returns EZCORP earns on its capital are strong and durable enough to justify where the stock trades today.
If you want to stress test this same question about the returns companies earn on their capital across a wider field, scan through our screener containing 20 high quality undiscovered gems
Has EZCORP Run Too Far on Excess Returns?
The Excess Returns model asks whether EZCORP’s equity can earn more than it costs. Here, the framework leans on how efficiently the pawn and lending platform can compound its book value over time rather than on a single cash flow forecast.
EZCORP’s book value sits at $18.94 per share, with a stable book estimate of $16.86 per share based on future projections from two analysts. The model uses a stable EPS of $1.75 per share, anchored to the median return on equity from the past 5 years, against a cost of equity of $1.46 per share. That spread implies an excess return of $0.30 per share, supported by an average return on equity of 10.39% in the inputs supplied.
For you as a shareholder, the key question is whether those excess returns can persist long enough to justify paying $32.75 for the stock when the Excess Returns projections put EZCORP's estimated intrinsic value substantially below the current share price. Find out what EZCORP could be worth using our Excess Returns estimate.
The EZCORP Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for EZCORP pick up where that valuation gap leaves you. They spell out which assumptions on growth, margins and earnings would need to hold for EZCORP's share price to sit meaningfully above or below where it trades today on the Community page. Each scenario ties a fair value estimate to a particular set of potential catalysts and risks so you can track over time which storyline is actually unfolding.
One of the top community narratives on EZCORP: 20% undervalued
"Continued focus on core pawn profitability, with most recent EBITDA and gross profit growth coming from pawn operations rather than scrap gold…"
Discover why this Narrative puts EZCORP at 20% undervalued.
One more EZCORP signal to weigh before you act on the valuation work
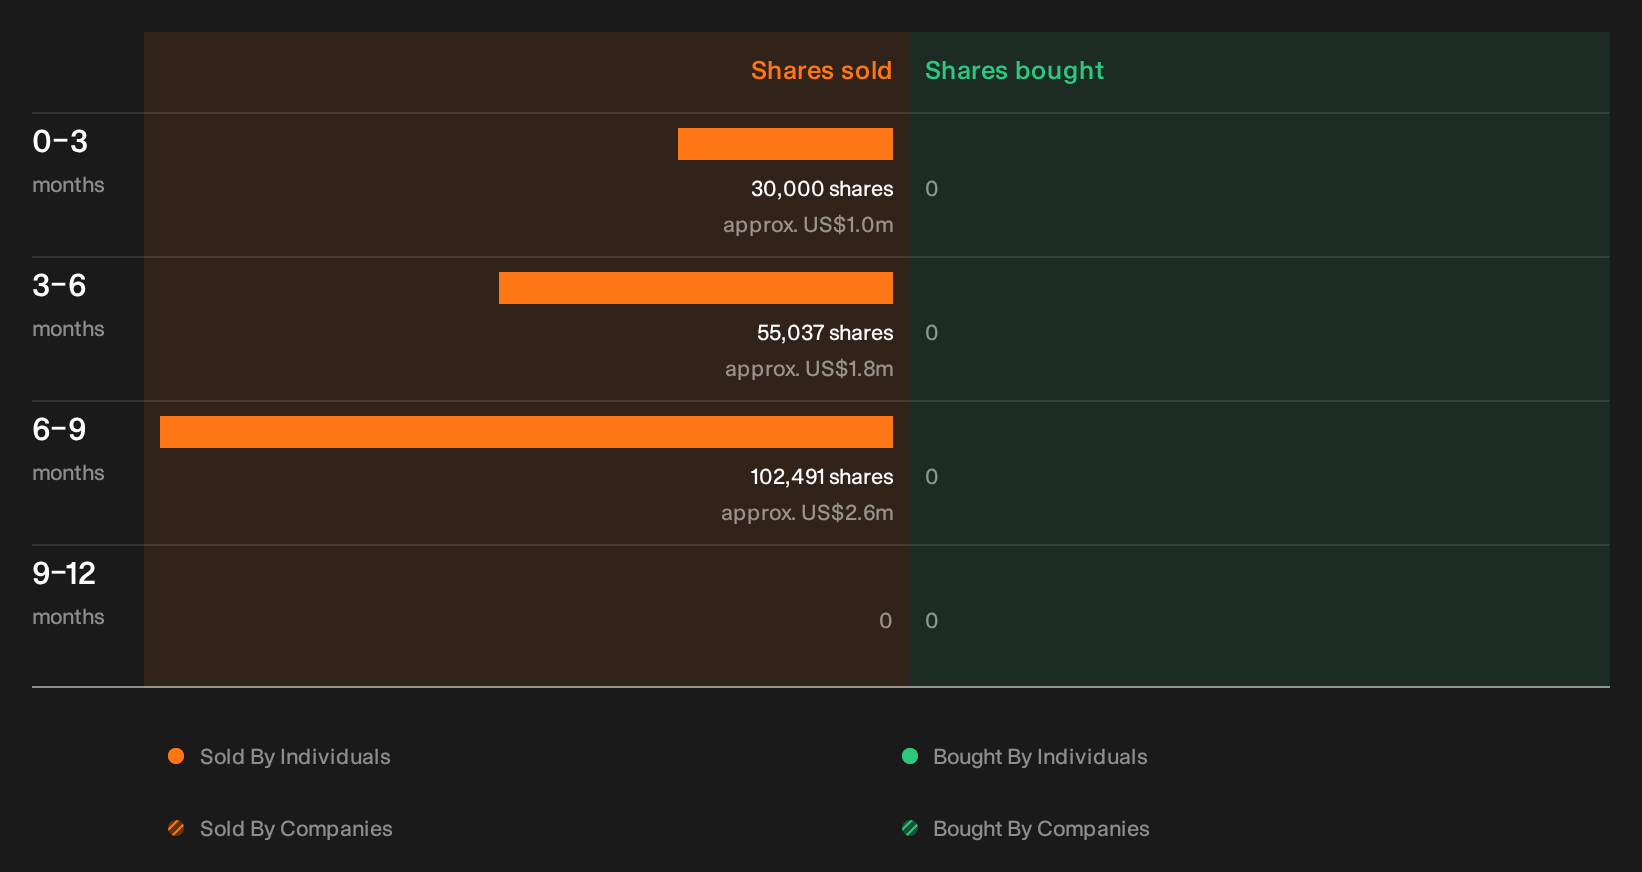
Price and returns are only part of the picture for EZCORP, since recent management share sales flagged by our checks raise questions about who sold, how much, and why it matters for you. See the recent insider selling flagged for EZCORP.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com