
Did Yalla Group's Fall Catch You Out? What Investors Missed
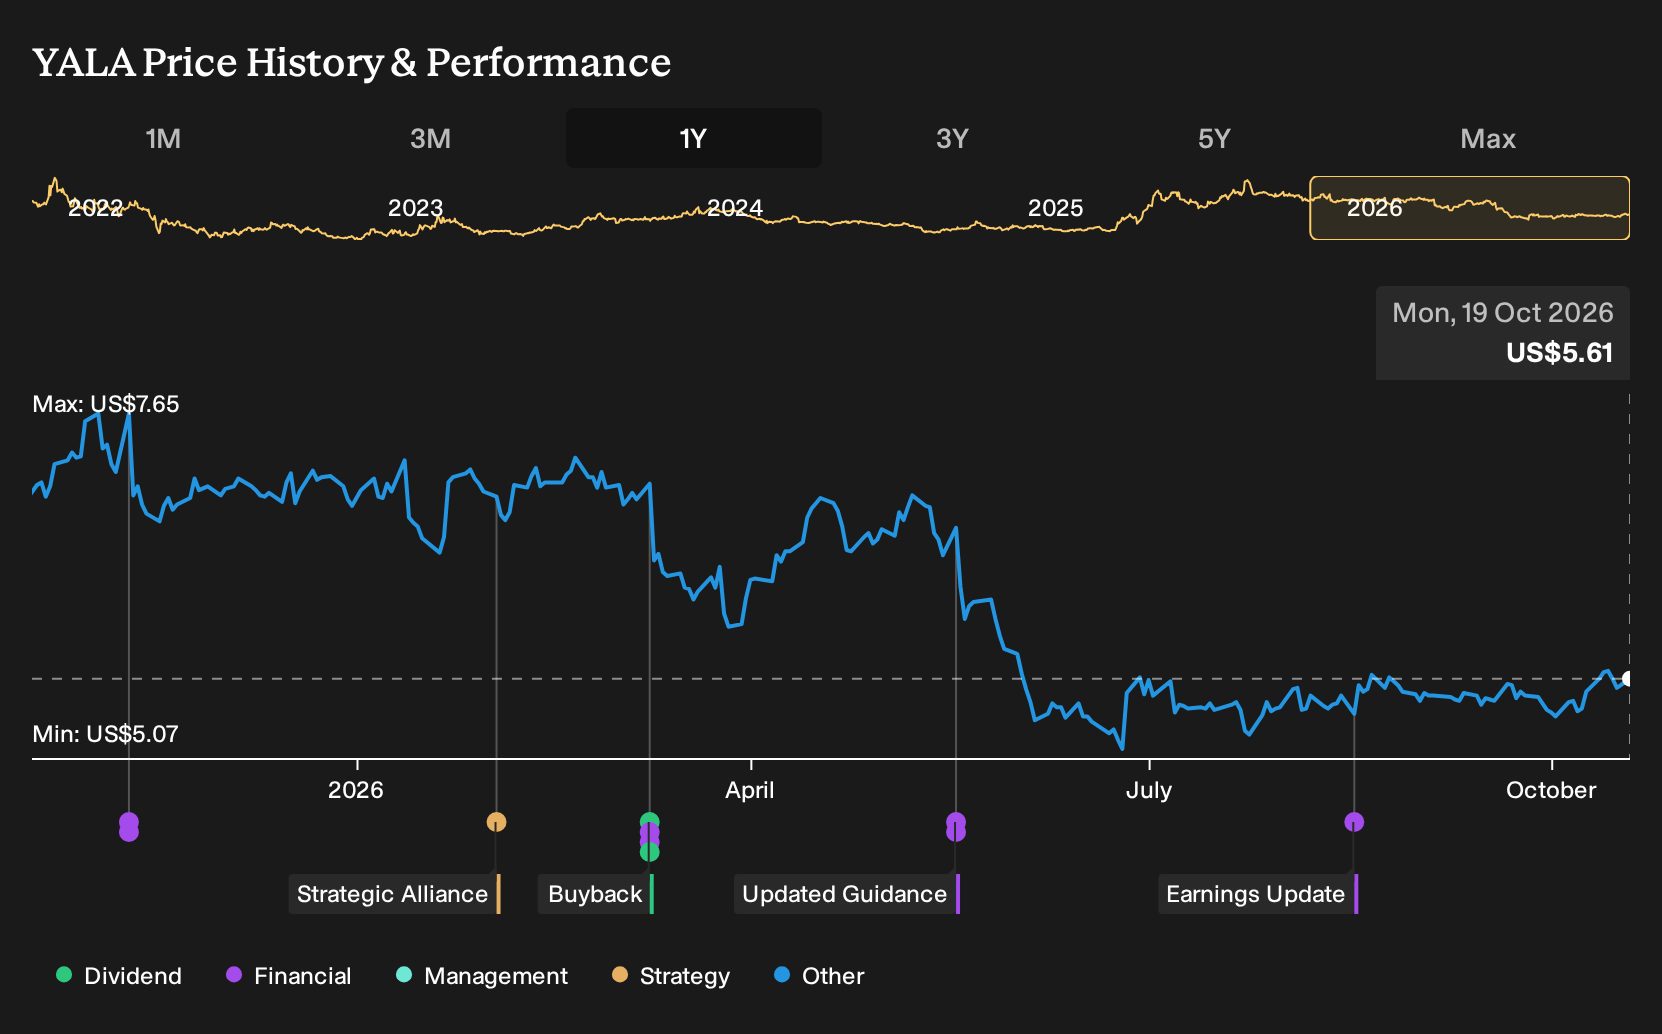
If you had looked only at user momentum and the upbeat talk on MENA gaming back in October 2025, Yalla Group might have seemed like a straightforward growth story. For Yalla Group shareholders, the loss over the past year was 21.0%, including dividends. The latest news now talks about softer revenue, lower net income and squeezed margins. If you were deciding whether to buy then, what warning signs were already hiding in plain sight?
This theme extends beyond Yalla Group. See which of 17 cryptocurrency and blockchain stocks may still merit a closer look.
The Argument You Would Have Been Weighing On Yalla Group
The shares cost US$6.96 at the start of the period, and investors were weighing two very different stories about where Yalla Group might go next.
The bullish narrative pointed to a Fair Value of US$9.27, a price its optimistic assumptions implied, built on 5.4% annual revenue growth and profit margins that were expected to ease only slightly to 39.6%.
The bearish camp worked off a Fair Value of US$6.5, again an implied price, and focused on margin pressure from rising MENA regulatory scrutiny and data privacy compliance costs.
What The Results Changed For The Yalla Group Thesis
The clearest new fact was Yalla Group's Q2 2026 results, where revenue and net income both slipped compared with Q2 2025 and net margin moved from 43.5% to 38.5%. That directly tested the bullish idea of only slightly softer profitability, while regulatory and cost worries from the cautious case looked more aligned with a thinner margin. On this evidence, the period supported the cautious case.
The key lesson is simple. When a thesis leans on resilient profitability, treat the net margin line as your tripwire and check whether each new report keeps it close to the original assumption.
What You Are Being Asked To Believe About Yalla Group Now
Yalla Group trades at US$5.61 today, while the selected Narrative sees Fair Value above that level. This reflects its own reading of the business rather than a settled truth.
The argument leans on new games, AI tools and buybacks to reshape earnings. Any buyer now has to judge whether those engines really can replace pressure on legacy chat products and thinner margins.
"The key factor is that investment in new games and AI tools converts higher marketing and R&D spending into game services that can represent a larger share of the revenue mix while margins remain resilient. The current valuation, large cash balance, and ongoing share repurchases suggest the market may not be fully pricing in this narrative’s view that Yalla Group is undervalued."
The price and this Narrative do not agree. → Uncover what this Narrative says Yalla Group is actually worth
Looking Past Yalla Group
Yalla Group asks you to think hard about attention. You are judging how sticky digital time spent can be.
Step back and a different business wrestles with the same challenge. It turns attention into advertising cash by matching intent with relevant messages.
That operator also sells access to powerful cloud tools. Customers rely on it to run AI-heavy workloads and everyday productivity.
The result is a company wired into search, video, email and workplace software. As attention and computing needs evolve, its influence remains an open question.
That argument has a Narrative and a number behind it. → See the company one Narrative values 26% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com