
Sun Hung Kai Properties (SEHK:16) Faces DCF Scrutiny, Is The Stock Fully Priced?
Recent discussion around Sun Hung Kai Properties (SEHK:16) focuses on a valuation gap. A Discounted Cash Flow model suggests the current market price exceeds the value implied by projected cash generation.
Over the past year, Sun Hung Kai Properties has shown stronger long-term rewards than short-term momentum, with a 1-year total shareholder return of 18.61% and a 3-year total shareholder return of 54.25%, in contrast to a 90-day share price return that has declined 12.49%.
The latest share price of HK$107.2 sits against that softer recent performance. This suggests investors have become more cautious in the near term as they weigh the DCF signals against the firm’s property pipeline, including projects such as the proposed taller residential towers at Tuen Mun A16.
Spot opportunities that echo the Sun Hung Kai Properties debate on value by scanning a curated set of 200 high quality undervalued stocks with stronger cash flow support.After a three year run that delivered strong total returns, followed by a recent 90 day pullback and a DCF flagging limited cash flow support, is most of Sun Hung Kai Properties’ upside already behind the stock or still ahead?
Most Popular Narrative: 7% Undervalued
On the most followed narrative, Sun Hung Kai Properties screens on a fair value of HK$115.3 against the last close of HK$107.2. That gap hinges on how resilient recurring income and development margins prove to be.
Although Sun Hung Kai Properties is adding large integrated commercial clusters in Hong Kong and Mainland China that are intended to support recurring rental income, the slight decline in Hong Kong net rental income and uneven office recovery suggest new supply could arrive into segments that are already under pressure. This may limit growth in rental revenue and keep rental margins subdued.
See why 0 investors see Sun Hung Kai Properties as 7% undervalued.
Result: Fair Value of HK$115.3 (UNDERVALUED)
Still, Sun Hung Kai Properties could challenge this cautious view if underlying profit rises further alongside lower finance costs, or if SUNeVision generates recurring data centre income at a faster pace.
Find out about the key risks to this Sun Hung Kai Properties narrative.
Another View: Sun Hung Kai Properties Through The P/E Lens
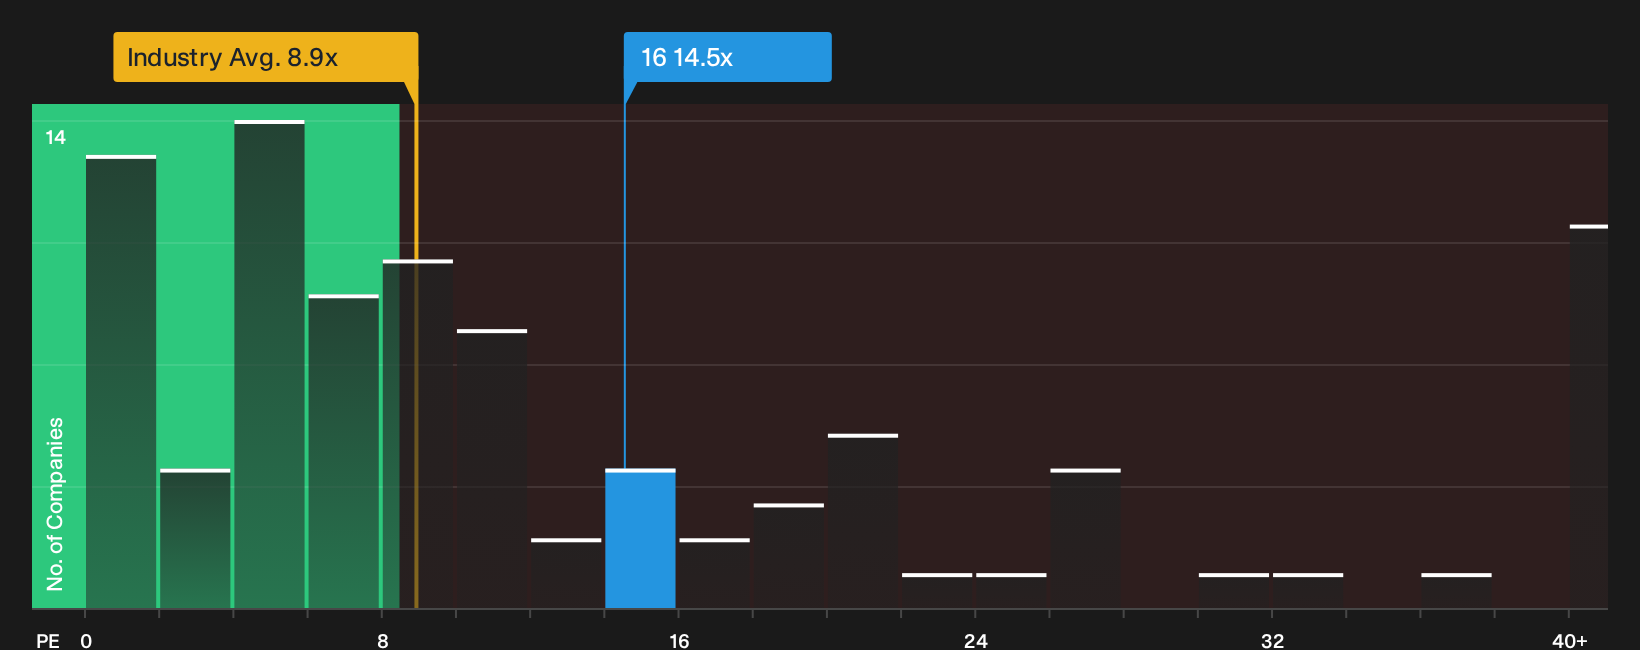
A second yardstick tells a different story. Sun Hung Kai Properties trades on a P/E of 14.5x. The broader Hong Kong real estate group sits nearer 8.9x, while the fair ratio for this stock is estimated at 15.8x. That mix points to richer pricing than peers but not stretched relative to its own earnings profile. Does that signal valuation risk, or a quality premium investors are willing to keep paying?
For a closer look at how this earnings multiple stacks up against sector norms and the fair ratio that the market could move towards, See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sun Hung Kai Properties for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 200 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Sun Hung Kai Properties can feel energising or uncomfortable, so move quickly, test the assumptions against the full data, and weigh the 3 key rewards and 1 important warning sign.
Looking for more ideas beyond Sun Hung Kai Properties?
If the Sun Hung Kai Properties debate has sharpened your thinking, keep that momentum and line up fresh opportunities that might fit your goals even better.
- Target potential mispricings by scanning a focused set of 200 high quality undervalued stocks that combine compressed valuations with stronger fundamentals.
- Build a sturdier core to your portfolio by checking the list of solid balance sheet and fundamentals (202 results) and sidestep weaker financial structures.
- Lean into future potential by reviewing the 613 high quality undiscovered gems before others start paying attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com