
ZoomInfo Technologies Is Down 62% Even Though Sales Rose
ZoomInfo Technologies hit headlines after a sharp revenue guidance cut, sweeping restructuring, and a wave of securities class actions, all following concerns about demand and its AI transition. Holding ZoomInfo Technologies over the past year would have meant a 62.5% loss, including dividends. If you had put money to work back on 19 October 2025, that is the result you would be trying to explain today. What exactly looked convincing enough then to back this story?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
The move put ZoomInfo Technologies in the middle of this trade. Scan 39 AI small caps for other companies exposed to it.
The Two Stories ZoomInfo Investors Had To Weigh
The shares cost US$10.08 at the start of the period, leaving investors in ZoomInfo Technologies choosing between two very different stories about its AI push and customer mix.
The bullish narrative put Fair Value at US$11.65, assuming revenue would rise 2.8% a year and profit margins would reach 15.1%, supported by AI tools like Copilot and a focus on larger enterprise clients.
The bearish view set Fair Value at US$6.79 and highlighted risks that the upmarket shift and heavy Copilot bets could slow revenue growth as smaller customers declined and margins stayed under pressure.
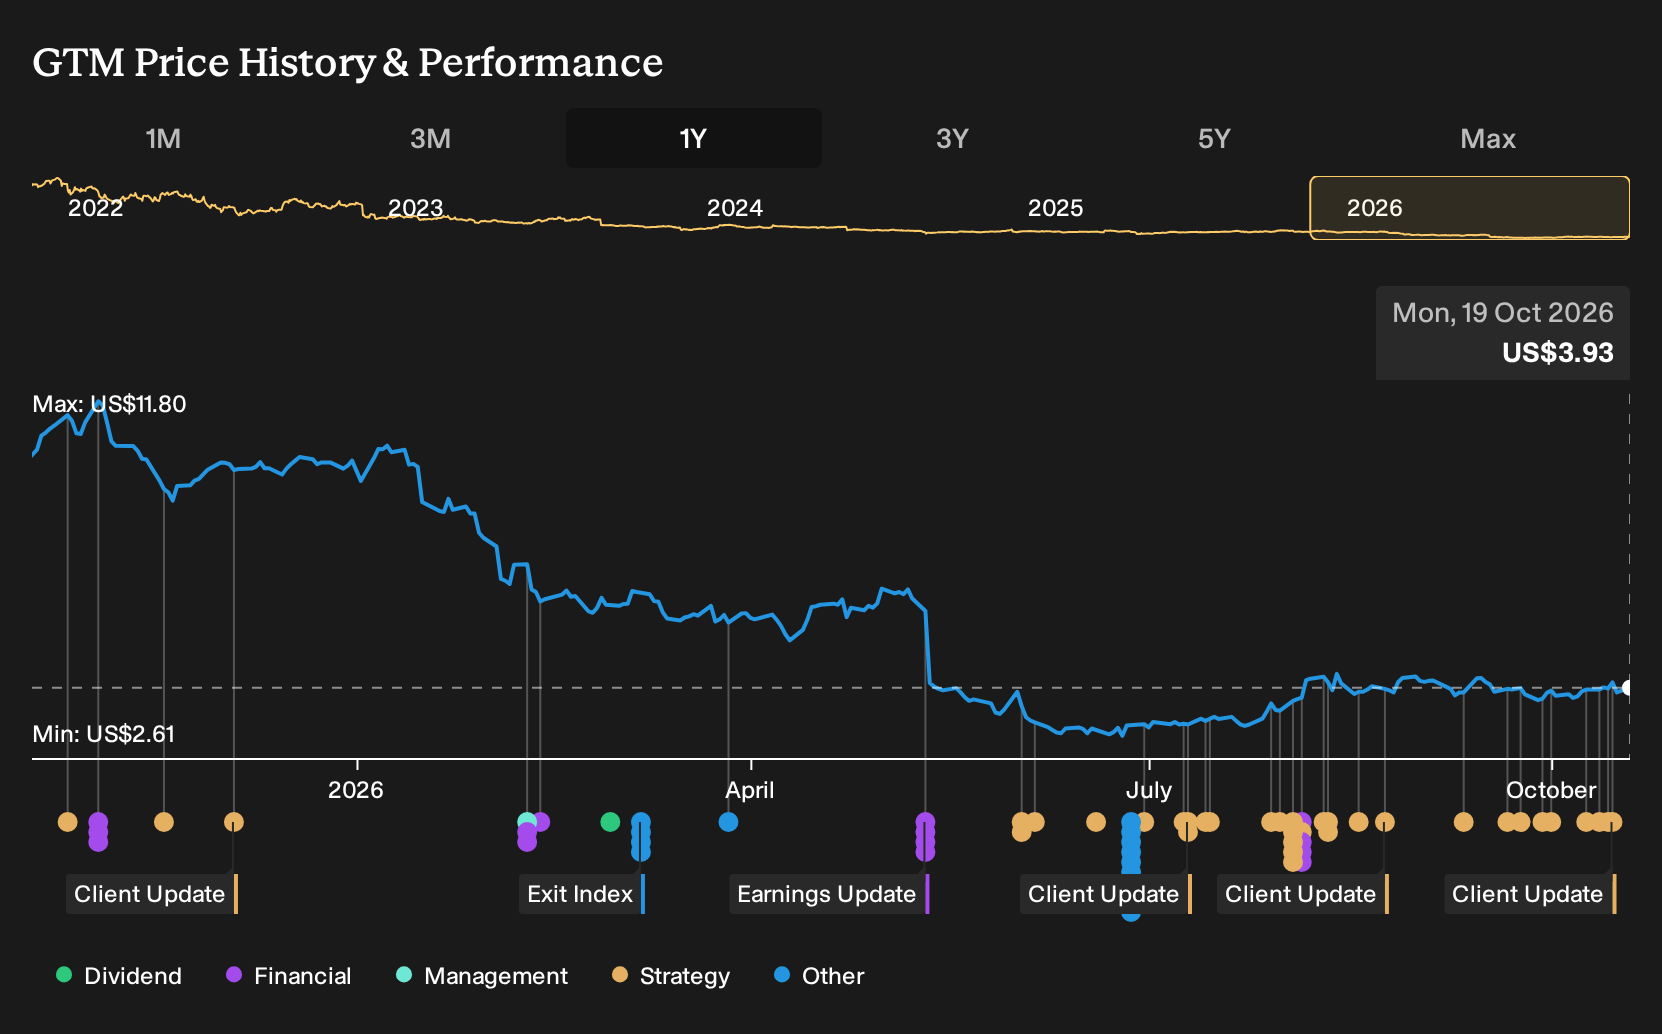
What The Results Changed For The ZoomInfo Technologies Argument
Q2 2026 results gave ZoomInfo Technologies investors new facts to work with. Revenue was US$310.4m compared with US$306.7m a year earlier, yet the business swung from a net profit of US$24.0m to a loss of US$643.7m. Net margin moved from 7.8% to a loss of 207.4%. That shift challenged the profitable AI and upmarket story and supported the cautious case.
The clear focus here was profitability. When revenue is roughly steady but net income and margin decline sharply, any similar company you assess should be reviewed in the same way. Compare management claims about AI driven efficiency or margin expansion with the reported net margin trend over several periods, not just with revenue growth.
What You Are Being Asked To Believe At US$3.93
Today ZoomInfo Technologies trades at US$3.93, with this selected Narrative arguing that its Fair Value sits above that level. The argument focuses on ZoomInfo Technologies becoming more of a headless go to market and automation layer rather than a simple sales data provider.
On that view, a buyer today would be assuming that upmarket data services, workflow orchestration and cost cuts can outweigh shrinking downmarket seats and softer net revenue retention.
"ZoomInfo Technologies is repositioning itself as a headless go to market context layer through GTM.AI, API access, and integrations into tools such as Replit, Slack AI, and Superhuman Go. This could widen its addressable usage beyond human sellers and support new data consumption revenue streams over time, with potential implications for revenue and gross margins."
One Narrative disagrees with today's price. → See where this Narrative says ZoomInfo Technologies should trade
How Could You Get There Earlier?
This company's disappointment is already part of the story. Your next idea could come from looking where the price and the possibilities still seem far apart. Here are three companies priced below our estimates.
- Company 1 - 33% below our estimate - turns a large backlog of AI infrastructure contracts into subscription and licensing revenue streams.
- Company 2 - 30% below our estimate - pushes coconut based drinks from niche shelves into mainstream retailers and expanding private label aisles.
- Company 3 - 45% below our estimate - converts a record backlog of data center and modular construction projects into higher margin buildouts and services.
Three companies from the same screener. Open all 35 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com