
Avery Dennison (AVY) Could Be 13% Undervalued After Leadership Change
Avery Dennison (AVY) drew fresh attention after appointing Helen Sheirbon as president of its Solutions Group, effective November 3, 2026, bringing senior operating experience from HP into a key business segment.
Recent trading suggests interest is building again in Avery Dennison. The 90 day share price return of 12.7% and 30 day share price gain of 4.7% contrast with a share price that is down 3.8% year to date. At the same time, the 1 year total shareholder return of 12.1% and 3 year total shareholder return of 8.7% show a mixed longer term picture as the stock trades around US$175.56.
Scan for other materials players with similar leadership change or momentum setups by reviewing the hand picked 35 high quality undervalued stocks alongside Avery Dennison.
Avery Dennison has already put up a solid run, yet the leadership shift and mixed return profile leave a real tension. Is the bigger payoff still ahead, or did most of it arrive in the latest rebound?
Most Popular Narrative: 13% Undervalued
Avery Dennison’s most followed narrative points to a fair value of $201.80, above the recent $175.56 close. This puts the new Solutions Group leadership into sharper context for long term holders who are weighing potential upside against recent gains.
The ongoing shift in the Materials Group toward high value categories like Specialty and Durable Labels, Embelex, Vestcom and new architectural films, along with continued growth in core label materials, may improve mix quality. This could support both segment revenue and adjusted EBITDA margins over time.
See why 12 investors see Avery Dennison as 13% undervalued.
Result: Fair Value of $201.80 (UNDERVALUED)
Still, Avery Dennison’s story can wobble if customer inventory prebuys unwind faster than end demand or if raw material inflation bites harder than pricing power.
Find out about the key risks to this Avery Dennison narrative.
Another View: Avery Dennison On Earnings Multiples
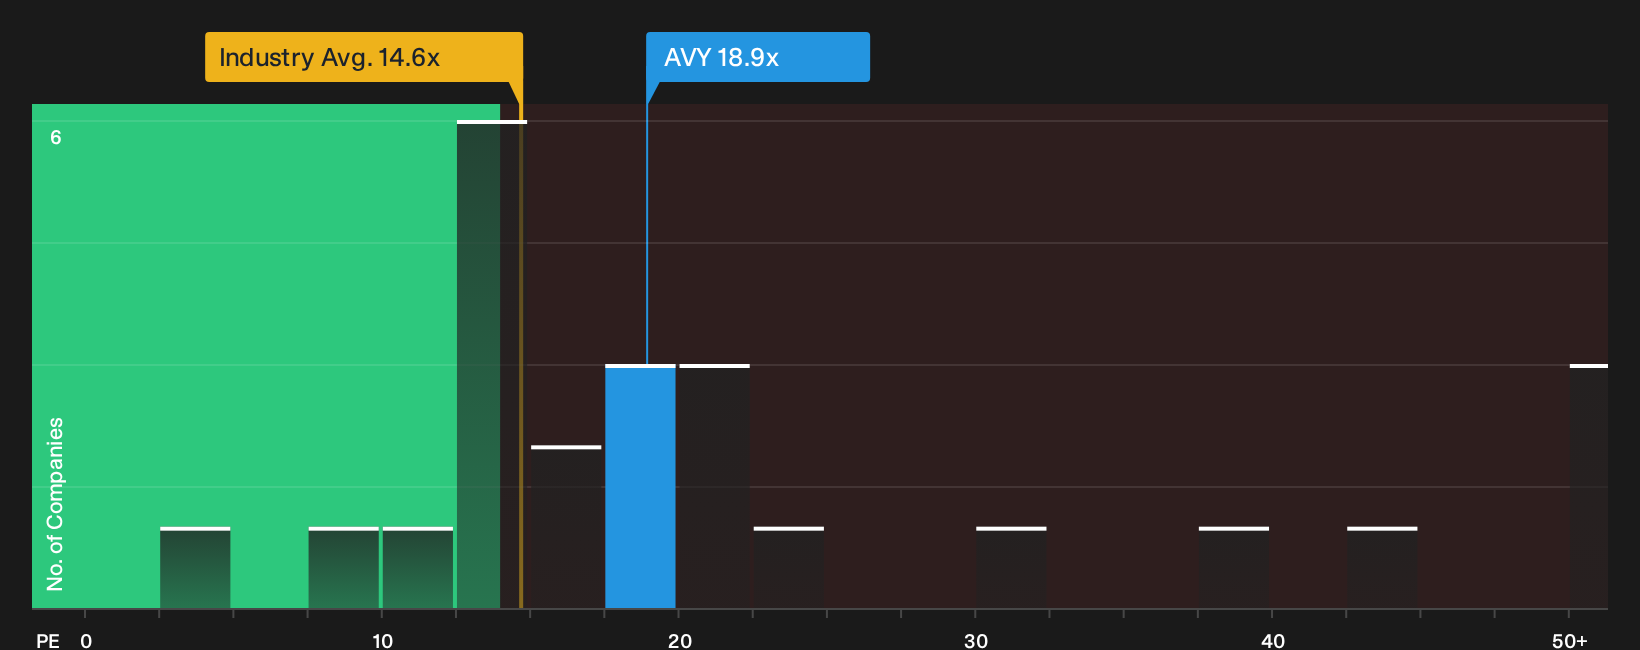
The picture changes once you step away from fair value models and focus on what Avery Dennison costs on earnings today. The stock trades on a P/E of 18.9x, which is higher than the global packaging sector at 14.6x and slightly above its own fair ratio of 18.5x.
That premium also narrows when you compare it with closer peers, where the average P/E sits at 24.9x. In practice, that means investors are paying more than the wider industry but less than similar companies, while the fair ratio indicates the multiple could move in either direction from here. Is that a margin of safety or a valuation risk building quietly in the background?
See what the numbers say about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and caution around Avery Dennison feels familiar, consider acting while the data is fresh and weigh both sides for yourself using our breakdown of 3 key rewards and 2 important warning signs
Looking for more Avery Dennison style investment ideas?
If Avery Dennison has sharpened your appetite for opportunities, do not stop here. Fresh ideas often appear where the crowd is not yet looking.
- Target potential bargains early by reviewing our hand picked 35 high quality undervalued stocks before the market fully prices them in.
- Strengthen your income playbook by scanning the 8 dividend fortresses that combine higher yields with resilient payout profiles.
- Reduce portfolio stress by focusing on the 32 resilient stocks with low risk scores that align with steadier balance sheets and more predictable business models.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com