
Baycurrent (TSE:6532) Gains Fresh Valuation Focus As Results And Dividend Lift Optimism
Baycurrent (TSE:6532) drew investor attention after reporting half-year sales of ¥92,913 million, net income of ¥22,209 million, and basic earnings per share of ¥148.63 from continuing operations.
Recent trading has been strong, with Baycurrent’s share price up 5.05% in the last session and posting a 35.02% 1 month share price return. Its 1 year total shareholder return of 47.64% and 3 year total shareholder return of 180.41% point to building momentum supported by the latest earnings and dividend increase.
Scan how Baycurrent’s post earnings momentum compares with other consulting and tech related plays by reviewing the hand picked 73 high quality undiscovered gems now catching investor attention.
Baycurrent now pairs solid consulting earnings and a higher dividend with a share price that has sprinted ahead in recent weeks. The main question is whether that business strength is already fully reflected in today's valuation.
Preferred P/E of 36.8x: Is it justified?
Valuation now leans heavily on what investors are willing to pay for each yen of Baycurrent’s earnings, and the current P/E of 36.8x sits at the center of that debate.
The P/E ratio reflects how many times current annual profit the market is pricing into the shares. For a consulting and tech focused group like Baycurrent, this often acts as a shorthand for what investors think about the durability of earnings and the quality of its contracts and client base.
Baycurrent is growing, with earnings reported to have risen by 23.7% over the past year and with revenue expected to expand by 18% per year. Earnings are also forecast to grow faster than the broader JP market and the firm is described as having high quality earnings with an outstanding 41.9% Return on Equity. A richer multiple can be one way the market expresses confidence that these characteristics will continue to support profits.
Even with that context, the 36.8x P/E is punchy compared to every reference point given. It is above the estimated fair P/E of 29.1x, far above the JP Professional Services industry average of 13.5x, and above the cited peer average of 17.2x. Those gaps are wide, suggesting the current price already bakes in a strong outlook and leaves less room for further re rating based purely on earnings quality.
Explore the SWS fair ratio for Baycurrent.
Result: Preferred multiple of 36.8x price-to-earnings (OVERVALUED).
Still, Baycurrent’s rich 36.8x P/E could reset quickly if consulting demand softens or if expected revenue and profit growth come in weaker than projected.
Find out about the key risks to this Baycurrent narrative.
Another View: What The SWS DCF Model Says About Baycurrent
The rich P/E paints Baycurrent as expensive, yet the SWS DCF model tells a different story. From a cash flow perspective, the shares at ¥10,710 sit about 26.2% below an estimated value of ¥14,508.83. That frames the recent rally as a possible discount rather than pure froth. Which signal do you trust more: earnings multiples or long term cash flows?
Look into how the SWS DCF model arrives at its fair value.
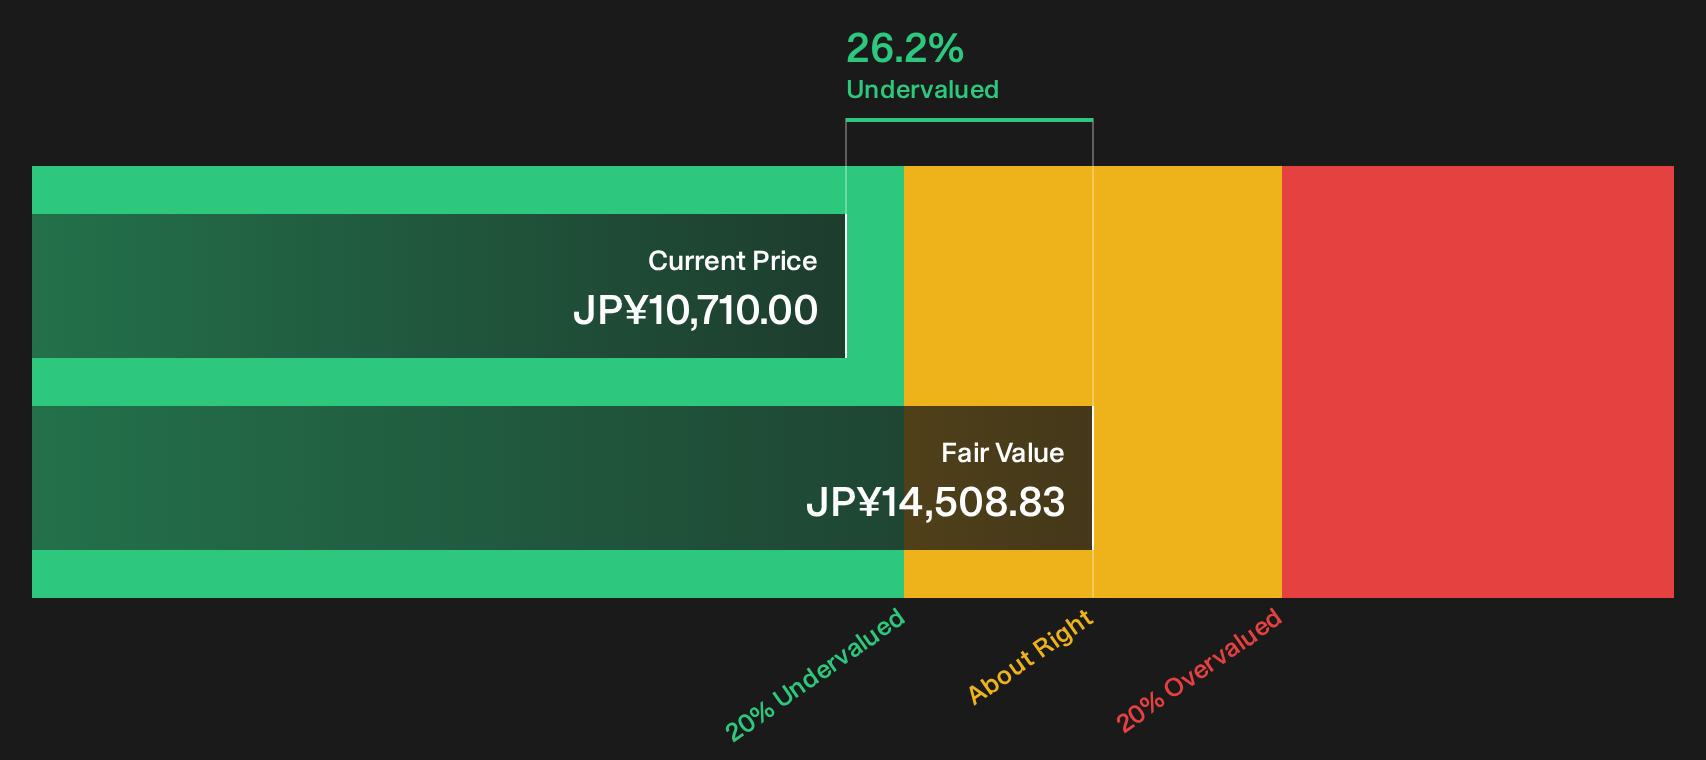
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Baycurrent for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Baycurrent is mixed. This is often when it can be useful to move quickly and test the story against the underlying data yourself. To see how the positives and concerns line up side by side, review the 3 key rewards and 1 important warning sign
Looking for more Baycurrent style investment ideas?
If Baycurrent has sharpened your interest, do not stop here. Fresh opportunities appear quickly, and missing the early moves can be costly over time.
- Target steady compounding by reviewing the 29 dividend fortresses that focus on income potential backed by stronger balance sheets and consistent cash generation.
- Hunt for mispriced quality through the 13 high quality undervalued stocks that highlight financially robust businesses trading at what may be discounted valuations.
- Reduce stress in your portfolio by scanning the 22 resilient stocks with low risk scores that filter for resilient operations and more stable risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com