
Nagase (TSE:8012), What Is Drawing Attention Now?
Nagase (TSE:8012) moved quietly higher, with the share price closing at ¥1,220.5, as investors weighed its diversified exposure to chemicals, plastics, electronics, and life sciences, with no single headline driving sentiment.
Recent trading has been quietly constructive for Nagase, with a 30-day share price return of 4.18% and a year-to-date share price gain of 24.86% contributing to a 1-year total shareholder return of 52.70%, which may indicate building momentum rather than a short-lived bounce.
Scan other quietly building momentum stories like Nagase by reviewing our hand picked 73 high quality undiscovered gems that sit off most radars but already show tangible traction in their numbers.
After a 52.70% 1-year total return and a share price near ¥1,220, the central question around Nagase is straightforward: do the current fundamentals still skew the risk reward in favour of new buyers, or not?
Price-to-Earnings of 12.4x: Is it justified?
Nagase now trades on a P/E of 12.4x, which puts the ¥1,220.5 share price on a richer earnings multiple than many Trade Distributors peers that sit closer to 10.8x.
The P/E ratio compares what investors pay per share to the profit generated per share. For a diversified operator like Nagase, spanning chemicals, plastics, electronics, and life sciences, this metric is a quick way to see how the market values its earning power against other listed businesses in the same space.
Here, the market is assigning a higher tag than both the Trade Distributors industry average of 10.8x and the peer group average of 10.9x. This suggests investors are currently willing to pay more for each unit of Nagase's earnings than for its closest comparables. Yet the estimated fair P/E of 15x is materially higher than the current 12.4x level. This points to a valuation that could shift if sentiment moved closer to that reference point.
Explore the SWS fair ratio for Nagase.
Result: Price-to-Earnings of 12.4x (ABOUT RIGHT)
Still, the story around Nagase can change quickly if demand weakens across its broad chemicals and electronics portfolio, or if currency swings compress reported earnings.
Find out about the key risks to this Nagase narrative.
Another view on Nagase’s value
The P/E picture makes Nagase look roughly in line with a fair ratio of 15x, yet the SWS DCF model paints a less generous story. On that view, the current ¥1,220.5 price sits above an estimated future cash flow value of ¥993.44, which leans toward overvaluation. Which lens deserves more weight in your process?
Investors who want to see how this cash flow view is built line by line can go deeper with the detailed model output, then judge for themselves whether the inputs feel conservative or optimistic. Look into how the SWS DCF model arrives at its fair value.
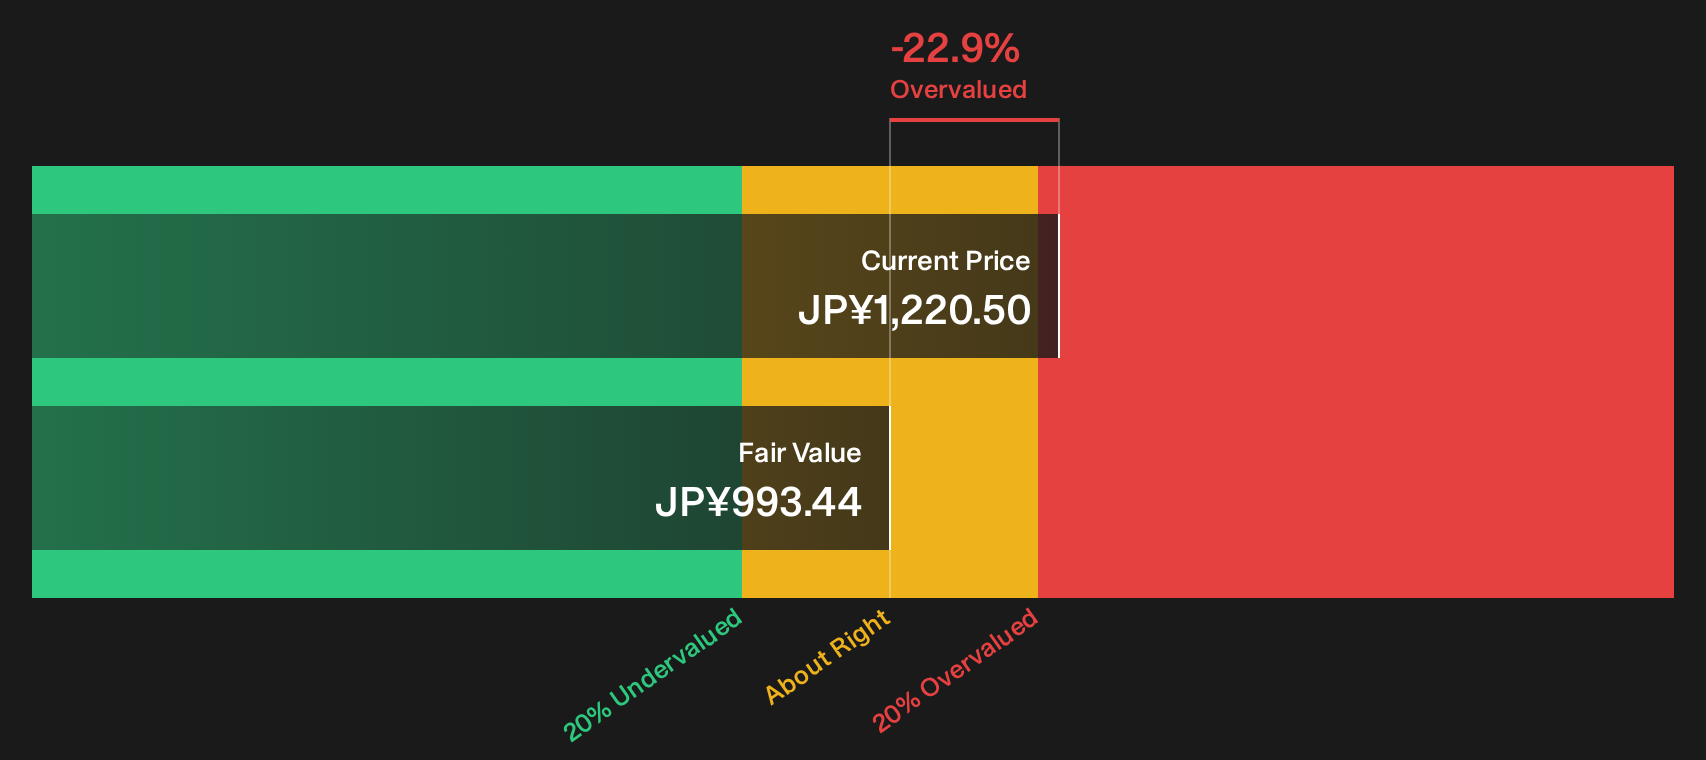
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Nagase for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of signals around Nagase feels finely balanced, it may be worth reviewing the underlying metrics yourself and deciding where you stand. To weigh both sides of the story in one place, start with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Nagase?
If Nagase has sharpened your focus, do not stop there. Broader idea sourcing gives you better context and more options when you commit capital.
- Target potential value opportunities by scanning a curated 13 high quality undervalued stocks that already pass quality and fundamentals checks.
- Prioritise resilience by reviewing a 22 resilient stocks with low risk scores that filters for companies with more defensive risk profiles.
- Get ahead of the crowd by tracking a 1 elite penny stocks with strong financials that already show solid financial underpinnings rather than pure speculation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com