
Riot Platforms (RIOT) Stock Could Be Overvalued On Its AI Data Center Shift
Riot Platforms has seen sharp swings in its share price in recent years, and the latest leg of that ride puts fresh focus on what investors are really paying for. With the stock now well below prior highs, the key question is how comfortably its current market value lines up with the revenue it generates.
- Over the past 5 years the share price has fallen 52.8%, which puts long term holders squarely focused on whether today's valuation still reflects the sales power of the business.
- Recent news around a shift from pure Bitcoin mining toward AI and high performance computing data centers, along with moving Bitcoin custody to BitGo Bank & Trust, can reshape future sales mix and capital intensity, which matters for how much investors may be willing to pay for each dollar of Riot Platforms' revenue.
- Your read on Riot Platforms is one view; the desks covering it have another. See what analysts think Riot Platforms's shares could be worth.
The issue now is whether Riot Platforms' share price is adequately supported by its sales when judged against the Fair Ratio benchmark.
Riot Platforms is only one way to play this theme, so it often helps to compare its swings in AI and crypto exposure with a basket of 17 cryptocurrency and blockchain stocks.
Is Riot Platforms Getting Expensive on Sales?
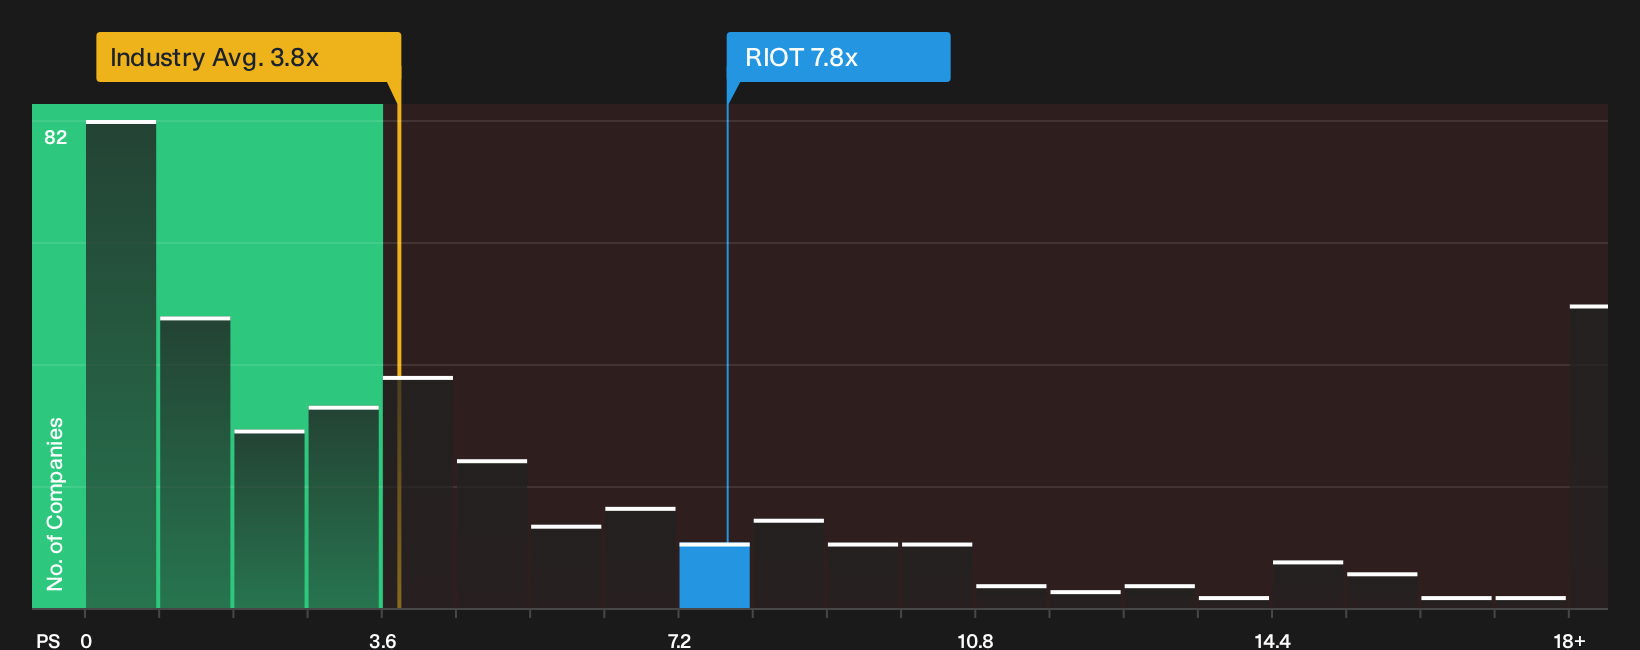
P/S suits Riot Platforms because revenue is still the cleaner anchor than earnings while the business invests heavily for AI and crypto infrastructure. On this yardstick the stock trades on about 7.8x sales, which is roughly double the wider software industry average of 3.8x and sits well below a broader peer group nearer 21.5x that leans heavily toward higher priced crypto and AI plays.
The Fair Ratio model, which adjusts the multiple you might expect for Riot Platforms based on its risk profile, sector and fundamentals, points to a lower valuation level than the current 7.8x P/S, so the shares screen overvalued on this framework. Because the recent push into AI and high performance computing data centers brings large upfront capital needs and uncertain long term contract economics, that richer multiple already bakes in a lot of optimism about how those projects will convert into recurring sales. Despite the shift of Bitcoin custody to BitGo Bank & Trust giving the crypto side a more regulated wrapper, the price tag per dollar of revenue still assumes a generous outcome. Explore the numbers behind Riot Platforms's P/S valuation.
The Riot Platforms Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Riot Platforms pick up exactly where this valuation puzzle leaves off, by spelling out which paths for future growth, margins and earnings would need to play out for the shares to look materially richer or cheaper than they do today. Each scenario treats Riot Platforms' fair value as a thesis about how the business might develop over time that you can revisit, rather than a one-off snapshot, and they are grouped together on the Community page.
One of the top community narratives on Riot Platforms: 56% undervalued
"Riot Platforms is building on its earlier plan to grow a scalable data center business by locking in a 20-year, 191 MW lease with a frontier AI lab and expanding AMD’s lease to 50 MW..."
Discover why this Narrative puts Riot Platforms at 56% undervalued.
Riot Platforms’ valuation still leaves one crucial piece of the puzzle
Price tags and revenue multiples only tell part of the story for Riot Platforms, because the people directing capital and the way they are rewarded can tilt the whole risk profile. See who runs Riot Platforms and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com