
Pinterest (PINS) Stock May Be Fully Priced On Current Earnings
Pinterest has delivered strong short term gains in recent weeks, yet over a longer horizon the stock has moved very differently, which raises a clear question about what investors are paying for its earnings today. With the share price at US$22.34 at the last close, the key issue is how that tag lines up with the underlying profit power of the business.
- The share price has fallen 55.9% over the past 5 years, which puts the focus squarely on whether current earnings can support a recovery story or point to a reset level for the stock.
- The company’s model relies heavily on turning user engagement into profitable advertising revenue, so any change in how efficiently those ad dollars translate into earnings can shift what looks reasonable to pay today.
- There is a second opinion on Pinterest worth weighing. See what analysts think Pinterest's shares could be worth.
The issue now is whether Pinterest’s current share price is appropriately aligned with the earnings the business is generating.
If you are comparing Pinterest with alternatives on the same question of what you pay for earnings, a focused stock screen can serve as a useful second reference point, such as 35 high quality undervalued stocks.
Does Pinterest Look Pricey on Earnings?
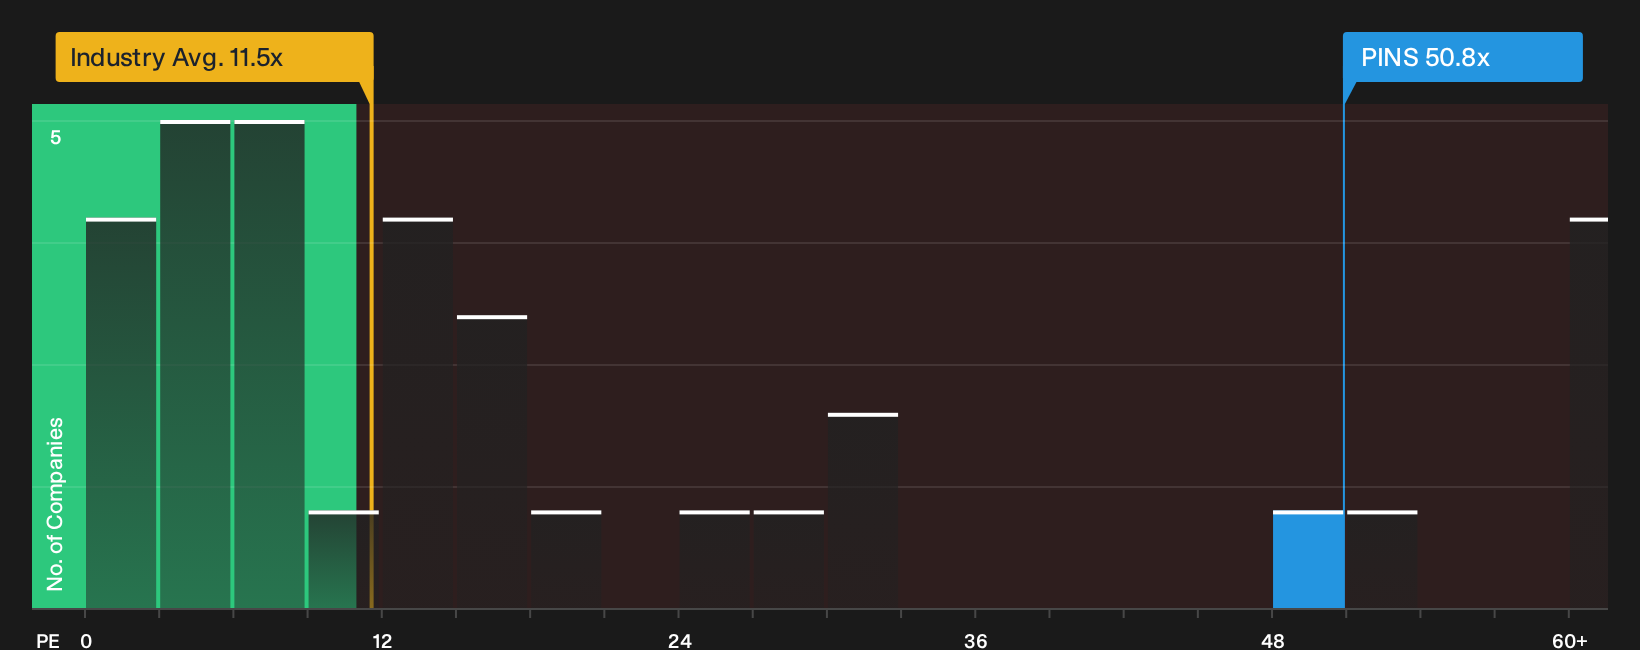
The P/E ratio suits Pinterest because earnings now sit at the center of how investors frame the story. On this metric, the stock trades on about 50.8x, which is far above the Interactive Media and Services industry average of roughly 11.5x. That is also well ahead of the wider peer group near 25.7x, so the market is attaching a clear premium to each dollar of profit the platform generates.
The fair multiple implied by the valuation model is lower than where Pinterest trades today, which points to an overvalued reading on this lens. To weigh whether that premium feels justified, you would need to look closely at how durable current profitability is, how efficiently new monetisation streams might scale and how much competitive pressure could eat into those earnings. The gap between the live P/E and the modelled fair level gives a sense of how much optimism is already embedded in the share price. Explore the numbers behind Pinterest's P/E valuation.
The Pinterest Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Pinterest pick up exactly where the valuation puzzle leaves you. They spell out what kind of growth, margins and earnings trajectory would need to play out for the current share price to look high or low. Rather than relying on a single P/E or model output, each scenario lays out the assumptions behind its estimate of fair worth, so you can compare those expectations with Pinterest's actual results as they are reported.
Community views on Pinterest split between investors who see under-recognised monetization potential and others who think rising costs and pricing pressure already test the current tag.
Bull case: 23% undervalued
"The current valuation implies that Pinterest’s share price does not fully reflect its record 640 million user base, lower-funnel skew, high free cash flow conversion…"
Discover why this Narrative puts Pinterest at 23% undervalued.
Bear case: roughly fairly valued
"The gap between more than 5x growth in paid clicks and much slower revenue growth suggests auction pricing and take rate may remain under pressure…"
Explore why this Narrative puts Pinterest at roughly fairly valued.
One more piece of the Pinterest puzzle before you make a move
Before you lean too hard on today’s earnings multiple, it helps to see how professional forecasters map out Pinterest’s revenue mix and profit profile a few years from now. Explore where analysts expect Pinterest to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com