
3 Indian Growth Stocks With Revenue Growth Up To 27%
Global food prices face fresh pressure as supply shocks and weather issues drag on, and that hits Indian households directly. Rising grocery bills can squeeze many listed businesses. It can also reward a smaller group of fast growing Indian companies where founders and insiders still own a lot, and stay strongly aligned with outside shareholders. This article highlights three such stocks from our screener that fit that profile.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where insiders are heavily invested in the outcome. However, if you want the standouts, these 39 high growth high conviction stocks are the most outstanding.
Rubicon Research (NSEI:RUBICON)
Rubicon Research is a specialty pharmaceutical player that leans on its own drug delivery platforms to build higher margin therapies. This focus aligns with the screener’s emphasis on fast growing, founder aligned businesses that use proprietary science rather than pure volume to drive their expansion.
Rubicon Research generates about ₹19.4 billion from pharmaceutical products such as generics, specialty formulations, APIs and related services. That basket is anchored by its RubiReten and RubiSRL delivery platforms, and the stock carries a market value of roughly ₹246.1 billion.
"Consistent R&D investment at roughly 10% to 11% of revenue, together with a track record of commercialising 88% of approved products, points to a deeper product basket that can support future revenue and earnings visibility."
The real swing factor now is how one less visible constraint on its capital structure ultimately affects pricing power and earnings durability.
That quiet constraint is exactly what the full narrative for Rubicon Research unpacks, showing how Rubicon Research’s capital choices could accelerate or cap what those platforms really earn over time.

Atlanta Electricals (NSEI:ATLANTAELE)
Atlanta Electricals manufactures power and special duty transformers for transmission, construction and other infrastructure linked sectors, tying it directly to India’s electrification build out. The business generated about ₹20 billion from transformer manufacturing in India and carries a market value near ₹130.4 billion.
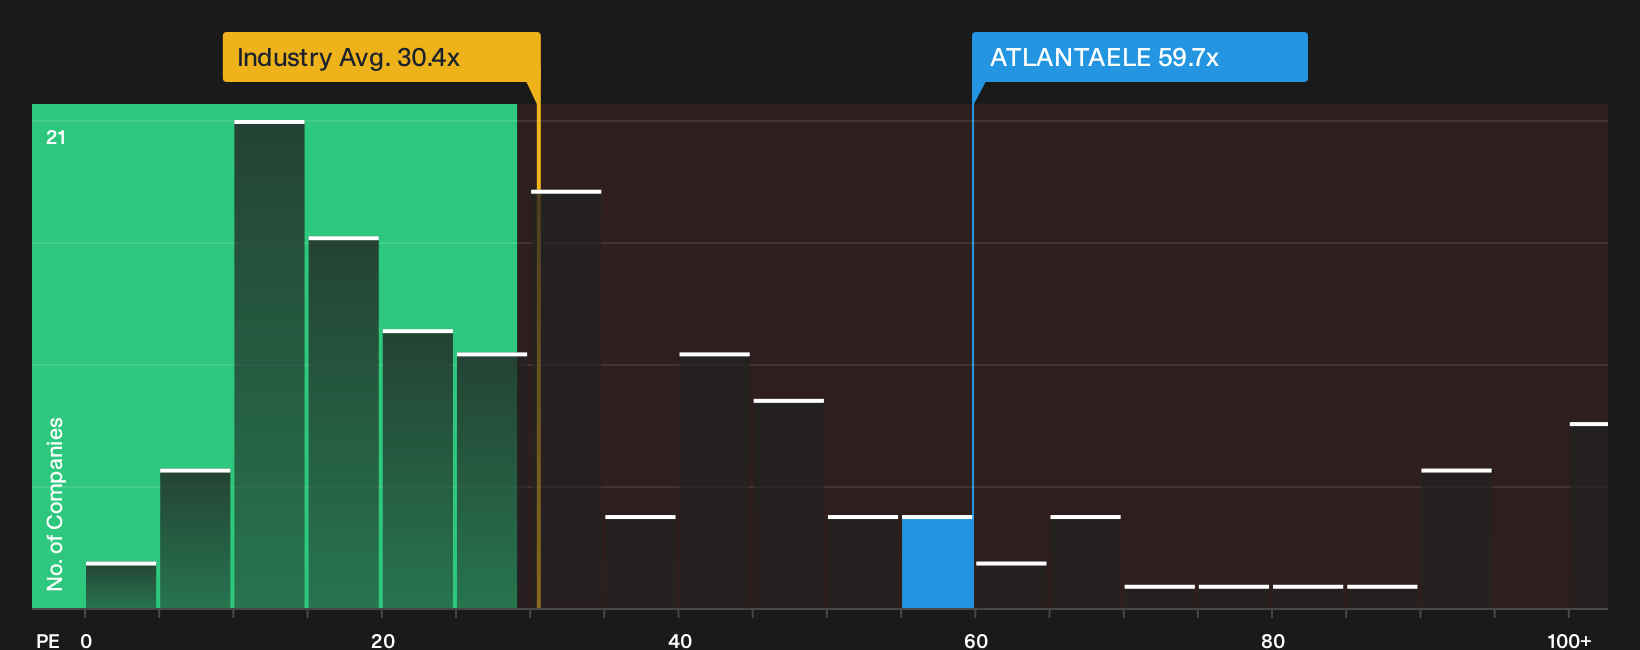
Atlanta Electricals combines 29.35% forecast earnings growth with a high 26.8% expected ROE and a strong transformer order pipeline tied to large grid projects. The stock trades on a rich 59.7x P/E, so future returns hinge on how pressure on that growth story ultimately plays out.
As that valuation tension builds, get the full 2 key rewards and 1 important warning sign to see what could justify the multiple or trigger a sharp reset.
Bajel Projects (NSEI:BAJEL)
Bajel Projects runs EPC work for extra high voltage transmission and distribution projects that plug directly into India’s electrification and grid expansion story. It earns about ₹27.5b from power transmission and distribution contracts and has a market value near ₹19.4b.
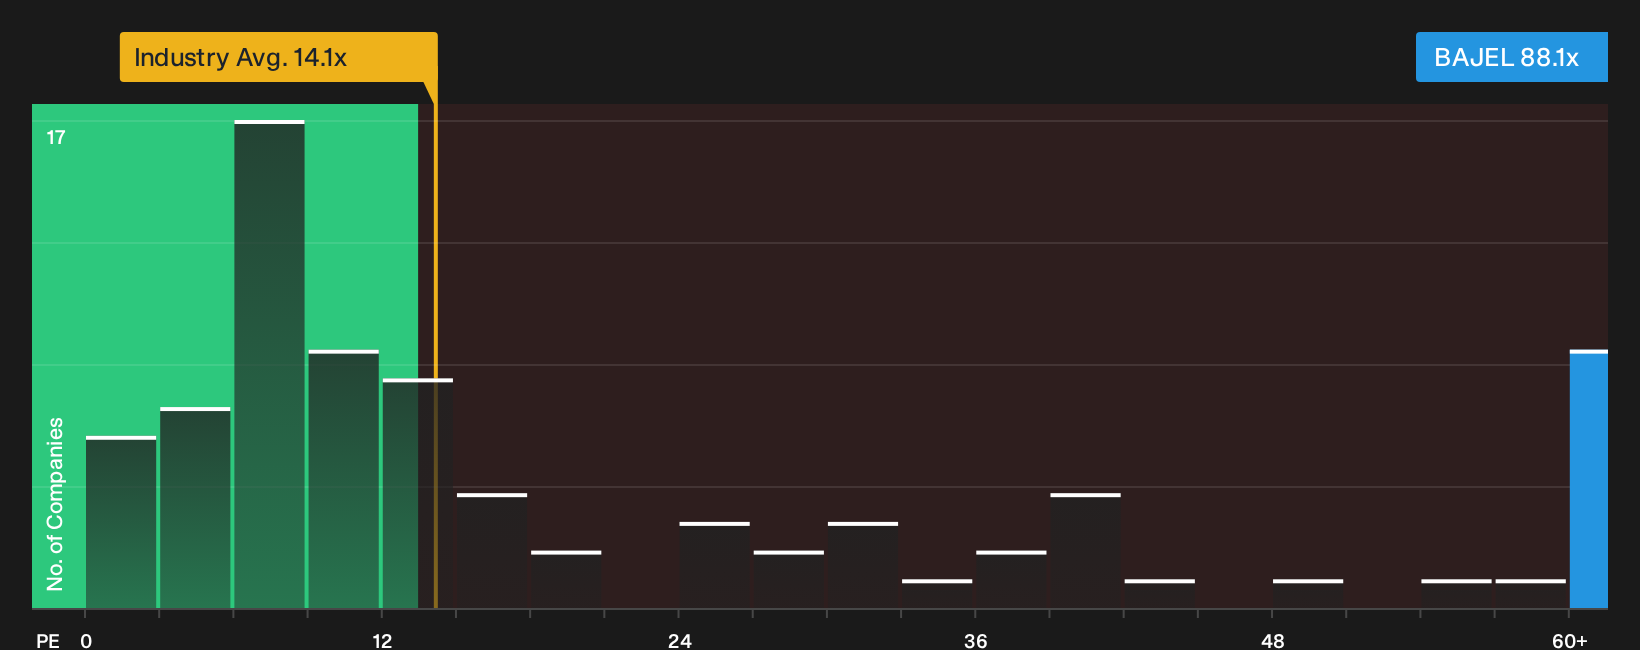
Bajel Projects ties into the fast growing, high insider ownership theme through its reported 71% earnings growth last year and a revenue forecast of around 27% a year. At the same time it has been winning ultra mega EPC orders in India and overseas. Investor interest focuses on how this rapid order inflow interacts with very thin margins and an 88.1x P/E, particularly in light of potential pressure on funding and execution.
That pressure point could make or break Bajel Projects’ next phase, so tap into the analysis report for Bajel Projects to see whether rapid orders are masking deeper execution risks.
Seeking Fresh Alternatives Beyond These Stocks?
Fresh ideas move first. Once a breakout theme catches momentum, ideal entry points can be gone before the crowd even looks. Scan these curated shortlists while it matters and get in early.
- Spot strong balance sheets before they get fully priced by using the curated list of solid balance sheet and fundamentals (202 results) that surfaces resilient businesses buyers may not have caught yet.
- Ride potential cash flow resilience as rates and inflation shift by scanning the hand picked 217 dividend fortresses built for investors who want income with backbone, not guesswork.
- Position ahead of possible infrastructure momentum by reviewing the focused 42 power grid technology and infrastructure stocks that filters companies tied to grid upgrades while they are still under the radar for now.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com