
What NatWest Group Doubters Got Wrong
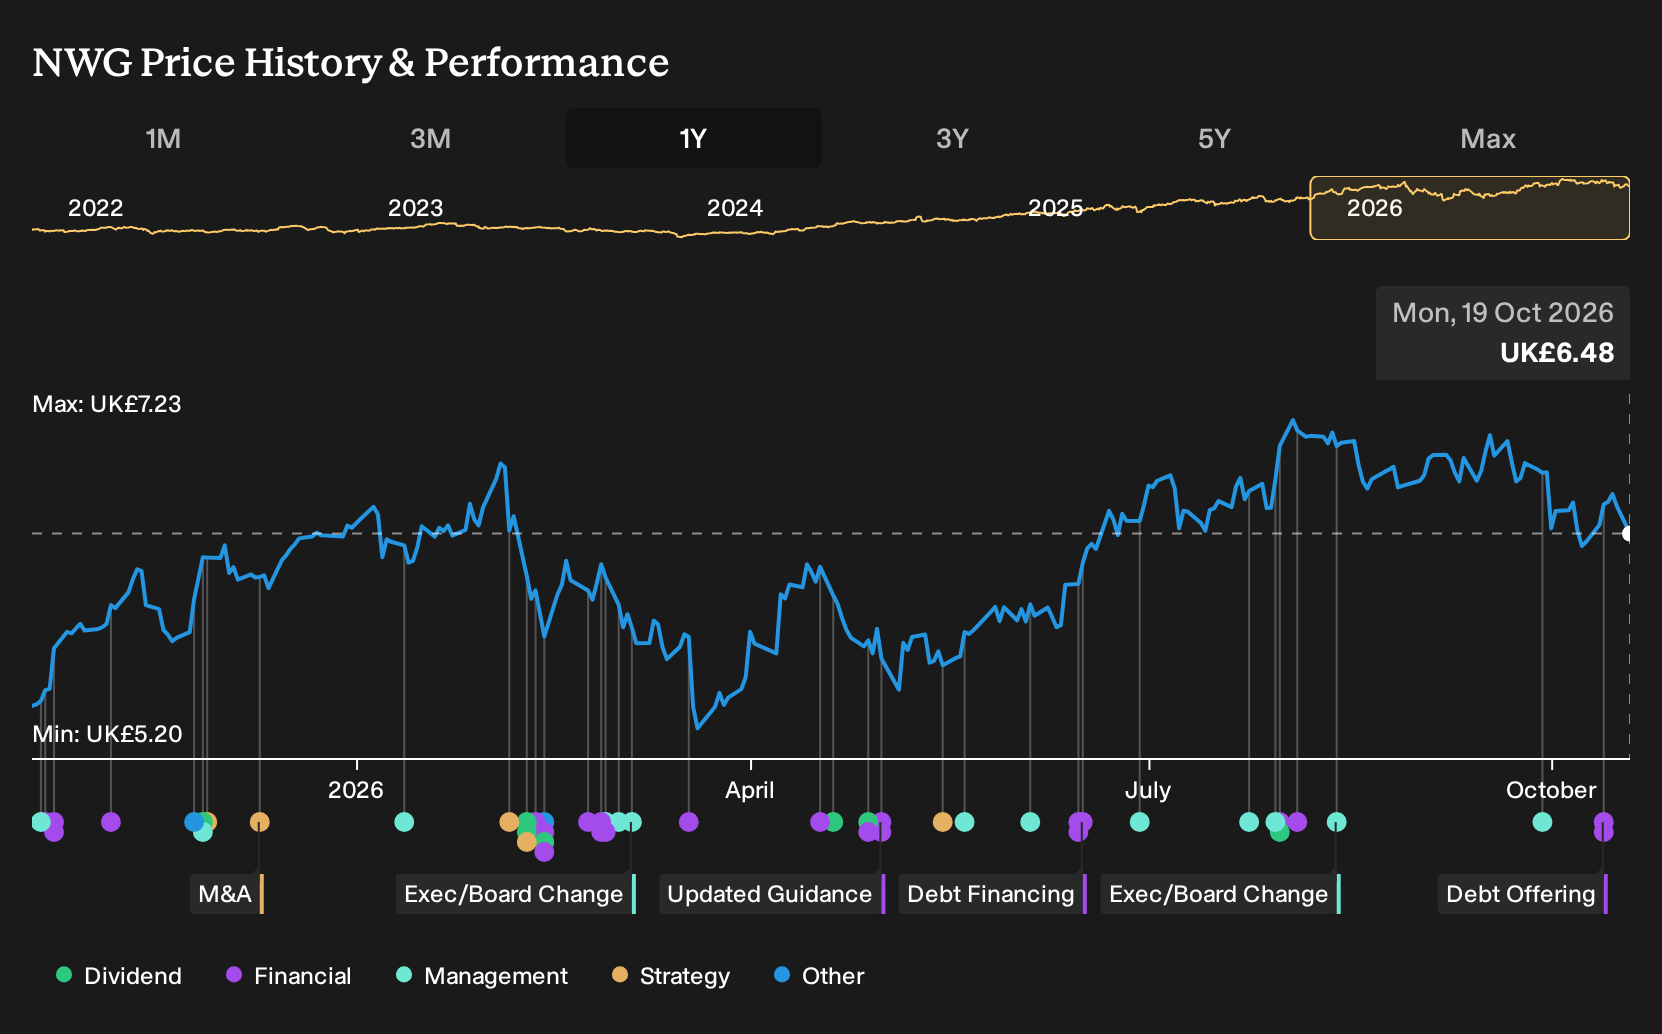
Holding NatWest Group over the past year would have returned 28.2%, including dividends. If you had been weighing a purchase back on 19 October 2025, you were looking at a bank pouring money into AI partnerships, digital overhauls and sustainable finance targets, while analysts argued over whether that spending justified a richer P/E or a discount. The real question now is which of those moving parts mattered most to that outcome.
NatWest Group has already moved. See which of 8 high quality undervalued stocks still trade below our estimates.
The Two NatWest Stories Investors Had In Front Of Them
The shares cost £5.32 at the start of the period, and NatWest Group investors were weighing two very different but plausible futures.
On the upbeat side, the digital and sustainable finance Narrative pointed to a Fair Value of £5.99. This was a notional price implied by assumptions such as 5.9% annual revenue growth and a 28.9% profit margin built on AI, cost rationalisation and climate lending targets.
The more cautious AI partnership Narrative put Fair Value at £4.8 and leaned on slower 1.3% revenue growth, while flagging execution and technology risks around the OpenAI tie up.
What The NatWest Evidence Actually Showed
The clearest datapoint arrived in Q2 2026. NatWest Group reported revenue of £4,364m and net income of £1,603m, with net margin at 36.7% compared with 32.4% a year earlier. That combination of higher revenue, higher profit and a fatter margin lent more weight to the upbeat digital and sustainable finance case than to the cautious AI partnership narrative.
The useful takeaway is simple. When an investment pitch leans on efficiency and technology, it can be treated as a claim about future net margin. Track that figure through each results release to see whether the story is turning into stronger economics.
What NatWest Group’s Price Now Bakes In
Today NatWest Group trades at £6.48. This selected narrative sees fair value above that level, tied to a shift toward fee-based wealth, payments and capital-light corporate lending supported by AI-driven cost efficiencies.
The question is whether fee income growth and AI-supported cost control can keep offsetting pressure on lending spreads and funding costs over time.
"Completion of the Evelyn Partners acquisition at the end of June 2026, which more than doubled NatWest Group assets under management and administration to £131b and is expected to lift group fee income by about 20%, sets up a larger mix of capital-light, recurring revenue that could support earnings resilience relative to pure interest income."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
How Could You Get There Earlier?
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 19% below our estimate - targets everyday sports supplement use as gyms and wellness routines expand.
- Company 2 - 34% below our estimate - channels investor capital into fee-earning renewable projects and social infrastructure assets.
- Company 3 - 23% below our estimate - attracts senior lawyers to a tech-led platform exchanging fixed offices for flexible fee-sharing.
Three companies from the same screener. Open all 9 companies with the balance sheet to back it up →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com