
AIA Group (SEHK:1299) Shows Strong Capital Discipline, Is It Still A Bargain?
Recent commentary on AIA Group (SEHK:1299) highlights returns on invested capital that exceed its cost of equity, alongside digital spending and disciplined balance sheet decisions that support efficiency and steadier cash generation for shareholders.
Recent trading in AIA Group has been choppy, with the share price down 4.5% over the past month and 12% year to date. However, a 3% one year total shareholder return and 19.1% three year total shareholder return point to longer term momentum that has rewarded patient holders.
Scan beyond AIA Group and compare other insurers and financials that show efficient capital use and disciplined balance sheets with the 231 resilient stocks with low risk scores.
AIA Group appears to be a high quality insurer based on its financial metrics, yet the share price has trended weaker this year. This raises an important question: does that gap signal potential value, or does it serve as a fair warning about what investors are willing to pay today?
Most Popular Narrative: 29.8% Undervalued
AIA Group last closed at HK$73.30 against a widely followed narrative fair value of HK$104.36. This frames the current share price as a sizeable discount and puts the focus squarely on whether that gap reflects mispricing or embedded risk.
The company's focus on high-value protection and low-guarantee fee-based products (now nearly 90% of new business) has resulted in resilient, predictable cash flows and strong margins, supporting sustainable earnings and embedded value growth. This positions AIA defensively against interest rate volatility and market cycles, underpinning profitability.
See why 25 investors see AIA Group as 30% undervalued.
The most followed narrative applies a 7.02% discount rate to those projected cash flows and earnings, then compares the outcome with the current HK$73.30 trading level. That approach implies around a 30% discount to fair value, which is meaningfully wider than the 40.6% upside implied by the analyst consensus target relative to the same market price.
Analysts contributing to this view are not uniform in their expectations, with price targets for AIA Group ranging from HK$81.02 to HK$121.01. Yet the shared assumption set is clear, built around mid single digit revenue growth, profit margins above 30%, and a future P/E multiple of 18.1x applied to earnings that are projected to reach HK$9.3b equivalent by around 2029.
For investors, the key judgement is whether those long term earnings and margin assumptions feel reasonable given AIA Group's Asian life insurance footprint, or whether the current market price already reflects more conservative outcomes. That decision sits at the intersection of your view on future regulation, competition from digital insurers, interest rate conditions across key markets, and the durability of the firm's high quality earnings profile.
Result: Fair Value of HK$104.36 (UNDERVALUED)
Still, the narrative can break if tighter regulations in key Asian markets squeeze product economics, or if digital first insurers chip away at AIA Group's pricing power.
Find out about the key risks to this AIA Group narrative.
Another View: Market Ratios Point To A Richer AIA Group
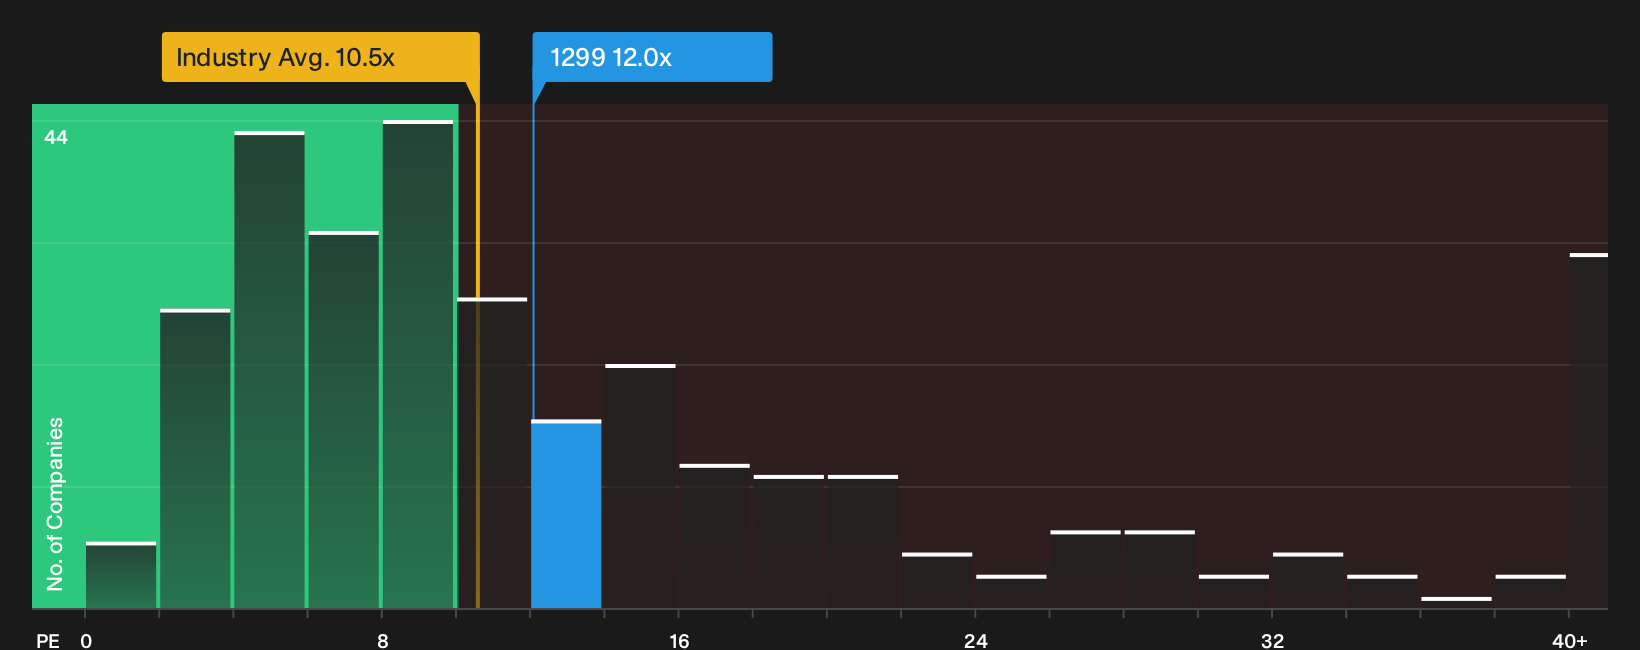
There is a very different read when you shift from cash flows to simple market ratios. AIA Group trades on a P/E of 12x, compared with 10.5x for the Asian insurance sector and a fair ratio estimate of 6.5x. That gap leans toward valuation risk rather than obvious mispricing. So is the discount to fair value a genuine opportunity, or is the market just reluctant to pay up for these earnings?
To see how that premium compares across peers and what it could mean if the share price moved closer to the fair ratio, take a closer look at the valuation breakdown with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Conflicting signals around AIA Group's value can feel confusing, so treat this as a starting point and pressure test the numbers yourself without delay. To see which specific positives analysts are focusing on, take a closer look at the 4 key rewards.
Looking for more investment ideas beyond AIA Group?
If AIA Group already sits on your radar, broaden your opportunity set with a few focused screens that surface different types of potential candidates quickly.
- Target resilient cash generators by reviewing companies that pass a list of solid balance sheet and fundamentals (202 results).
- Hunt for mispriced quality by scanning a curated list of 199 high quality undervalued stocks before the crowd pays attention.
- Spot early-stage potential by sorting through 134 elite penny stocks with strong financials that pair smaller market caps with stronger underlying financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com