
Did Record Backlog Just Shift Comfort Systems USA's (FIX) Investment Narrative?
- Comfort Systems USA recently reported that it entered the third quarter of 2026 with a record US$14.1b backlog, heavily weighted toward data centers, technology infrastructure, and mission critical projects that can support mechanical, electrical, and modular construction work.
- The same backlog strength and technology focused mix that support Comfort Systems USA's operations are paired with a premium 27.8x forward P/E multiple. This indicates that investors are closely watching how efficiently this contracted workload converts into cash flow and returns on capital.
- We will examine how Comfort Systems USA's investment narrative is shaped by record backlog levels heading into its third quarter 2026 earnings release.
Compare Comfort Systems USA's record project pipeline with other contractors plugged into data centers and mission critical infrastructure by scanning the hand picked 55 AI infrastructure stocks shaping this build out cycle.
Comfort Systems USA Investment Narrative Recap
For a shareholder in Comfort Systems USA, the core belief is simple. Large, complex mechanical and electrical work tied to data centers and industrial buildouts keeps flowing into backlog, then turns into high quality earnings and cash. The record US$14.1b pipeline heading into Q3 2026 keeps that thesis intact, as long as execution remains disciplined.
The key near term catalyst is how efficiently that technology heavy backlog converts to revenue, margin and free cash flow in the upcoming Q3 print. The main risk is any cooling in AI or semiconductor construction, or policy delays, which could slow awards and stretch project timing at a point when the stock already carries a premium multiple.
The most immediate news for Comfort Systems USA is the Q3 2026 earnings release scheduled for October 22, with results landing after the close. That update arrives at the intersection of record backlog, expanding modular capacity and a forward P/E of 27.8x, which together frame how tightly current expectations are anchored to strong operational delivery.
With no fresh announcements beyond the earnings date itself, the Q3 call becomes the event that can either reinforce or challenge the current narrative around technology driven demand, high returns on capital and free cash flow generation. For you as an investor, the focus likely sits on backlog conversion, modular returns and any commentary on the durability of AI and data center projects.
Comfort Systems USA Forecasts and Analyst Assumptions
Comfort Systems USA's narrative projects US$19.6b revenue and US$2.9b earnings by 2029. Analysts are assuming revenue growth of 20.3% per year, and this outlook implies earnings would roughly double, with an increase of about US$1.5b from US$1.4b today.
Uncover why Comfort Systems USA's fair value indicates a 50% potential upside to its current price before this valuation gap starts to close.
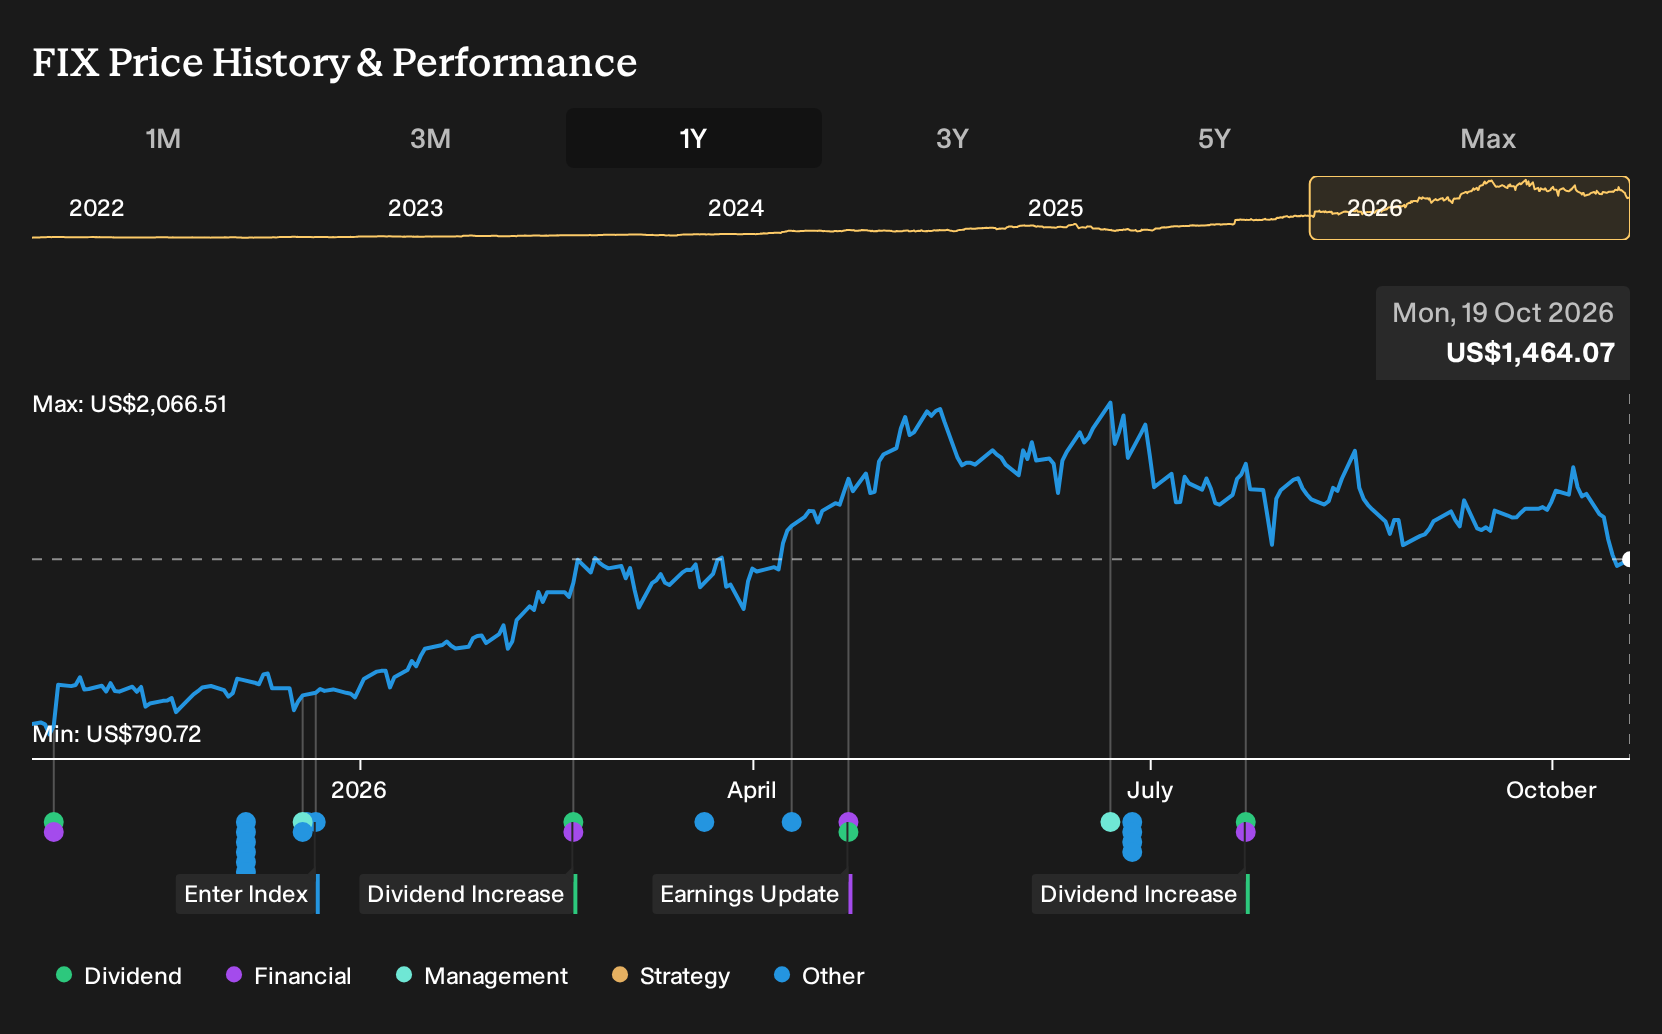
Exploring Other Perspectives
Some of the most optimistic analysts focus on a different catalyst for Comfort Systems USA. They highlight multiyear hyperscaler commitments and assume revenue could reach about US$20.7b with earnings of roughly US$3.1b by 2029. You can read those pre earnings assumptions as a reminder that views may shift sharply once new Q3 data lands.
Explore 5 other Comfort Systems USA fair value estimates, including one that suggests as much as 81% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your Comfort Systems USA research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Comfort Systems USA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Comfort Systems USA's overall financial health at a glance.
Looking for more Comfort Systems USA style ideas?
If the Comfort Systems USA story has you thinking about where else contracted cash flow, balance sheet strength, or income potential might show up, the Simply Wall St Screener can help you cast a wider net across similar opportunities.
- For investors who want potential mispricings with quality fundamentals, review a curated 35 high quality undervalued stocks that may offer more attractive entry points than widely followed large caps.
- If capital preservation comes first for you, filter for a 32 resilient stocks with low risk scores that screens for resilient businesses with more measured risk scores.
- For those building a portfolio around dependable income, scan a 8 dividend fortresses that focuses on companies offering higher yield alongside stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com