
Western Digital (WDC) Rides A Chip Rebound, Is It Still Above Fair Value?
Western Digital (WDC) is back in focus after a sector wide rebound in chip and tech stocks, as easing borrowing costs and AI driven optimism lifted sentiment across major semiconductor names.
Over the past year Western Digital has swung sharply, with the share price up 87.65% year to date and the 1 year total shareholder return at 190.35%. This comes even after a 30 day share price decline of 20.20% and a 90 day fall of 35.77%, so momentum has cooled in the short term while the longer run performance trend remains very strong.
Scan how Western Digital compares with hand picked AI infrastructure peers by checking the 55 AI infrastructure stocks now that chip stocks are back in the spotlight.
Western Digital has participated in a powerful rebound and still shows strong longer term returns. After that kind of run and a recent pullback, a key question is whether the current price fairly reflects the storage business on offer.
Most Popular Narrative: 6.8% Overvalued
Western Digital last closed at $352.21, while the most followed narrative pegs fair value at $329.76. The current price sits a little above that storyline and turns the spotlight onto how durable today’s economics really are.
A quick note on the headline number, because it flatters the picture badly. Western Digital''s reported net profit margin currently reads near 54%, but a large part of that is a one-time accounting gain on the SanDisk shares it still holds and is selling down, not the economics of actually selling drives. The real, still-impressive figure is a business earning gross margins around 50% at a cyclical high in pricing. Read the 54% as the crest of a wave, not the water line.
See why 37 investors see Western Digital as 7% overvalued.
Result: Fair Value of $329.76 (OVERVALUED)
Still, Western Digital’s story can change fast if rivals ramp capacity or if AI data center customers slow orders once current buildouts are filled.
Find out about the key risks to this Western Digital narrative.
Another View On Western Digital's Valuation
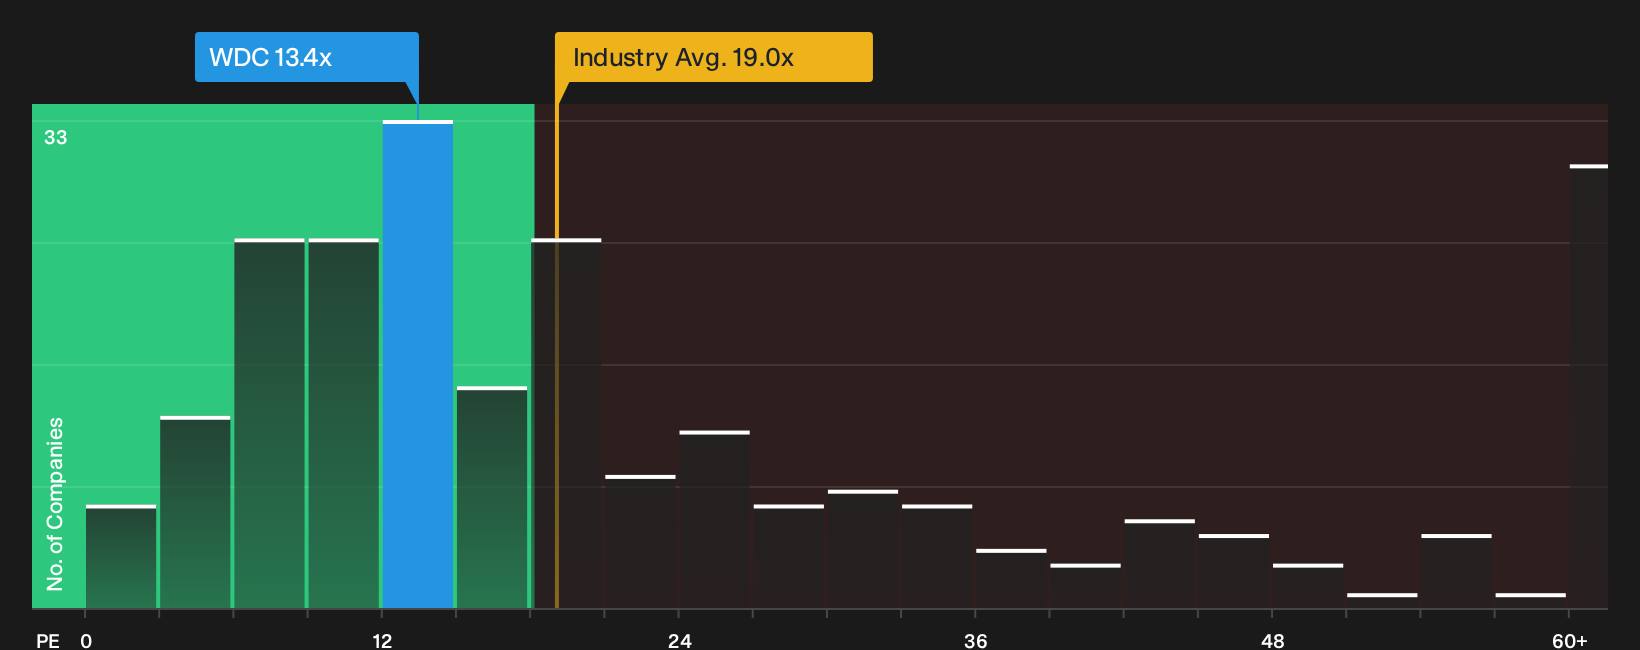
The user narrative tags Western Digital as 6.8% overvalued against a fair value of $329.76. A very different picture comes from multiples. WDC trades on a P/E of 14.2x, while the fair ratio is 46.2x and peers and the wider tech sector sit nearer 29.5x and 19x. That gap points to valuation risk if margins slide, but also room for sentiment to catch up if the earnings power holds. Which story do you think the market is really pricing in today?
See what the numbers say about this price, find out in our valuation breakdown.See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals in Western Digital's story so far. Act while the data is fresh and weigh the potential upside against the caution flags by checking the 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Western Digital?
If Western Digital has sharpened your focus, now is the moment to widen your watchlist before the next wave of opportunities moves without you.
- Target quality at a discount by scanning a curated set of 35 high quality undervalued stocks that pair solid fundamentals with prices that may not fully reflect them yet.
- Strengthen your income stream by reviewing 8 dividend fortresses that focus on higher yields backed by durable cash flows and payout histories.
- Sleep easier through market swings by assessing a 32 resilient stocks with low risk scores that emphasizes resilient balance sheets and more stable risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com