
Performance Food Group (PFGC) Could Be 22% Undervalued On Its Margin Improvement Narrative
Argus recently lifted its target for Performance Food Group (PFGC), highlighting the distributor’s focus on branded food and related products across foodservice, convenience, and specialty channels as a key part of its investment story.
Recent trading has been choppy for Performance Food Group, with the share price slipping 2.12% over the last day but still up 4.11% across the past month and 8.70% year to date. The 1 year total shareholder return is down 5.70%, compared with a much stronger 3 year total shareholder return of 73.92% and 5 year total shareholder return of 111.89%. This points to longer term momentum still in place despite near term pressure.
Capitalize on the renewed focus around Performance Food Group by scanning a curated set of peers and potential alternatives in our 33 high quality undervalued stocks.Performance Food Group now trades well below the average analyst target after a mixed year on the chart. Is that discount signaling opportunity, or is the market simply pricing in justified caution on the business?
Most Popular Narrative: 22% Undervalued
On the most followed view, Performance Food Group screens as undervalued, with a fair value of $123.23 against a last close of $95.71, which puts the current discount front and center in the story.
The main execution priority is that Performance Food Group converts procurement synergies, private brands, and AI and automation projects into sustained EBITDA margin uplift while managing integration costs, fuel volatility, and pressure in the Specialty segment.
Rollout of AI and automation tools across routing, inventory, warehouse safety, and sales, which management expects to contribute about 50 to 60 basis points of EBITDA margin uplift over three years, offers an efficiency catalyst that could support higher operating profit without relying on stronger pricing.
See why 3 investors see Performance Food Group as 22% undervalued.
Result: Fair Value of $123.23 (UNDERVALUED)
Still, the Performance Food Group story depends on Convenience stabilising and Cheney Brothers integration costs easing. Both factors could undercut margins if they remain more stubborn than expected.
Find out about the key risks to this Performance Food Group narrative.
Another View On Performance Food Group’s Valuation
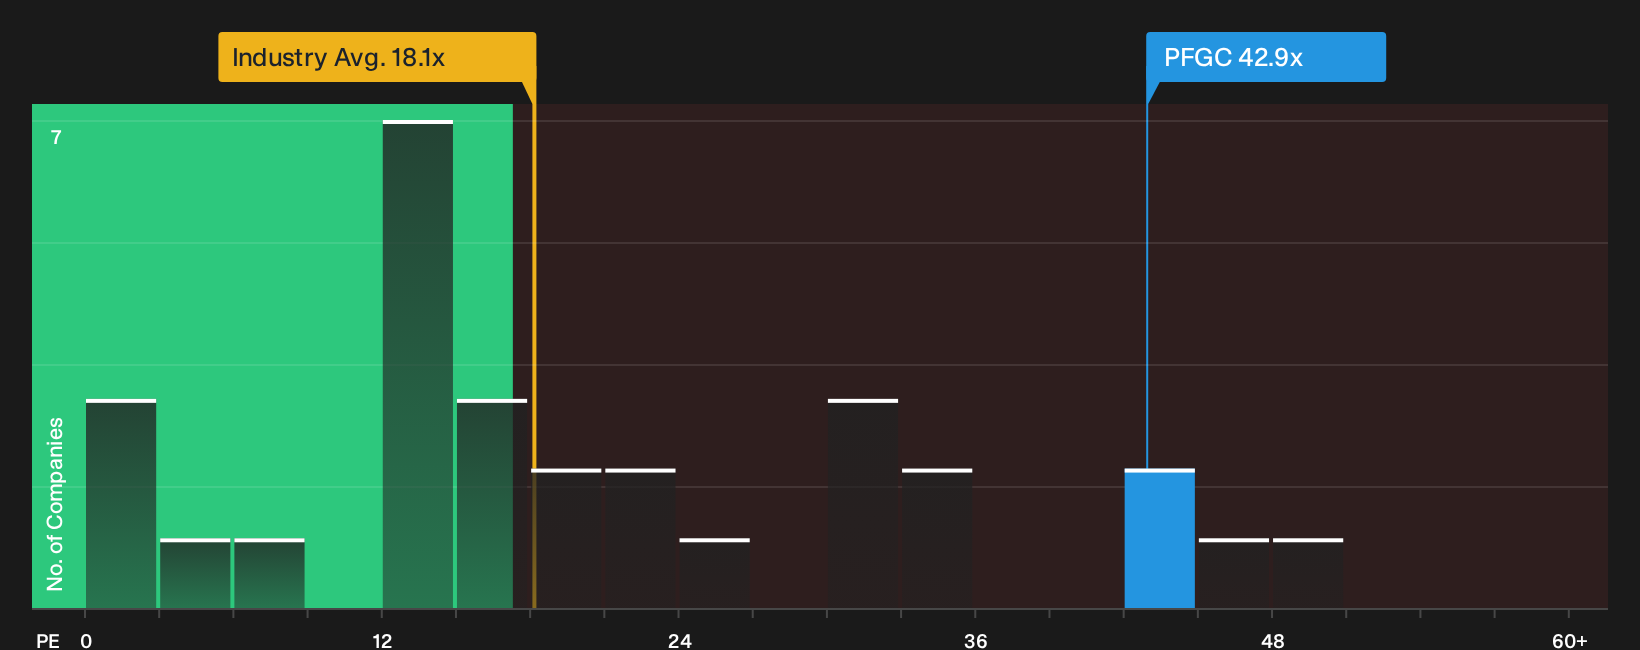
The fair value work around Performance Food Group leans on future earnings and cash generation. A different lens is the current P/E. At 42.9x, the shares trade well above the US Consumer Retailing sector at 18.1x and above a fair ratio of 31.2x. That gap points to valuation risk rather than a clear margin of safety. How comfortable are you paying a premium multiple for this story?
To see how this pricing stacks up against detailed earnings and peer data, take a closer look at our valuation breakdown, including the role of that higher P/E and the fair ratio benchmark, in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on valuation and margins can feel messy, so move quickly, review the full data, and weigh 3 key rewards and 1 important warning sign.
Looking for more Performance Food Group investment ideas?
Do not stop with Performance Food Group. Broaden your watchlist using focused screens that surface different types of opportunities other investors may be overlooking today.
- Target resilient cash generators by running a list of solid balance sheet and fundamentals (25 results) that can help you stress test potential holdings before they ever hit your portfolio.
- Hunt for mispriced quality and let the 33 high quality undervalued stocks point you toward companies where fundamentals and current pricing appear out of sync.
- Spot early-stage potential by scanning the 14 elite penny stocks with strong financials and checking which smaller businesses already show the financial traits you care about most.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com