
How Cost Cuts Will Impact Oerlikon Stock Investors
- OC Oerlikon has attracted renewed attention as restructuring and cost reduction efforts are highlighted alongside DCF analysis indicating that current pricing may not fully reflect projected cash generation.
- The key tension for investors now lies between OC Oerlikon’s planned margin improvement from cost measures and the risk that cyclical industrial demand or execution challenges could limit the cash flows implied by that valuation work.
- This review will examine how OC Oerlikon's investment narrative could shift as restructuring progress and cost savings move into sharper investor focus.
Scan how OC Oerlikon compares with other industrial restructurings by reviewing the hand picked 196 high quality undervalued stocks that may not fully reflect their projected cash generation yet.
OC Oerlikon Investment Narrative Recap
To own OC Oerlikon, you need to be comfortable with a story built around restructuring, cost cuts and a tighter focus on surface solutions, rather than broad industrial diversification. The recent 171.3% share price move sharpens attention on whether margin uplift and cash conversion from these measures actually come through, since expectations around the business are now far more demanding.
The near term swing factor is execution on cost savings as the group leans into a pure play model while managing early cyclical end markets like automotive and general industry. The main risk remains that softer industrial orders, product mix pressure and currency effects blunt margin progress, which would make the operational turnaround look less convincing.
Given the lack of fresh corporate announcements tied directly to this rerating, the most relevant reference point is still the planned Barmag divestment that underpins OC Oerlikon's shift toward a more focused surface solutions profile. That move concentrates exposure on coatings, advanced manufacturing and related services where management is pushing for higher returns on capital and a cleaner operating structure.
This cleaner footprint can sharpen the catalyst path for investors, because it makes cost out progress, order trends and R&D payback easier to track against the DCF case that currently suggests upside to the CHF7.16 intrinsic value estimate. It also raises the stakes on cyclical swings, customer concentration and any setbacks in the product pipeline, since there is now less diversification to cushion weaker segments.
OC Oerlikon's current analyst storyline links a projected CHF2.0b revenue base and CHF106.9m in earnings by 2029 to annual top line growth of 7.7%, which would mean an earnings increase of about CHF78.9m from CHF28.0m today.
Uncover why OC Oerlikon's fair value indicates a 3% potential downside to its current price, leaving little room for error.
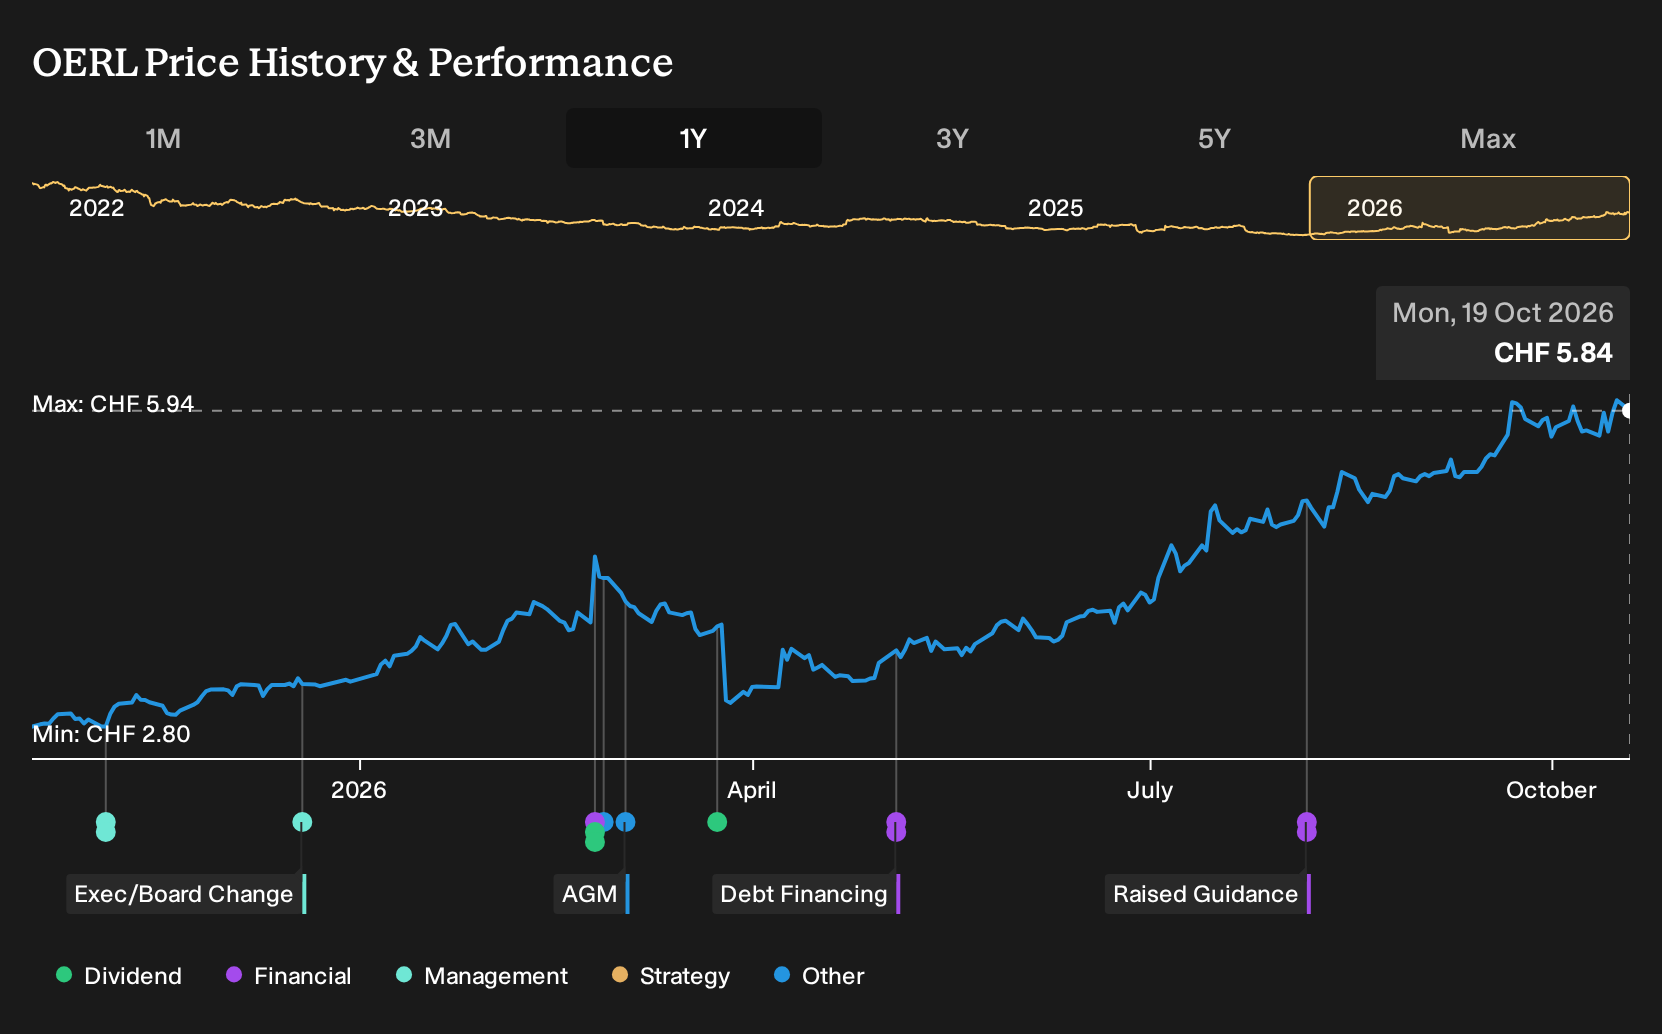
Exploring Other Perspectives
One alternative angle on OC Oerlikon is that aviation and industrial gas turbine demand might cool, which would leave the more cautious analysts closer to right. They were working off CHF1.9b of 2029 revenue and CHF93.8m of earnings before this latest news. That is a much tougher, more pessimistic path than consensus, and it could shift again as fresh information lands. Readers can weigh these different stories and decide which feels more realistic.
Explore 3 other OC Oerlikon fair value estimates, including one that suggests as much as 19% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your OC Oerlikon research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for OC Oerlikon. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate OC Oerlikon's overall financial health at a glance.
Looking for more OC Oerlikon style investment ideas?
If you want to stress test the OC Oerlikon story against other opportunities, broaden your watchlist using the Simply Wall St Screener and compare how different businesses stack up on value, quality and resilience.
- For investors who care most about quality at a sensible price, scan a curated 196 high quality undervalued stocks that pair solid fundamentals with discounted valuations.
- If balance sheet strength gives you peace of mind, focus on companies from the list of solid balance sheet and fundamentals (203 results) and see which ones match your risk tolerance.
- When you want to go beyond the usual tickers and find fresher stories, filter through the 613 high quality undiscovered gems that combine robust financials with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com