
Is Butterfly Network (BFLY) Undervalued On New Alliances Or Already Priced For Growth?
Butterfly Network (BFLY) has been drawing fresh attention after two recent alliances that extend its ultrasound technology into medical education and brain interface research, giving investors new angles to assess the stock.
The recent alliances arrive after a sharp reset in sentiment, with Butterfly Network’s 7 day share price return down 12.63% and its 30 day share price return down 5.20%, even as the 90 day share price return of 9.53% and year to date share price return of 99.20% sit alongside a very large 3 year total shareholder return of more than eight times.
Spot opportunities beyond Butterfly Network by scanning a curated set of 33 healthcare AI stocks that also blend medical technology with AI driven use cases.Butterfly Network has just ridden a steep year to date surge while short term returns have cooled. Is this a moment to accept today’s price, or to wait for a cleaner valuation setup in the next section?
Most Popular Narrative: 34% Undervalued
Analysts following Butterfly Network see a fair value of $11.40 per share versus the recent $7.47 close. This frames the stock as materially below their long term scenario and puts extra weight on how its ultrasound and chip licensing plans play out.
Butterfly's pipeline of large enterprise and medical school deals, bolstered by recent success in landing a top global health system for full deployment, points to accelerating penetration of handheld ultrasound solutions as healthcare systems shift toward more accessible, cost-effective, point-of-care diagnostics supporting forward-looking revenue growth as funding clarity returns.
See why 37 investors see Butterfly Network as 34% undervalued.
Result: Fair Value of $11.40 (UNDERVALUED)
Still, the bullish Butterfly Network story depends on closing large enterprise and medical school deals, as well as managing high R&D spending that could extend losses.
Find out about the key risks to this Butterfly Network narrative.
Another View: Butterfly Network And Rich Sales Multiples
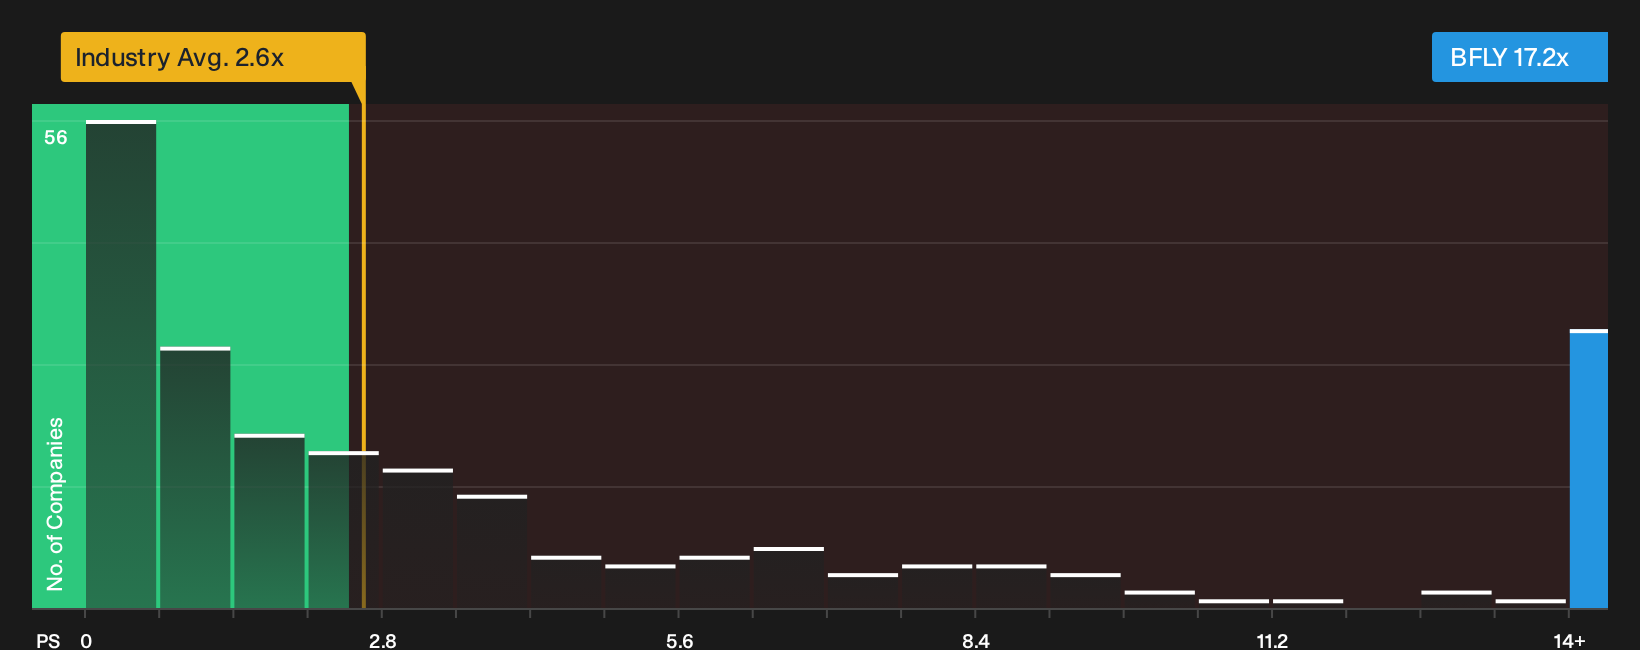
The fair value story built on analyst targets bumps into a very different message from the market’s own pricing of Butterfly Network. On a P/S ratio of 17.2x, the stock trades far above the estimated fair ratio of 4.1x, the US Medical Equipment industry at 2.6x, and peers at 4.9x. That kind of gap concentrates a lot of expectation into each dollar of future revenue. How comfortable are you with paying that premium for an unprofitable business that still needs to prove its long term earnings power?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The split tone in this Butterfly Network analysis, with rich upside narratives alongside pointed valuation concerns, only matters if you weigh the evidence yourself and act before sentiment moves again. To see both sides set out clearly, review the 1 key reward and 3 important warning signs
Looking For More Investment Ideas Beyond Butterfly Network?
If Butterfly Network has sharpened your thinking, do not stop here. Broader context across different styles of opportunities can change how this stock looks in your portfolio.
Scan undervalued potential by sizing up companies that screen well on price and quality through 33 high quality undervalued stocks.
Seek dependable income by checking out companies with robust payouts and balance sheets using 8 dividend fortresses.
Prioritise resilience by reviewing a curated 32 resilient stocks with low risk scores that aims to limit downside while still giving you room to participate in upside moves.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com