
AbbVie (ABBV) Posts Fresh Trial Wins, Is The Stock Fully Valued?
AbbVie (ABBV) just put fresh clinical data at center stage. New Phase 2a results for its investigational Crohn’s therapy ABBV-466 and twin FDA Breakthrough Therapy tags for Temab-A are reshaping the story.
These trial readouts are landing while AbbVie’s share price has climbed to US$285.42, with a 30 day share price return of 8.13% and a year to date share price return of 24.47% as investors weigh the Crohn’s and oncology updates alongside a longer run total shareholder return of 26.68% over one year and more than 3x over five years. Together, these figures indicate that momentum has been building around the pipeline story rather than fading.
Scan AbbVie’s momentum in immunology and oncology against a curated group of peers by jumping to the 33 healthcare AI stocks that are also focusing on data-driven drug development.
Bulls point to AbbVie’s Crohn’s and oncology data as support for a richer multiple, while bears see a hot US$285 stock priced for perfection. Which side do the current valuation markers lean toward?
Most Popular Narrative: 2% Overvalued
AbbVie closed at $285.42, a touch above the most followed fair value estimate of $278.61 that is built on detailed growth and margin assumptions. The current price leans slightly richer than that framework implies while still treating pipeline execution as the main swing factor.
The key requirement for AbbVie is successfully executing on its pipeline and business development so that new immunology, oncology and neuroscience drugs replace revenue from declining products such as Humira and Imbruvica.
The current view that AbbVie is fairly valued and bullish indicates that the share price already reflects expectations for sustained growth from ex Humira platforms, rising R&D investment and extended earnings delivery into the 2030s and 2040s.
See why 333 investors see AbbVie as 2% overvalued.
Result: Fair Value of $278.61 (OVERVALUED)
Still, any stumble in replacing Humira and Imbruvica revenue, or intensifying drug pricing pressure, could quickly challenge the AbbVie fair value narrative that investors are leaning on.
Find out about the key risks to this AbbVie narrative.
Another View: AbbVie Through A Cash Flow Lens
The earlier fair value of $278.61 leans on analyst assumptions and earnings multiples. A different tool, the SWS DCF model, values AbbVie at $506.53 per share based on projected future cash flows, which implies the current $285.42 price screens as materially undervalued. Which set of assumptions do you find more realistic for the long haul?
To see how that cash flow based estimate is built and what would need to change for the gap to close, Look into how the SWS DCF model arrives at its fair value.
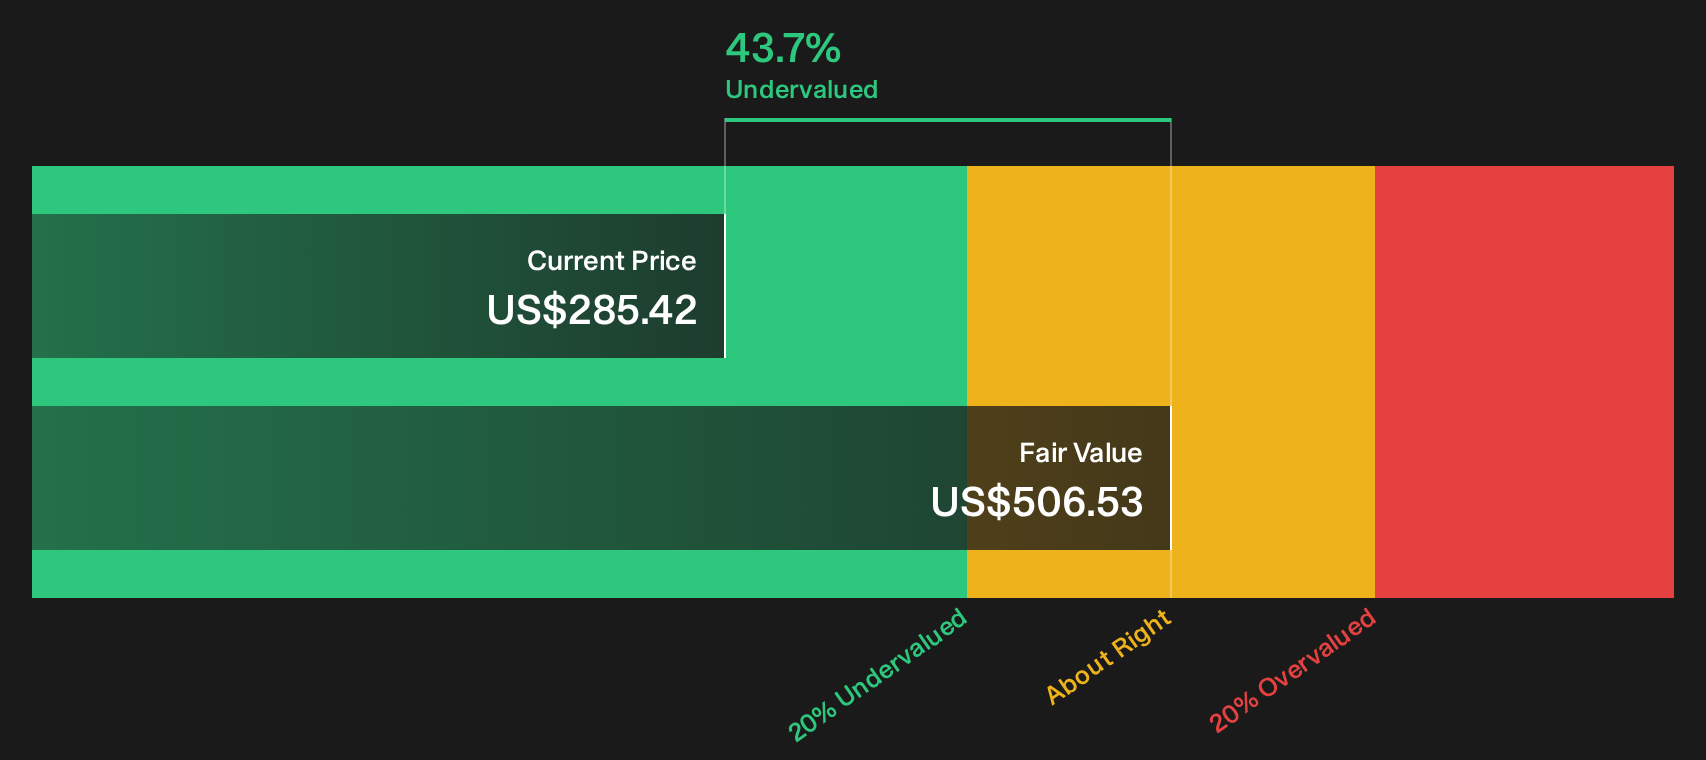
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out AbbVie for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the data or a clear tilt in AbbVie sentiment. Either way, move quickly, review the key metrics in detail, and stress test both sides of the story by weighing 3 key rewards and 4 important warning signs.
Looking for more ideas beyond AbbVie?
If you stop with AbbVie, you only see one angle. Broaden your watchlist with other potential opportunities that match your risk, income, and quality preferences.
- Target potential mispricing by scanning a curated set of companies that currently appear attractively valued using the 33 high quality undervalued stocks.
- Lock in income potential by reviewing a focused group of high yield candidates screened as 8 dividend fortresses.
- Dial down portfolio stress by searching through a hand picked pool of 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com