
What Acadia Healthcare Stock Momentum Means For Shareholders
- Acadia Healthcare Company has recently attracted fresh attention as investors focus on its facility expansion program, specialty treatment footprint, and operational tweaks rather than any single new announcement.
- The interesting angle is how early use of AI in billing and revenue cycle work is being weighed against legal, Medicaid, and underperforming facility pressures.
- Next, the focus shifts to how this renewed interest, shaped by AI-driven operations, could influence Acadia Healthcare's broader investment narrative.
Acadia Healthcare Company Investment Narrative Recap
To own Acadia Healthcare Company, you need to be comfortable with a story built around expanding behavioral health capacity, improving operations at existing facilities, and squeezing more cash from each admission through tighter cost and revenue cycle management. The recent share price move, coming without fresh company news, does not materially change that underlying thesis.
The near term swing factor still sits in execution on facility ramp up and AI supported billing, especially as interest costs and start up losses weigh on results. The biggest risk remains pressure on Medicaid reimbursement and supplemental programs, which, paired with legal expenses and underperforming facilities, could limit any operational progress.
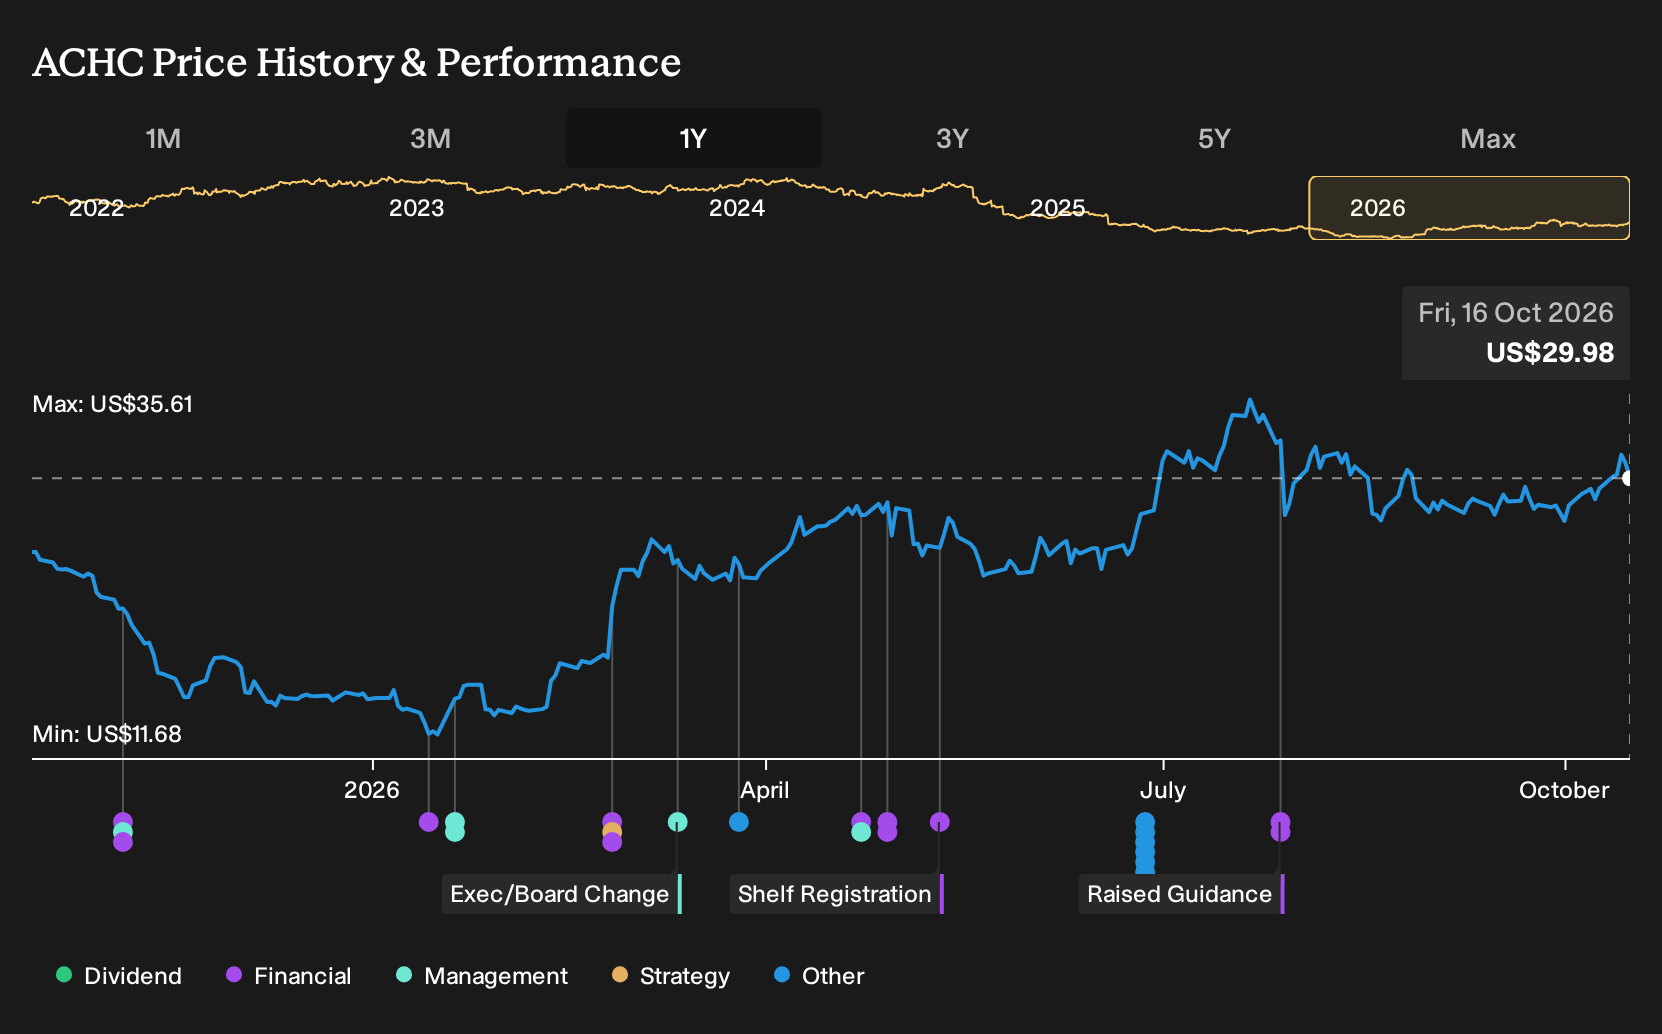
The most relevant data point around this move is that Acadia Healthcare Company is being discussed as roughly 11% undervalued based on a fair value estimate of US$33.79 versus a recent price near US$29.98. That gap is being framed around facility development, specialty care expansion, and technology enabled operations rather than a single headline.
In practical terms, investors are weighing a stock that has climbed about 110% year to date. At the same time, it trades on a P/S of 0.8x compared with higher sector averages, while facing clear execution and reimbursement risks. For anyone tracking catalysts, the key question is whether operational adjustments and AI driven revenue cycle work can offset Medicaid exposure, legal costs, and the drag from weaker sites.
Acadia Healthcare Company's current analyst script points to revenues of US$4.0b and earnings of US$229.5m by 2029, built on assumed top line growth of 5.9% a year and an earnings swing of roughly US$1.3b from a loss of US$1.1b today to that projected profit level.
Uncover why Acadia Healthcare Company's fair value indicates a 13% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle you might explore is liability and payer costs. The most optimistic analysts before this sector driven move were assuming revenue could reach about US$4.1b and earnings about US$402.9m by 2029. That view leans on Acadia Healthcare Company containing legal and reimbursement expenses more tightly than the baseline story assumes, which this latest price action may challenge or reinforce.
Explore 3 other Acadia Healthcare Company fair value estimates, including one that suggests up to 400% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Acadia Healthcare Company research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Acadia Healthcare Company. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Acadia Healthcare Company's overall financial health at a glance.
Looking for more investment ideas beyond Acadia Healthcare Company?
If the Acadia Healthcare Company story has sharpened your thinking on risk, valuation, and execution, use that same lens to scan a wider watchlist. The Simply Wall St Screener can help you quickly narrow the field to businesses that better match your return goals and comfort level with volatility.
- For investors who want potential upside paired with reasonable quality checks, start with a focused group of 20 high quality undiscovered gems that the broader market may be overlooking.
- If capital preservation and a smoother ride matter to you, filter for 32 resilient stocks with low risk scores that score well on resilience and financial stability.
- Income focused investors can target reliable cash distributions by screening for 8 dividend fortresses that aim to combine robust payouts with underlying strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com