
What Is Drawing Attention To ConnectOne Bancorp (CNOB)?
ConnectOne Bancorp (CNOB) has drawn fresh attention after recent share performance data showed a mixed picture, with gains year to date but declines over the past month and past 3 months. That split sets the stage for a closer look at the bank’s fundamentals.
That pattern fits a broader trend for ConnectOne Bancorp, where the year to date share price return of 16.54% contrasts with a 30 day share price decline of 3.64%. Long term investors have seen a 3 year total shareholder return of 100.15%, which points to strong past market confidence in the story despite the recent loss of momentum.
Compare ConnectOne Bancorp’s mixed recent returns with other banks by scanning our hand picked list of solid balance sheet and fundamentals (25 results), which may be better aligned with your risk tolerance and time horizon.
ConnectOne Bancorp has already rewarded long term holders, yet the recent pause in the share price raises a sharper issue. Is most of the easy upside already behind it, or does valuation still leave meaningful room ahead?
Most Popular Narrative: 17% Undervalued
ConnectOne Bancorp’s most followed narrative pins fair value at $36.75 per share, above the recent $30.44 close. This puts the current price at a clear discount and turns attention to what might close that gap.
ConnectOne Bancorp is working through a large pipeline of adjustable rate and fixed loans that are repricing at higher yields, with about US$700m already repriced in 2026 at an average 255 basis point increase and similar volumes expected ahead. This can keep supporting net interest margin and earnings power as more of the book resets.
See why 8 investors see ConnectOne Bancorp as 17% undervalued.
Result: Fair Value of $36.75 (UNDERVALUED)
Still, the ConnectOne Bancorp narrative hinges on two pressure points: rent stabilized multifamily credit issues and rising deposit costs in its New York and New Jersey footprint.
Find out about the key risks to this ConnectOne Bancorp narrative.
Another View On ConnectOne Bancorp’s Value
The first story around ConnectOne Bancorp leans on analyst targets and earnings power. A different lens tells something less comfortable. Simply Wall St’s DCF model estimates future cash flows at $24.28 per share, which sits below the current $30.44 price and points to an overvalued outcome instead.
That gap suggests investors are already paying above this cash flow based estimate and that upside relies on stronger execution than the model assumes. The key question is which lens you trust more when the narratives disagree so clearly.
Look into how the SWS DCF model arrives at its fair value.
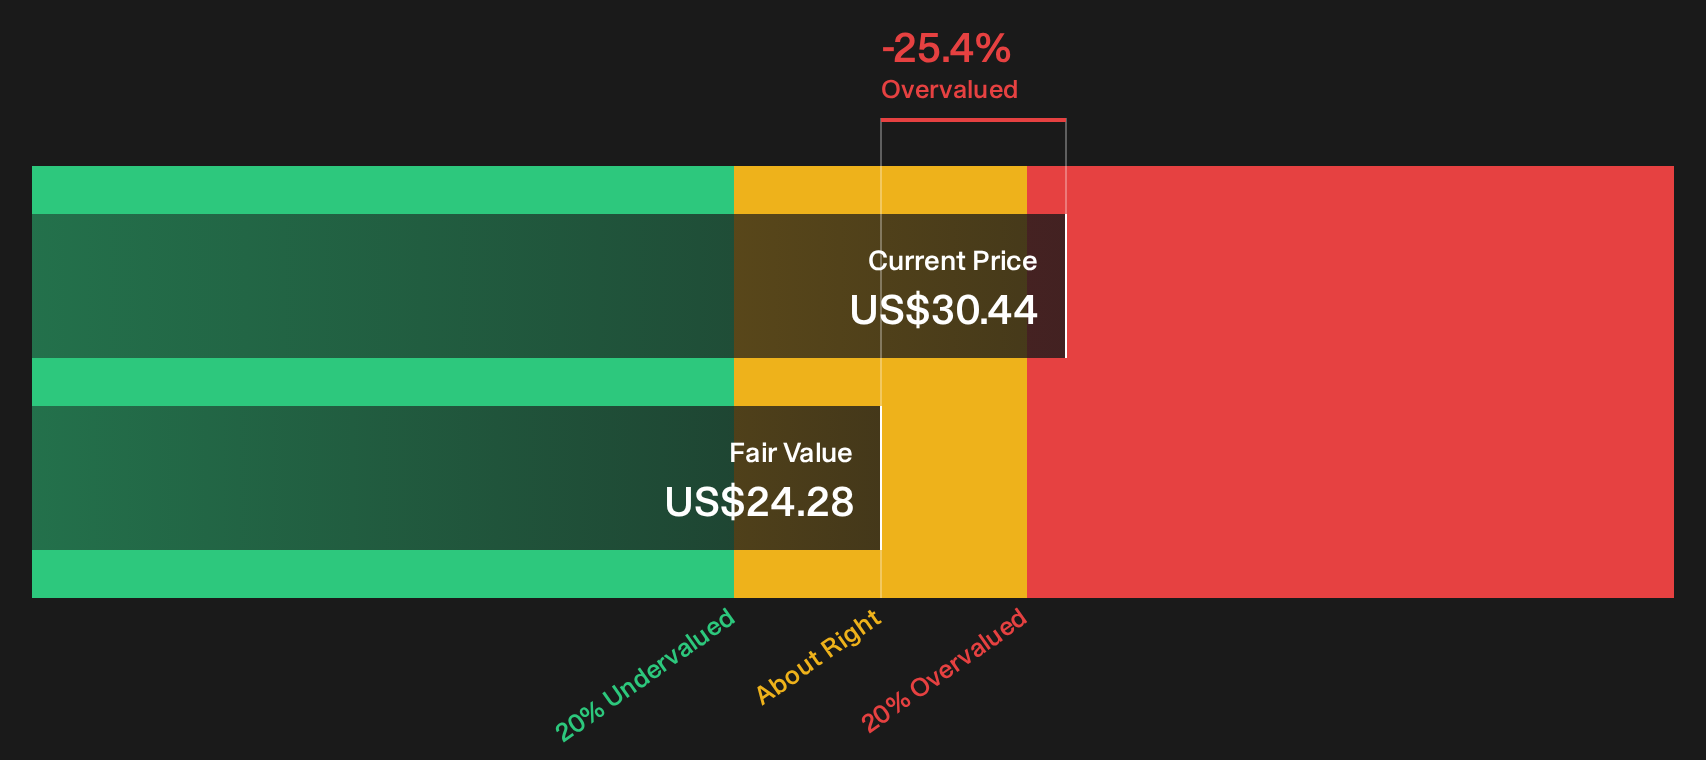
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ConnectOne Bancorp for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or real opportunity: either way, you are better off testing the assumptions yourself and seeing what holds up. Take a closer look at the optimism already priced into ConnectOne Bancorp by reviewing the 6 key rewards.
Looking for more investment ideas beyond ConnectOne Bancorp?
If the mixed signals around ConnectOne Bancorp have sharpened your focus, use that momentum. Let the screener guide you toward fresh ideas that fit your style.
- Target resilient income by focusing on companies that show consistent payouts with the help of 8 dividend fortresses.
- Hunt for quality at a discount by scanning businesses that pair solid fundamentals with appealing prices through 20 high quality undiscovered gems.
- Prioritize capital preservation by zeroing in on companies that score well on stability using the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com