
Bond Conversion Could Be A Big Deal For Elis Shares (ENXTPA:ELIS)
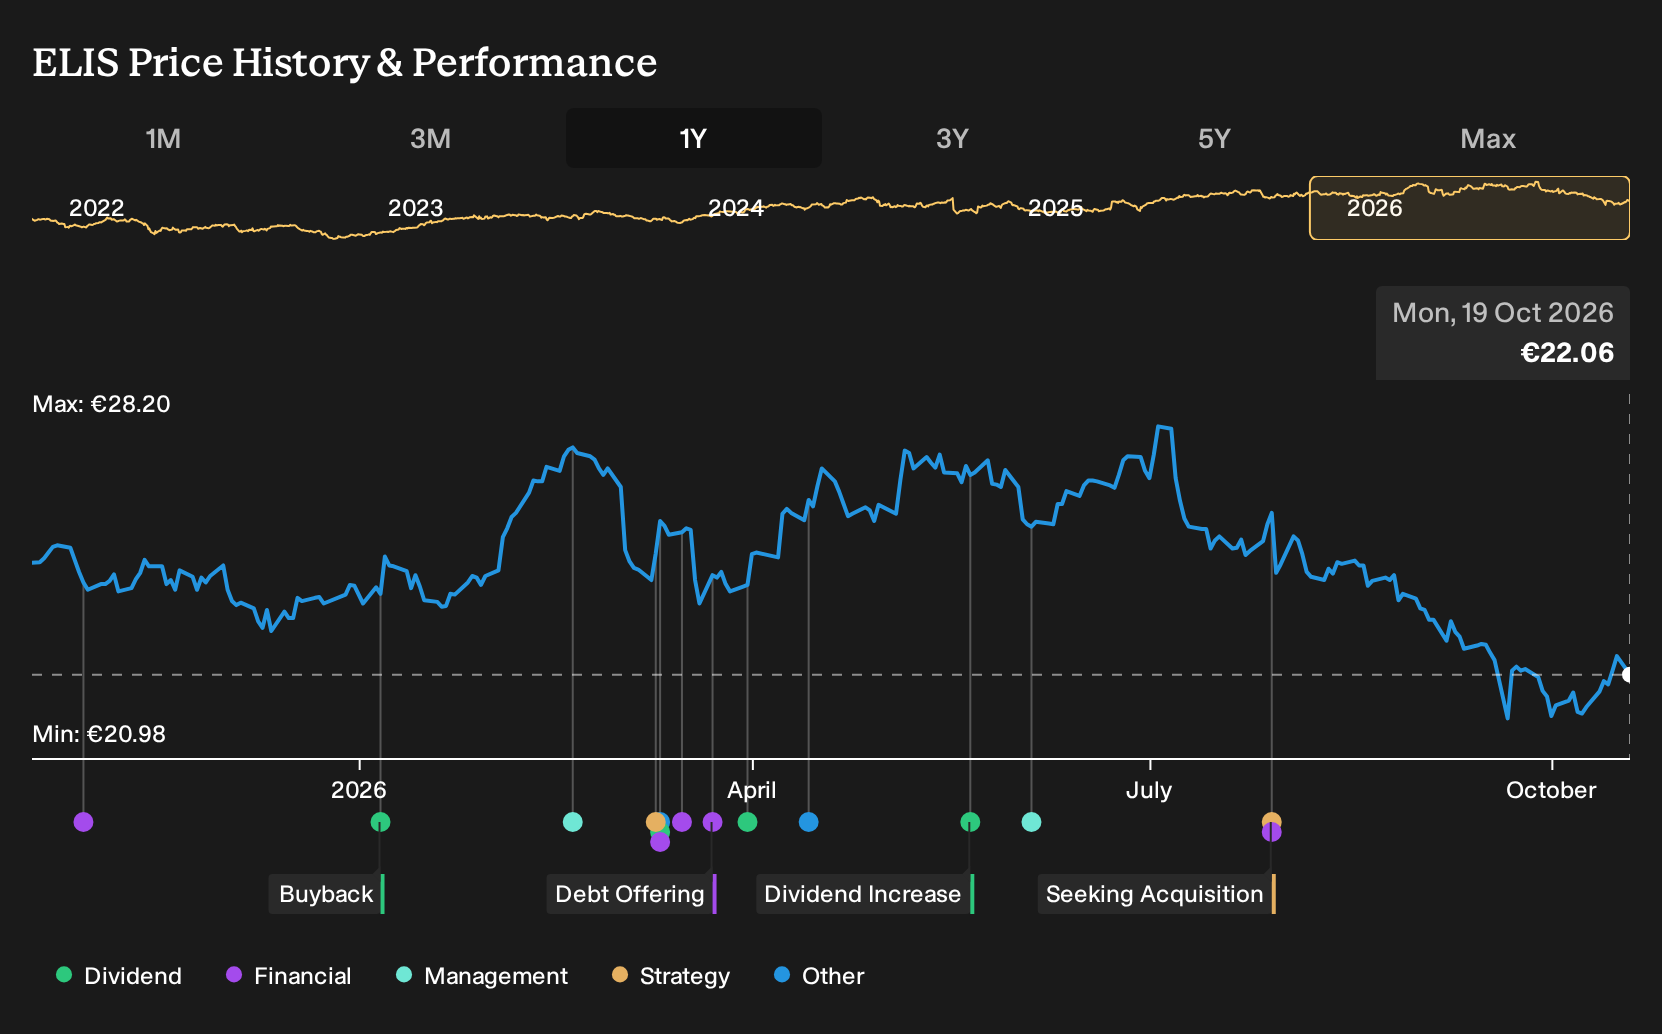
- Elis recently completed a major balance sheet reshuffle, as almost all of its 2029 OCEANE bonds were converted into equity. This lifted the share count by close to 10% and reduced future interest obligations.
- This shift changes how Elis distributes future cash flows between debt and equity holders. As a result, the relationship between operating performance, capital intensity, and shareholder returns becomes much more important to understand.
- The focus now turns to how Elis' investment narrative holds up in light of this large OCEANE conversion into equity.
Scan how Elis stacks up on balance-sheet quality and capital efficiency, then compare it with other hand-picked companies in our list of solid balance sheet and fundamentals (203 results).
Elis Investment Narrative Recap
To own Elis, you need to be comfortable with a capital intensive, service heavy model that leans on recurring contracts in sectors like hospitality, healthcare and workwear. The investment case hinges on steady outsourcing demand, tight cost control and disciplined capital spending. The recent OCEANE conversion does not alter that operational thesis, but it does shift more of the economic upside and downside onto equity holders.
In the near term, the key swing factor is how Elis manages margin pressure in places like Latin America while keeping volumes and pricing intact across Europe. The biggest operational risk remains a combination of wage inflation, FX headwinds and any slowdown in hospitality activity. Those pressures could squeeze net margins and make heavy linen and plant CapEx feel more burdensome if conditions soften.
The recent conversion of almost all 2029 OCEANE bonds into equity is the announcement that matters most here. Elis now carries more shares but less interest bearing debt. That change increases the sensitivity of each share to outcomes in cash generation, return on capital and future investment choices. It also simplifies the capital structure, which makes it easier to judge how much of the firm value ultimately belongs to shareholders.
This move interacts directly with the current catalysts and risks. Lower interest outflows give Elis more room to absorb wage inflation, FX pressure or cyclical softness in hospitality without stressing coverage ratios. At the same time, higher share count means any disappointment on operating margins, CapEx discipline or organic growth is felt more sharply on a per share basis. Execution on productivity programs, outsourcing wins and disciplined capital allocation now matters even more for equity holders.
Elis' current analyst narrative points to revenues of €5.4b and earnings of €445.4m by 2029, compared with earnings today of €366.6m. That path implies 4.3% yearly revenue growth and an earnings increase of about €78.8m from current levels.
Uncover why Elis' fair value indicates a 33% potential upside to its current price, which could narrow quickly if sentiment shifts.
Exploring Other Perspectives
Simply Wall St Community members offer just 2 fair value views on Elis, spanning roughly €29.45 to about €37.70 per share, so even a tiny sample already shows how far opinions can stretch. When you factor in the recent OCEANE conversion, ongoing Latin America margin pressure, FX swings and hospitality exposure, you get plenty of room for sharply different narratives. If you want a fuller picture, explore more of these contrasting community estimates before considering how Elis fits into your own portfolio logic.
Explore another Elis fair value estimate, including one that suggests it could be worth just €29.45!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Elis research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Elis. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Elis' overall financial health at a glance.
Looking For More Investment Ideas Beyond Elis?
Once you understand where Elis fits in your portfolio, it helps to line it up against other opportunities that score well on balance sheet strength, quality and resilience. The Simply Wall St Screener lets you filter for exactly the kind of businesses you want to research next, so you can build a watchlist that matches your own risk tolerance and income goals.
- If capital preservation is a top priority, start with companies that combine sturdy finances and lower risk profiles through our 231 resilient stocks with low risk scores.
- For investors who care most about paying a fair price for strong fundamentals, look through a curated pool of attractively priced quality stocks in the 196 high quality undervalued stocks.
- Income focused readers can zero in on businesses offering higher yields with robust payout support by scanning the 217 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com