
Is Nine Dragons Paper (Holdings) (SEHK:2689) Undervalued After Dividend Concerns And Cash Flow Questions?
Recent commentary on Nine Dragons Paper (Holdings) (SEHK:2689) zeroes in on one issue. Investors are weighing the risk around its dividend commitments, as negative free cash flow and questions over intrinsic value stay in focus.
Recent trading tells a mixed story for Nine Dragons Paper (Holdings). The share price is down about 18.6% over 30 days and roughly 30.3% over 90 days, even though the 3 year total shareholder return is up around 17.9% while the 5 year total shareholder return is down roughly 47.9%. This combination signals fading momentum in the near term as the market reassesses dividend risk and perceived valuation.
Compare Nine Dragons Paper (Holdings) with other dividend focused opportunities by scanning our curated list of 217 dividend fortresses before you commit fresh capital here.
Nine Dragons Paper now trades well below recent levels, with dividend worries and an intrinsic value gap still lingering. Is this the moment to step in, or does patience offer a safer entry point as valuation is examined next?
Preferred P/E of 5.6x for Nine Dragons Paper: Is it justified?
On simple earnings math, Nine Dragons Paper (Holdings) looks inexpensive. The shares closed at HK$5.05, while the stock is described as good value on a P/E of 5.6x against both its own fair P/E estimate and listed peers.
The P/E ratio compares what you pay per share with the earnings that each share generates. For a mature packaging and paper producer such as Nine Dragons Paper, this measure often frames how much confidence investors place in the durability of its profits and cash generation through the cycle.
Here the gap is wide. Nine Dragons Paper is assessed as good value on a P/E of 5.6x against an estimated fair P/E of 8.5x, and also trades below the Hong Kong market P/E of 10.6x. Trading below peer averages and the fair ratio points to a market that is pricing the business on a materially lower earnings multiple than the level models suggest it could move toward if sentiment and fundamentals align.
The discount is even more stark when set against the wider Asian Forestry industry, where the average P/E is 15.4x. That kind of spread implies investors are assigning a much heavier earnings discount to Nine Dragons Paper than they are to sector rivals, despite the stock being described as good value relative to both direct peers and the broader industry.
Explore the SWS fair ratio for Nine Dragons Paper (Holdings).
Result: Price-to-earnings of 5.6x (UNDERVALUED)
Still, dividend pressure and the reported intrinsic discount on Nine Dragons Paper could both unravel if cash generation or investor confidence weakens further.
Find out about the key risks to this Nine Dragons Paper (Holdings) narrative.
Another View on Nine Dragons Paper’s Value
The apparently cheap 5.6x P/E story for Nine Dragons Paper (Holdings) runs into friction once the SWS DCF model is brought in. On this view the shares at HK$5.05 sit above an estimated future cash flow value of HK$3.49, which frames the stock as overvalued rather than on sale. Which lens do you trust more when earnings and cash do not tell the same story?
Look into how the SWS DCF model arrives at its fair value.
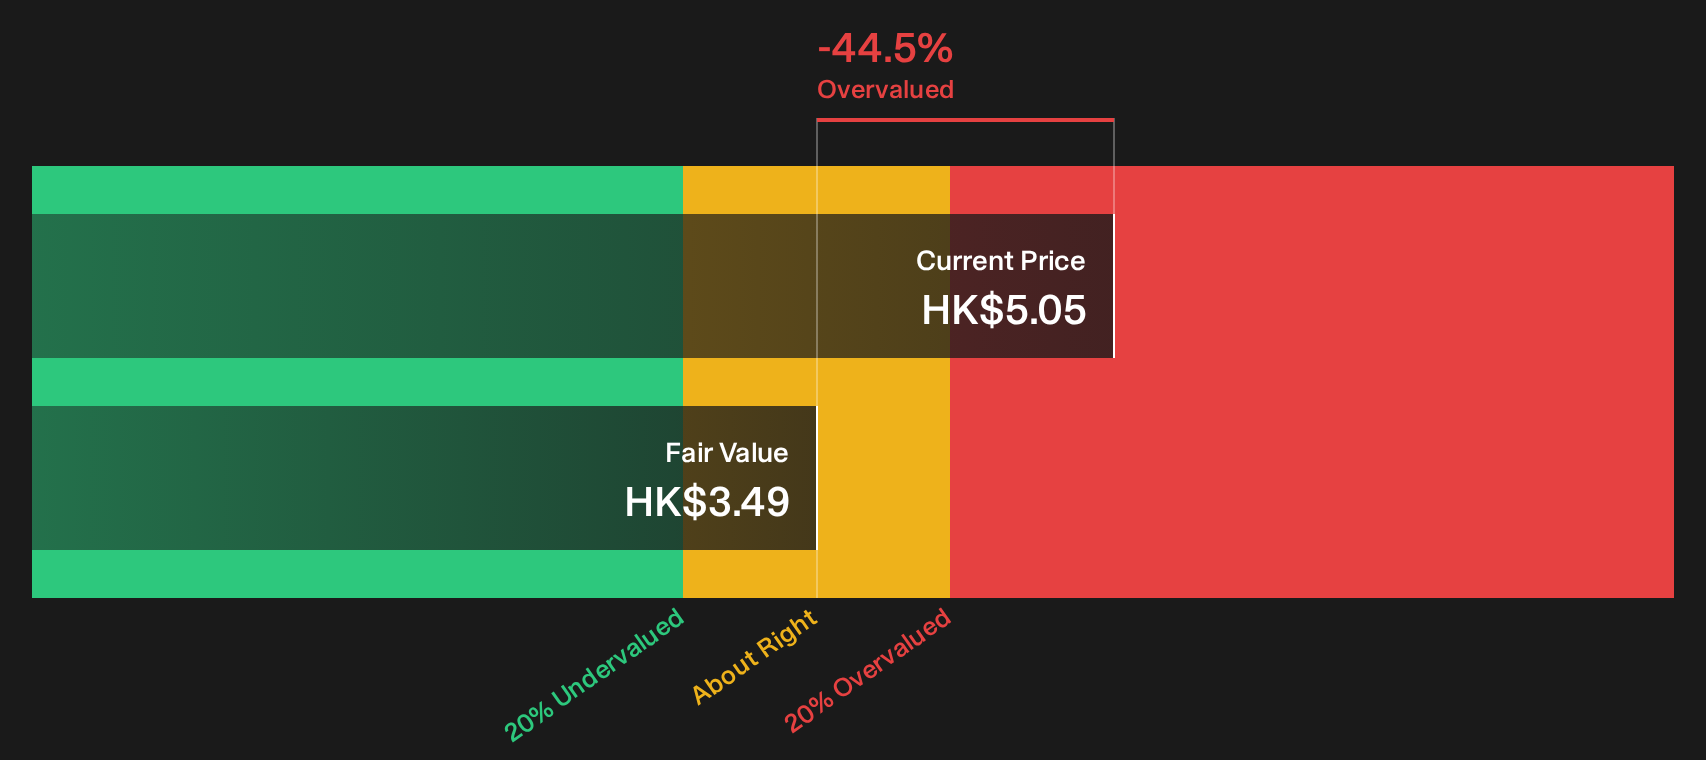
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Nine Dragons Paper (Holdings) for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Nine Dragons Paper can cut both ways, so move quickly, review the data for yourself, and weigh the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Nine Dragons Paper?
If Nine Dragons Paper (Holdings) has raised more questions than answers, you may want to broaden your watchlist with a few focused idea lists tailored to different goals.
- Target resilient balance sheets and steadier fundamentals by running your eye over the list of solid balance sheet and fundamentals (203 results). This could help anchor a portfolio.
- Hunt for quality on sale by checking the 195 high quality undervalued stocks, which combines strong business profiles with prices that screens flag as attractive.
- Seek out overlooked opportunities by scanning the 613 high quality undiscovered gems before others start paying attention and pricing them differently.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com