
Why Super Micro Computer Bears Were Right Before The Drop
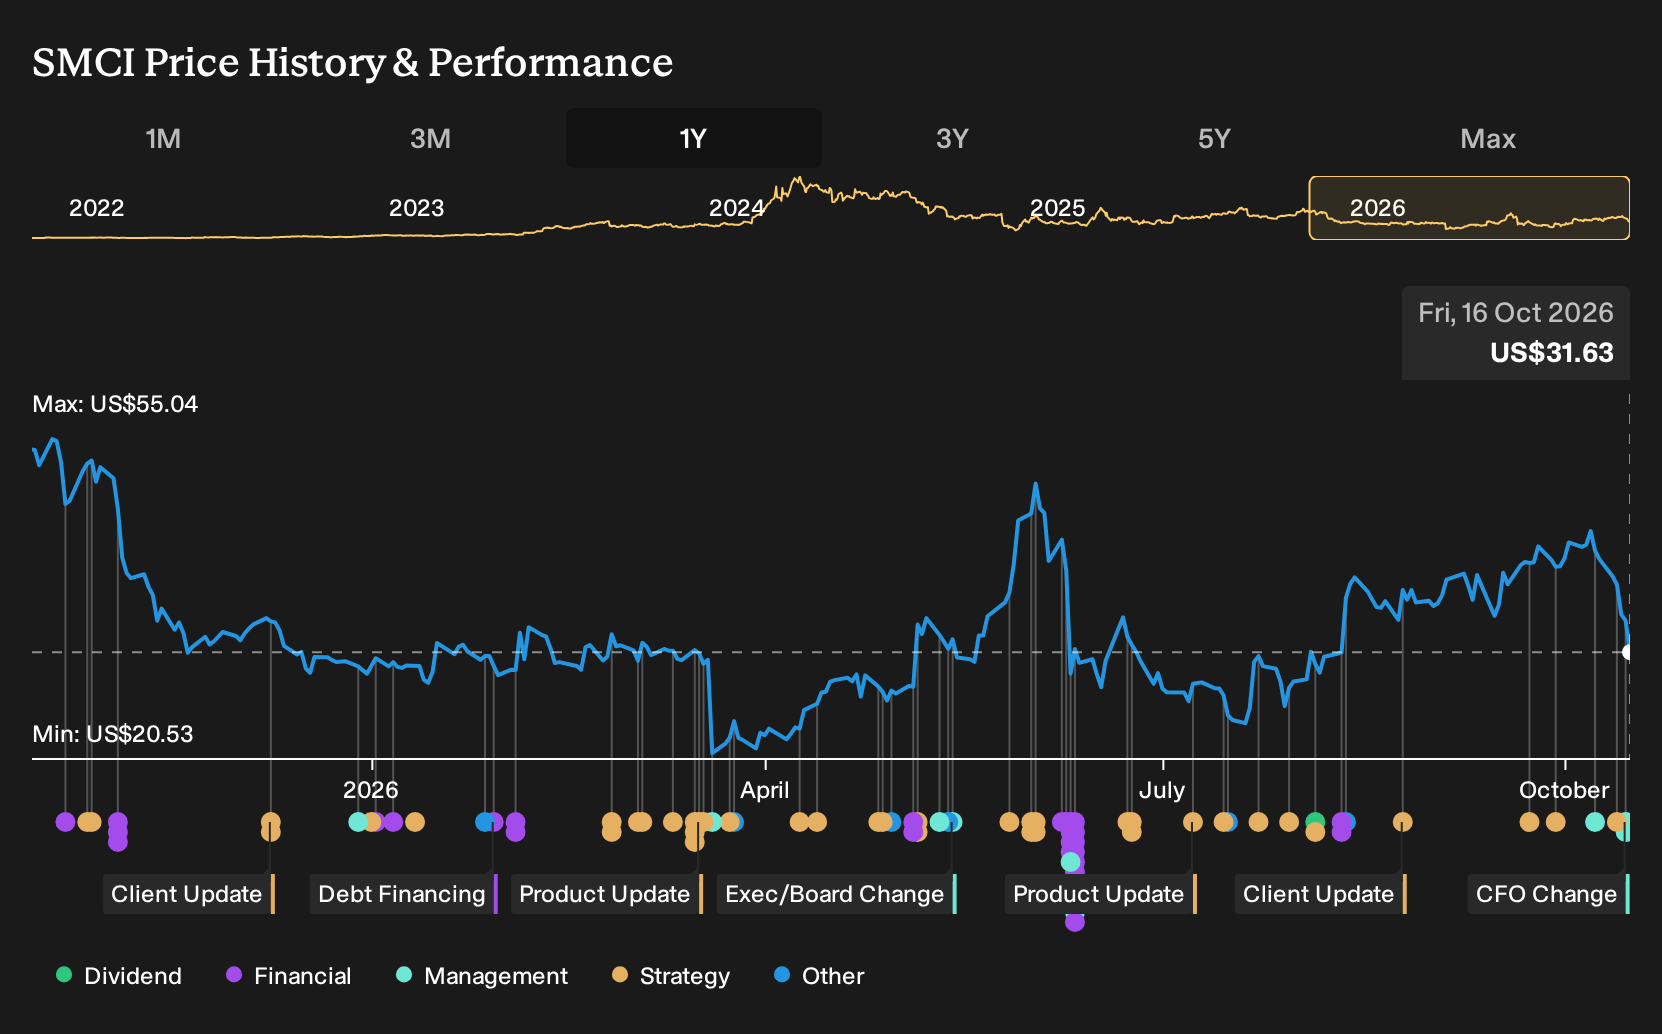
Investors who held Super Micro Computer over the past year are down 42.5%, including dividends. If you had backed the bullish February 2025 thesis that SMCI could dominate customized AI data center builds, you watched a very different story play out in your portfolio. The obvious question is not whether Super Micro Computer was a bad business but which specific assumptions on 50% revenue growth, 6.6% margins, liquid cooling uptake, and a 20x P/E failed to match reality.
Super Micro Computer has already moved. Pinpoint other ways to investigate the theme among 55 AI infrastructure stocks.
The Argument You Would Have Been Weighing Up On Super Micro Computer
The shares cost US$53.84 at the start of the period, so any thesis on Super Micro Computer had to answer whether that entry point compensated you for growth and execution risk.
The bullish February 2025 view saw fair value at US$74.53, a price implied by assumptions such as 50.0% revenue growth and 6.6% profit margins supported by direct liquid cooling adoption.
The more cautious August 2025 stance pointed to a US$50.06 fair value and focused on risks like heavy reliance on a few large customers and potential hardware commoditization.
What The Results Changed For The Super Micro Computer Thesis
Super Micro Computer reported Q4 2026 revenue of US$11.12b and net income of US$1.14b, with net margin at 10.3% versus 3.4% in Q4 2025. That margin outcome exceeded both the bullish 6.6% and the cautious 5.0% assumptions, although later news about export-control probes, class actions, and a large equity raise clearly supported the more cautious case on governance and balance sheet risk. Overall, the evidence cut both ways.
The key lesson is simple. When a story leans on margin expansion and capital intensity, keep checking reported net margin against the thesis line and track how management funds the order book, whether through operating cash, debt, or fresh equity.
What Super Micro Computer's Lower Price Is Asking You To Believe
Super Micro Computer trades at US$31.63 today, with the selected Narrative placing its Fair Value above that level based on expectations around AI infrastructure orders and mix.
The Narrative leans on higher margin data center solutions, broader customers, and tight cash and compliance execution, so a buyer now would need to believe those shifts can outweigh the share price fall.
"The main thing that has to go right is Super Micro Computer sustaining its shift toward higher-margin integrated data center building block solutions, software, services, and a more diversified mix of enterprise and channel customers while managing working capital, compliance, and legal risks."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Go Straight To The Source
This company's disappointment is already part of the story. Your next idea could come from looking where the price and the possibilities still seem far apart. Here are three companies priced below our estimates.
- Company 1 - 41% below our estimate - uses heavier AI, digital, branch and payments investment to pursue higher fee income diversification.
- Company 2 - 48% below our estimate - scales large LED display projects and services while working to improve margins and returns.
- Company 3 - 33% below our estimate - converts a sizable AI infrastructure contract backlog into paid multicloud database and software usage.
Those are three of them. See every one of the 33 undervalued companies on it →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com