
Blackbaud (BLKB) Rebounds Sharply, Is The Stock Cheap Or Fairly Valued?
Blackbaud (BLKB) has attracted fresh attention after its share price reset over recent years. This has left the stock trading on a P/E ratio below many software peers and raised renewed questions about whether the current valuation fully reflects its earnings base.
Recent trading tells a mixed story. The share price has climbed strongly in the short term, with a 90 day share price return of 63.8%. However, longer term total shareholder returns remain weak, with a 5 year total shareholder return that has declined 29.0% as the market has reassessed Blackbaud against its earnings and current P/E discount to software peers.
Compare Blackbaud's reset valuation with a curated 33 high quality undervalued stocks that the market may be pricing at similar discounts to their earnings power.
Blackbaud runs a focused, recurring software and payments business, yet its share price only recently bounced after years of weaker returns. Is this a quality platform still available at a discounted valuation today?
Most Popular Narrative: 0% Undervalued
The most popular narrative pegs Blackbaud's fair value at $51.50, which is almost identical to the last close of $51.65. That tight gap puts all the focus on whether the business can deliver on the specific earnings drivers included in that estimate.
The main thing that has to go right is continued execution on AI products, longer contract terms, and transaction monetization so that the business can sustain the growth and margin profile it is targeting through 2030.
The current valuation implies that the market is not fully pricing in this narrative that Blackbaud is undervalued relative to its targets for profitable growth, high EBITDA margins, and ongoing share repurchases.
See why 0 investors see Blackbaud as 0% overvalued.
Result: Fair Value of $51.50 (ABOUT RIGHT)
Still, this story can break if rivals undercut Blackbaud on price or if donor and tuition payment volumes soften and squeeze the transaction heavy revenue mix.
Find out about the key risks to this Blackbaud narrative.
Another View On Blackbaud's Valuation
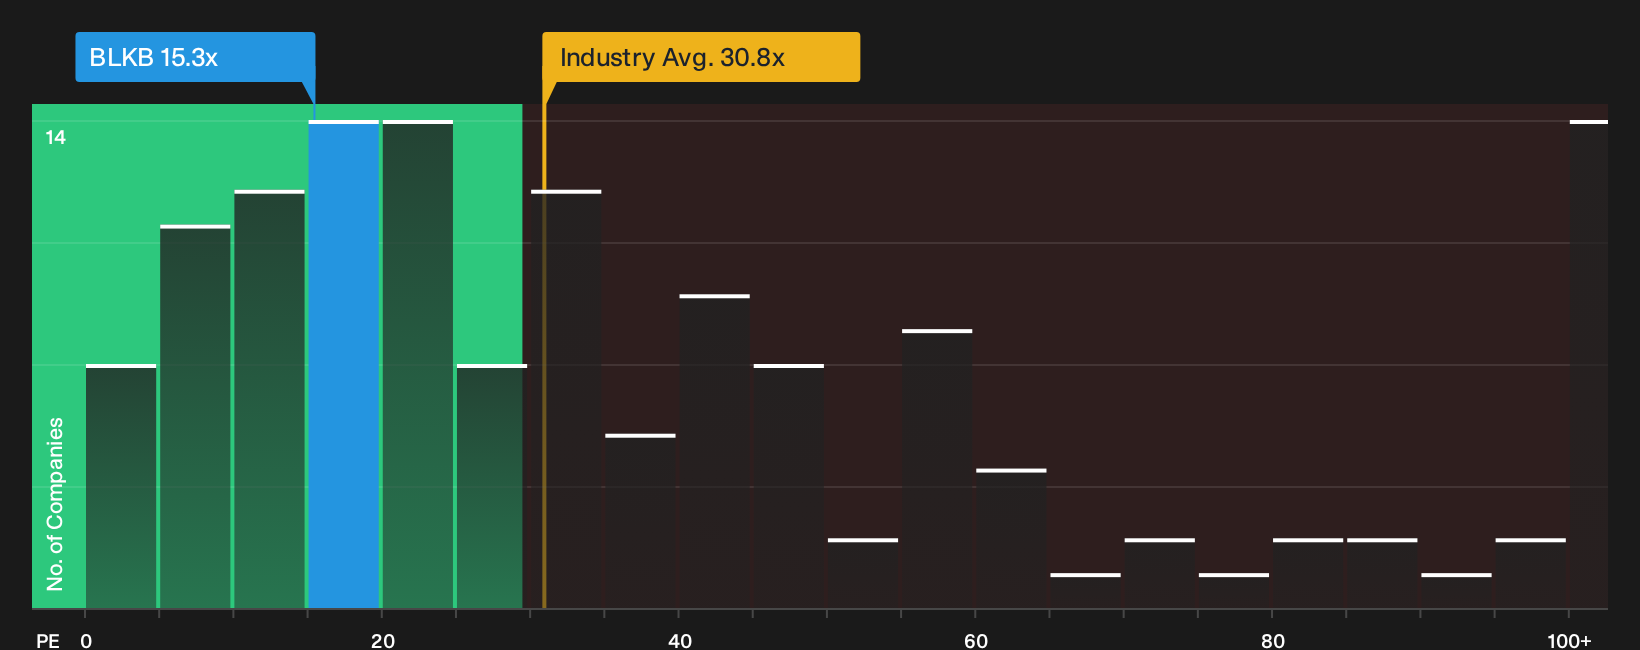
On earnings multiples, Blackbaud looks inexpensive. The shares trade on a P/E of 15.3x compared with a US Software industry average of 30.8x and a peer average of 35.9x, while the fair ratio sits at 23.3x. That gap suggests either mispricing or a meaningful business risk investors still need to weigh.
To see what the numbers say about this price in more detail, take a look at the See what the numbers say about this price — find out in our valuation breakdown.
For a clearer visual of how Blackbaud's current valuation stacks up against sector norms, review the
Next Steps
Mixed messages on Blackbaud's valuation and fundamentals can feel hard to reconcile. Review the data yourself, weigh both the downside and upside, and then check the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Blackbaud?
If Blackbaud has sharpened your sense of value, do not stop here. Broaden your watchlist and pressure test your thinking against a wider set of opportunities.
- Target potential mispricing by running your eye over companies on the 33 high quality undervalued stocks that combine solid earnings power with room for sentiment to catch up.
- Strengthen your downside protection by focusing on businesses screened for resilience and stability through the 32 resilient stocks with low risk scores.
- Get ahead of the crowd by hunting for quality opportunities that fewer investors follow using the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com