
Codan (ASX:CDA), Why Is The Market Taking A Closer Look?
Codan (ASX:CDA) is experiencing a clear demand upswing for its radio communications and metal detection gear, as defense spending and geopolitical risks feed directly into a growing order book and rising revenue momentum.
The recent pullback, with a 7 day share price return down 6.9%, comes after a sharp run in which Codan has delivered a 30 day share price return of 25.1% and a year to date share price gain of 116%. Over the same period, the company has recorded a 1 year total shareholder return of 89.0% and a 3 year total shareholder return of roughly 7x, which signals strong longer term momentum even as shorter term sentiment cools.
Scan Codan alongside other defense and mission-critical communications players by reviewing the 6 resilient stocks with low risk scores, which are built to handle stress tests rather than smooth markets.
After a surge like Codan has logged, with a small pullback on top, the real test now is simple. Does the current price still offer a skew that rewards new risk, or mostly protect prior gains?
Most Popular Narrative: 6% Undervalued
On the numbers in front of you, Codan is trading at A$62.69 against a widely followed fair value marker of A$66.77. That gap rests on a detailed story about defense demand, gold detection and acquisition-led expansion.
Heightened geopolitical tensions, increased defense spending, and the need for resilient communications infrastructure, especially in light of remilitarization and growing demand for unmanned systems, are expanding Codan's customer base and forward order book in defense and public safety, driving both near-term and long-term revenue growth. The integration of Kagwerks and DTC, development of interoperable MESH radio platforms, and the shift toward full-solution communications providers position Codan to capture higher-margin contracts, improve operating leverage, and expand its reach in large, high-growth markets (e.g., U.S., Europe), supporting margin expansion and earnings growth.
See why 40 investors see Codan as 6% undervalued.
On that narrative, the A$66.77 fair value relies on forecast revenue growth of 16.1% a year, a move in net profit margins from 20.0% to 24.5%, and a discount rate of 8.64% to translate those future cash flows back into today’s terms.
The same story also leans on earnings projections that step from A$175.2m now to A$335.8m by around October 2029. The valuation assumes Codan trades on a P/E of 46.6x those future earnings, compared with the current Electronic industry marker of 48.9x in Australia.
For that to hold, the narrative assumes the firm can keep converting defense order momentum, gold detection demand and acquisitions into higher returns on equity. The latest work points to a 32.1% ROE in three years and reinforces why market participants are prepared to assign a premium multiple today.
Result: Fair Value of A$66.77 (UNDERVALUED)
Still, if gold detection demand weakens or big competitors compress communications margins, the Codan narrative that underpins that A$66.77 marker could fracture quickly.
Find out about the key risks to this Codan narrative.
Another View: Codan Looks Expensive On Earnings
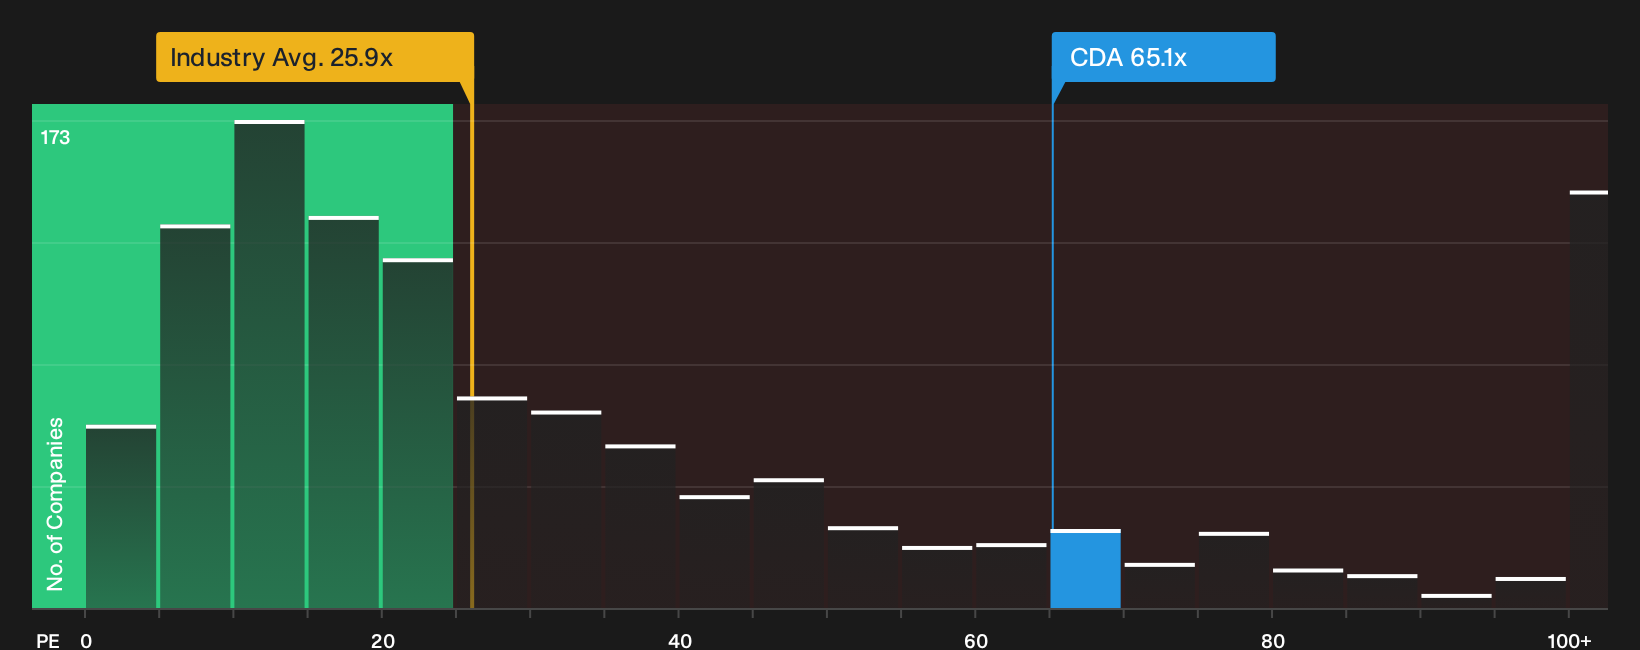
The story shifts when the lens moves from cash flow to what investors are paying for each dollar of Codan earnings. The stock trades on a P/E of 65.1x. That compares with 36.7x for peers, 25.9x for the global Electronic group, and a fair ratio of 47.7x.
This gap means buyers today are paying a hefty premium that could compress if sentiment cools or if results fall short of expectations. The question is simple. Are you comfortable underwriting that kind of multiple risk on Codan at this stage of the cycle?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Opinions on Codan are strong on both value and risk, so treat this as your prompt to move quickly, test the assumptions, and study the 2 key rewards.
Looking for more investment ideas beyond Codan?
If Codan has your attention, do not stop here. Broaden your watchlist now so you are not chasing the next opportunity after it already runs.
- Target quality at a discount by scanning the 4 high quality undervalued stocks that combine strong fundamentals with attractive entry points.
- Strengthen your downside protection by reviewing a list of solid balance sheet and fundamentals (12 results) that can better handle shocks when conditions turn rough.
- Get ahead of the crowd by hunting through 15 high quality undiscovered gems before they move onto everyone else's radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com