
Natera (NTRA) Gains Fresh Clinical Backing As Fair Value Debate Stays Open
Natera (NTRA) has moved back into focus after its Signatera Genome technology was featured in 20 abstracts at the 2026 ESMO Congress, along with fresh FDA Breakthrough Device status for its multi-cancer early detection assay.
Investors have been rewarding this stream of clinical milestones, with Natera’s share price up 47.26% over the past 90 days and delivering a very large 3-year total shareholder return, even though the stock has slipped 2.80% over the past day and 1.09% over the past week.
Scan how Natera’s momentum in cancer diagnostics compares with a hand picked group of 33 healthcare AI stocks pushing the boundaries of data driven medicine.
After a 47% run in three months and a very large 3 year return, Natera now sits near its analyst target. Is meaningful upside still on the table, or has most of the move already played out on valuation?
Most Popular Narrative: 3% Undervalued
Natera’s last close at $393.44 sits modestly below the most followed fair value estimate of $403.89. This estimate is built on detailed growth and margin forecasts. That gap sets the stage for a thesis that backs today’s price with ambitious assumptions on diagnostics adoption, AI, and new products.
Investment in new product launches (e.g., Fetal Focus NIPT, Signatera Genome, AI-based biomarkers) and a robust R&D pipeline positions Natera to capture growth from long-term trends in personalized medicine and early detection, underpinning future revenue expansion.
See why 18 investors see Natera as 3% undervalued.
Result: Fair Value of $403.89 (UNDERVALUED)
Still, Natera’s story can change quickly if reimbursement for key tests tightens or if heavy R&D and commercial spending delays any path to sustained profitability.
Find out about the key risks to this Natera narrative.
Another View: Rich Multiples Around Natera
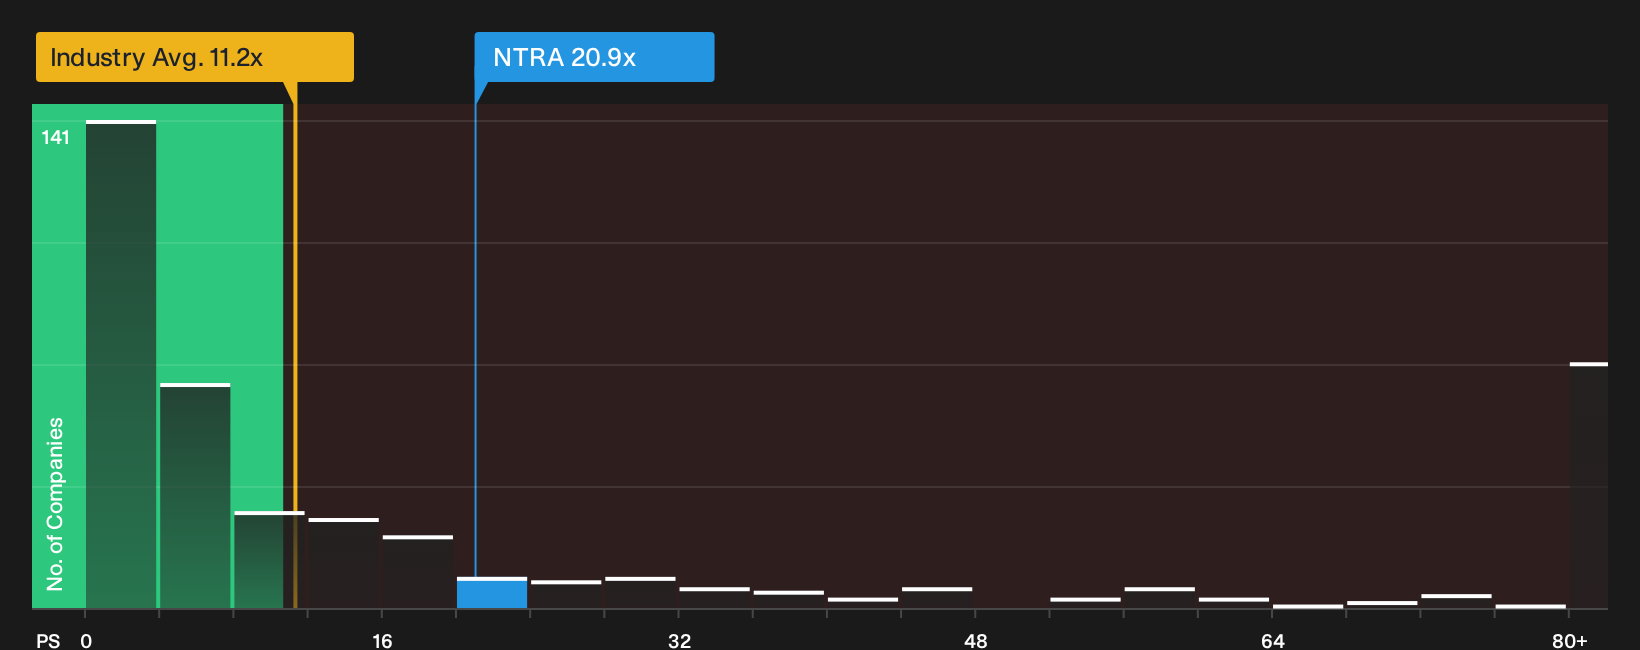
The first fair value narrative paints Natera as modestly undervalued. A different lens tells a sharper story on pricing power. On P/S, the stock trades at 20.9x, while direct peers sit near 9.2x and the broader US biotechs group is close to 11.2x.
That is almost double both the peer average and the industry, and well above an estimated fair ratio of 11x that the market could eventually lean toward. For you, that gap can look like enthusiasm that still has room to run, or like valuation risk that leaves little margin for disappointment.
To see what the numbers say about this price, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If the split views on Natera leave you unsure, that is the point. Act while sentiment is still forming and carefully weigh the 3 key rewards against your own reading of the data.
Looking for more ideas beyond Natera?
If Natera has your attention, do not stop here. Broaden your watchlist with fresh ideas built from the same data driven approach powering this analysis.
- Spot potential mispricings early by scanning a 33 high quality undervalued stocks that filters for quality fundamentals and room for sentiment to catch up.
- Lock in steadier cash flow potential by reviewing a 8 dividend fortresses that focuses on income streams above 5% with balance sheet support.
- Dial back portfolio risk by checking a 32 resilient stocks with low risk scores that highlights resilient businesses with stronger overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com