
Ubtech Robotics (SEHK:9880) Expands In Ras Al Khaimah, Is The Stock Fully Valued?
New Ras Al Khaimah partnership puts Ubtech Robotics in focus
A fresh Memorandum of Understanding between Ubtech Robotics (SEHK:9880) and the Government of Ras Al Khaimah is drawing attention, as investors weigh how Gulf-based humanoid robot trials might influence sentiment toward the Hong Kong listed stock.
Set against a year-to-date share price return that has fallen 50.73% and a 1-year total shareholder return that is down 52.11%, the recent 3.03% 1-day share price gain to HK$64.55 comes after a 30-day share price return that declined 20.16%. This suggests sentiment around Ubtech Robotics is still fragile despite interest in the Ras Al Khaimah partnership.
Compare Ubtech Robotics with a curated set of peers by scanning 92 robotics and automation stocks, which could also benefit as humanoid and automation projects gain traction in sectors like logistics, healthcare, and tourism.
Ubtech Robotics has a broad product range and fresh Gulf exposure, yet the share price has fallen sharply this year and has only just bounced. Is that weakness still justified by the valuation or not?
Preferred Price-to-Sales of 10.4x: Is it justified for Ubtech Robotics?
On the simple numbers, Ubtech Robotics trades on a P/S ratio of 10.4x, which looks rich next to both its Hong Kong Machinery peers and its own fair ratio estimate, even with the recent share price pullback to HK$64.55.
The P/S multiple compares the market value of the equity to the revenue the business generates. For a robotics group like Ubtech Robotics that is currently unprofitable, this metric often becomes the default way investors benchmark what they are paying for each unit of sales when earnings are not yet a clean guide.
Here, the current P/S of 10.4x is described as expensive versus the Hong Kong Machinery industry average of 1x and even marginally stretched versus the peer average of 10.2x. The assessment also flags an estimated fair P/S ratio of 8.4x, which is materially lower than where the shares change hands and could be a level the market moves toward if enthusiasm around future growth cools.
Explore the SWS fair ratio for Ubtech Robotics.
Result: Price-to-Sales of 10.4x (OVERVALUED)
Still, weak recent returns, ongoing losses of CN¥601.021m, and a valuation above the estimated fair P/S could quickly cap enthusiasm around Ubtech Robotics.
Find out about the key risks to this Ubtech Robotics narrative.
Another view on Ubtech Robotics using the SWS DCF model
The multiple-based read on Ubtech Robotics already looks demanding, yet the SWS DCF model comes out even harsher. At HK$64.55 the shares are described as trading well above an estimated future cash flow value of about HK$1, which implies very little margin for error if expectations shift.
Look into how the SWS DCF model arrives at its fair value.
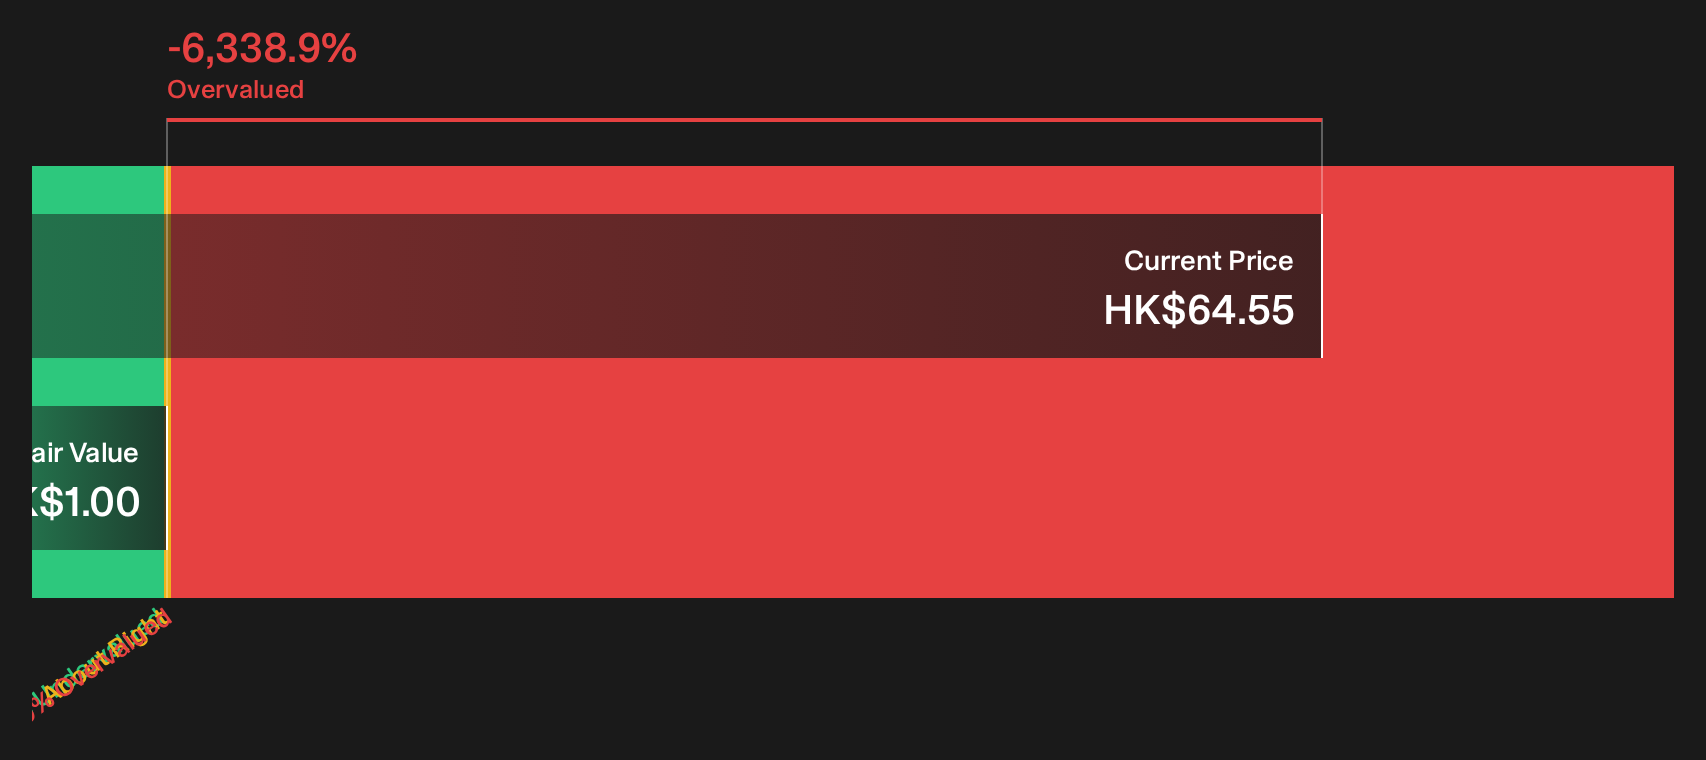
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ubtech Robotics for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 194 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
After a setup this cautious around Ubtech Robotics, it makes sense to pull up the numbers yourself and pressure test the assumptions quickly. To see what the more optimistic investors are focusing on, review the 2 key rewards.
Looking for more investment ideas beyond Ubtech Robotics?
If Ubtech Robotics has sharpened your thinking, do not stop at one ticker. A broader watchlist can reveal opportunities that fit your risk and return preferences.
- Target potential mispricing by reviewing companies on the 194 high quality undervalued stocks and see which ones line up with your return expectations.
- Focus on resilience and staying power by checking out the list of solid balance sheet and fundamentals (203 results) that may better handle tough operating conditions.
- Hunt for potential future leaders early by scanning the 613 high quality undiscovered gems before attention and capital move on to the next theme.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com