
3 Critical Infrastructure Stocks Riding The AI Data Center Buildout
Capital is already moving. JPMorgan has put US$230b to work in year one of its US$1.5t Security and Resiliency Initiative, and that kind of long-horizon spending can reshape which stocks quietly compound and which get left behind. If you care about where real money is flowing rather than headlines, this is your moment. This article walks through three stocks exposed to that news and how this theme could affect their future risk and reward.
The stocks highlighted below are a small sample of what this theme touches, and the full screen surfaced 25 more companies with equally compelling infrastructure narratives that are not covered in this article. If you want to move beyond examples and start lining up your own watchlist, head straight to the North American and European Critical-Infrastructure Builders screener to identify, filter, and analyze potential high-conviction critical-infrastructure builders.
Fluence Energy (FLNC)
Overview: Fluence Energy builds and operates grid-scale battery storage systems and software that help modern power networks integrate renewables reliably.
Operations: Fluence Energy generates about US$2.6b from batteries and battery systems, with additional revenue from Asia Pacific and EMEA regions.
Market Cap: US$1.1b
For a theme built around real-world critical infrastructure, Fluence Energy is where the data centers, renewables, and power grids all meet, and the long-term demand story for that kind of grid plumbing is a key focus area for major capital allocators.
"Rapid global electrification and surging power demand, driven by data centers, transportation, and industrial sectors, are expected to increase the need for grid resilience and flexibility, with significant implications for large-scale battery storage."
What really matters now is how one unresolved cost and execution pressure shapes the path from that demand picture to future margins.
That margin puzzle is exactly where things get interesting for long-term holders, and the full narrative for Fluence Energy breaks down what could be accelerating, what might be stalling, or what could be quietly masking risk.

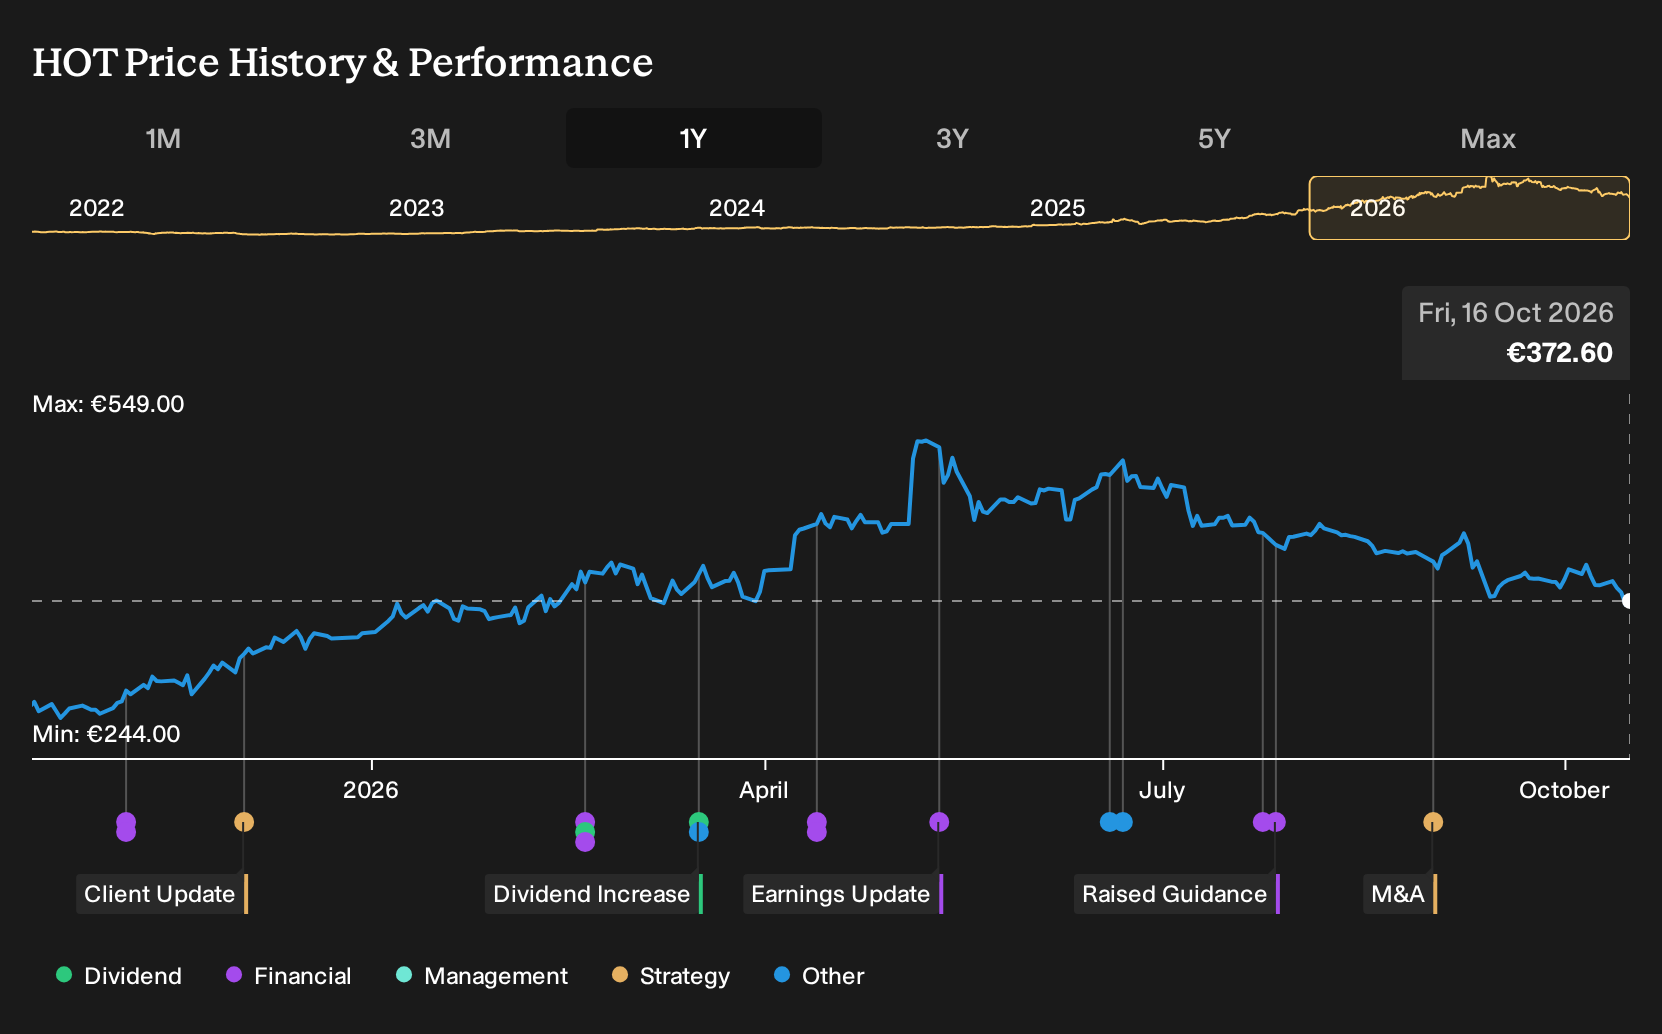
HOCHTIEF (XTRA:HOT)
Overview: HOCHTIEF is a global construction group that delivers large, complex infrastructure projects for energy, transport, data, and industrial clients across key Western markets.
Operations: HOCHTIEF generates about €27.7b from Turner and €10.5b from CIMIC, with €1.7b from European engineering and construction activities.
Market Cap: €28.0b
HOCHTIEF matters for this critical-infrastructure screen because it already sits inside the big project pipelines where energy security, AI data capacity, and defense facilities intersect.
"Surging demand for AI driven digital infrastructure, with HOCHTIEF reporting around €16.8 billion of data center orders in 2025 and data centers already at 21% of the backlog, provides multi year visibility that could support higher revenue and operational earnings if margins in this segment remain firm."
What really shapes how HOCHTIEF converts that visibility into lasting value is how one quiet pressure on future project economics ultimately resolves.
If you want to see how that pressure could be accelerating or masking value at HOCHTIEF, read the full narrative for HOCHTIEF to understand the potential upside and associated risks.
Vertiv Holdings Co (VRT)
Overview: Vertiv Holdings Co designs and services power, cooling, and infrastructure systems that keep AI heavy data centers and communication networks running.
Operations: Vertiv generates about US$7.5b from the Americas, US$2.7b from Asia Pacific, and US$2.4b from Europe, the Middle East, and Africa.
Market Cap: US$79.5b
Vertiv matters in this screener because it supplies the electrical and thermal plumbing that lets AI factories, cloud campuses, and national networks actually stay online.
"The liquid cooling market is already growing at roughly 20 to 30% annually as hyperscalers like Microsoft, Google, and Amazon race to build AI infrastructure. Vertiv's Q4 2025 organic orders surged 252% year over year, and its $15 billion backlog is equivalent to roughly 1.5 years of trailing revenue."
What investors will watch closely now is how one quiet shift in project mix filters through to future pricing power and profitability.
As that project mix shifts, read the full narrative for Vertiv Holdings Co to see whether Vertiv Holdings Co is quietly accelerating durable cash generation or masking new execution risk.

Seeking Fresh Alternatives Before They Fly
Fresh opportunities rarely stay quiet for long. Breakout momentum, dropping mispricings, and under the radar ideas can be caught early only once. Consider acting before the wider market responds.
- Track cash rich operators built to ride volatile cycles. Then sort through the list of solid balance sheet and fundamentals (25 results) while it matters and build a shortlist before everyone else reacts.
- Identify potential miners tied to critical metals. Scan the 32 best rare earth metal stocks and review candidates while prices still look reasonable.
- Follow the AI build out with hardware suppliers already generating profits. Filter the 39 profitable AI stocks that aren't just burning cash and focus on businesses funding expansion from real earnings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com