
Is Barrick Mining (B) Undervalued Following Its Rebrand To Barrick Mining?
Barrick Mining (B) is back in focus after its corporate name change from Barrick Gold Corporation in May 2025, a move that widened its mandate across gold, copper, silver, and energy materials.
The recent rebrand to Barrick Mining has arrived during a mixed spell for the share price, with the stock at US$40.82 after a 30 day share price return that fell 5.79%, but a 90 day gain of 12.24% and a 1 year total shareholder return of 19.99% pointing to momentum that has built over a longer stretch.
Extend your view beyond Barrick Mining and scan a curated set of peers with 36 elite gold producer stocks that are also tied to bullion pricing, mine quality, and capital discipline.
The rebrand, the 1 year return near 20%, and a US$40.82 share price leave a simple tension for Barrick Mining. Is the stronger run largely spent, or is valuation still pointing to meaningful upside ahead?
Price-to-Earnings of 10.3x: Is it justified?
On simple earnings terms, Barrick Mining looks inexpensive, with a P/E of 10.3x that screens as good value against peers even after a 1 year total return near 20% and a last close of $40.82.
The P/E ratio compares what investors pay today for each dollar of profit. It is especially watched in sectors like metals and mining where earnings can move sharply with commodity prices. For Barrick Mining, a 10.3x P/E implies the market is attaching a relatively low price tag to its current earnings base.
Analysts assessing the business see that multiple as low in several ways. The stock trades on a P/E below the US market level of 18.1x, below the US Metals and Mining industry average of 18.6x, and below the peer group average of 17.6x. Together, these comparisons point to the market pricing Barrick Mining at a clear discount to many comparable listings. That same framework suggests a fair P/E closer to 19.7x, a level the valuation work indicates the ratio could reasonably move toward if sentiment or positioning shifted.
Explore the SWS fair ratio for Barrick Mining.
Result: Price-to-Earnings of 10.3x (UNDERVALUED)
Still, Barrick Mining faces clear risks if metal prices weaken or if key operations such as Carlin or Pueblo Viejo encounter cost or production setbacks.
Find out about the key risks to this Barrick Mining narrative.
Another View: SWS DCF model points the other way
Look past the earnings multiple and the picture shifts. Our DCF model pegs Barrick Mining's future cash flow value at $34.53 per share while the stock trades at $40.82. On that lens, the shares appear overvalued, which raises a simple question for investors: Which signal deserves more weight, cheap earnings or a rich cash flow profile?
Look into how the SWS DCF model arrives at its fair value.
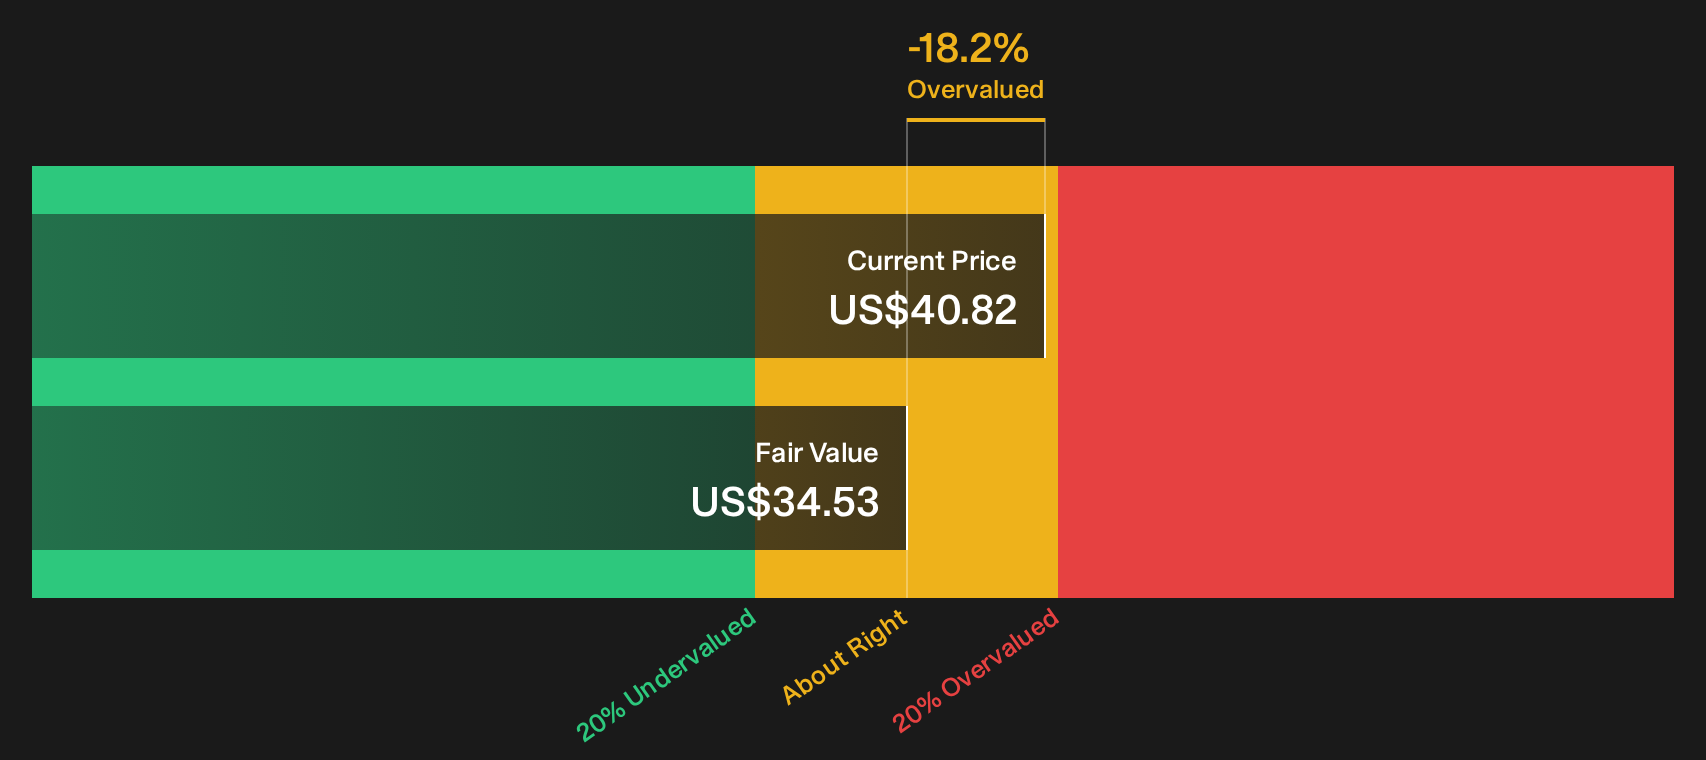
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Barrick Mining for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Barrick Mining's valuation and risk profile do not need to leave you stuck on the fence. Move quickly, review the numbers yourself, and weigh up the 3 key rewards and 2 important warning signs.
Looking for more ideas beyond Barrick Mining?
Do not stop at a single ticker. Use the Simply Wall Street Screener to surface fresh investment angles that line up with your risk level and return goals.
- Target quality at a discount by scanning companies that combine strong fundamentals with appealing valuations through the 33 high quality undervalued stocks.
- Strengthen portfolio resilience by zeroing in on businesses with sturdy finances using the list of solid balance sheet and fundamentals (25 results).
- Spot under-the-radar potential by reviewing companies with solid numbers that have limited coverage via the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com