
How Investors May Respond To SoftBank (TSE:9434) Ohio AI Data Center Plan
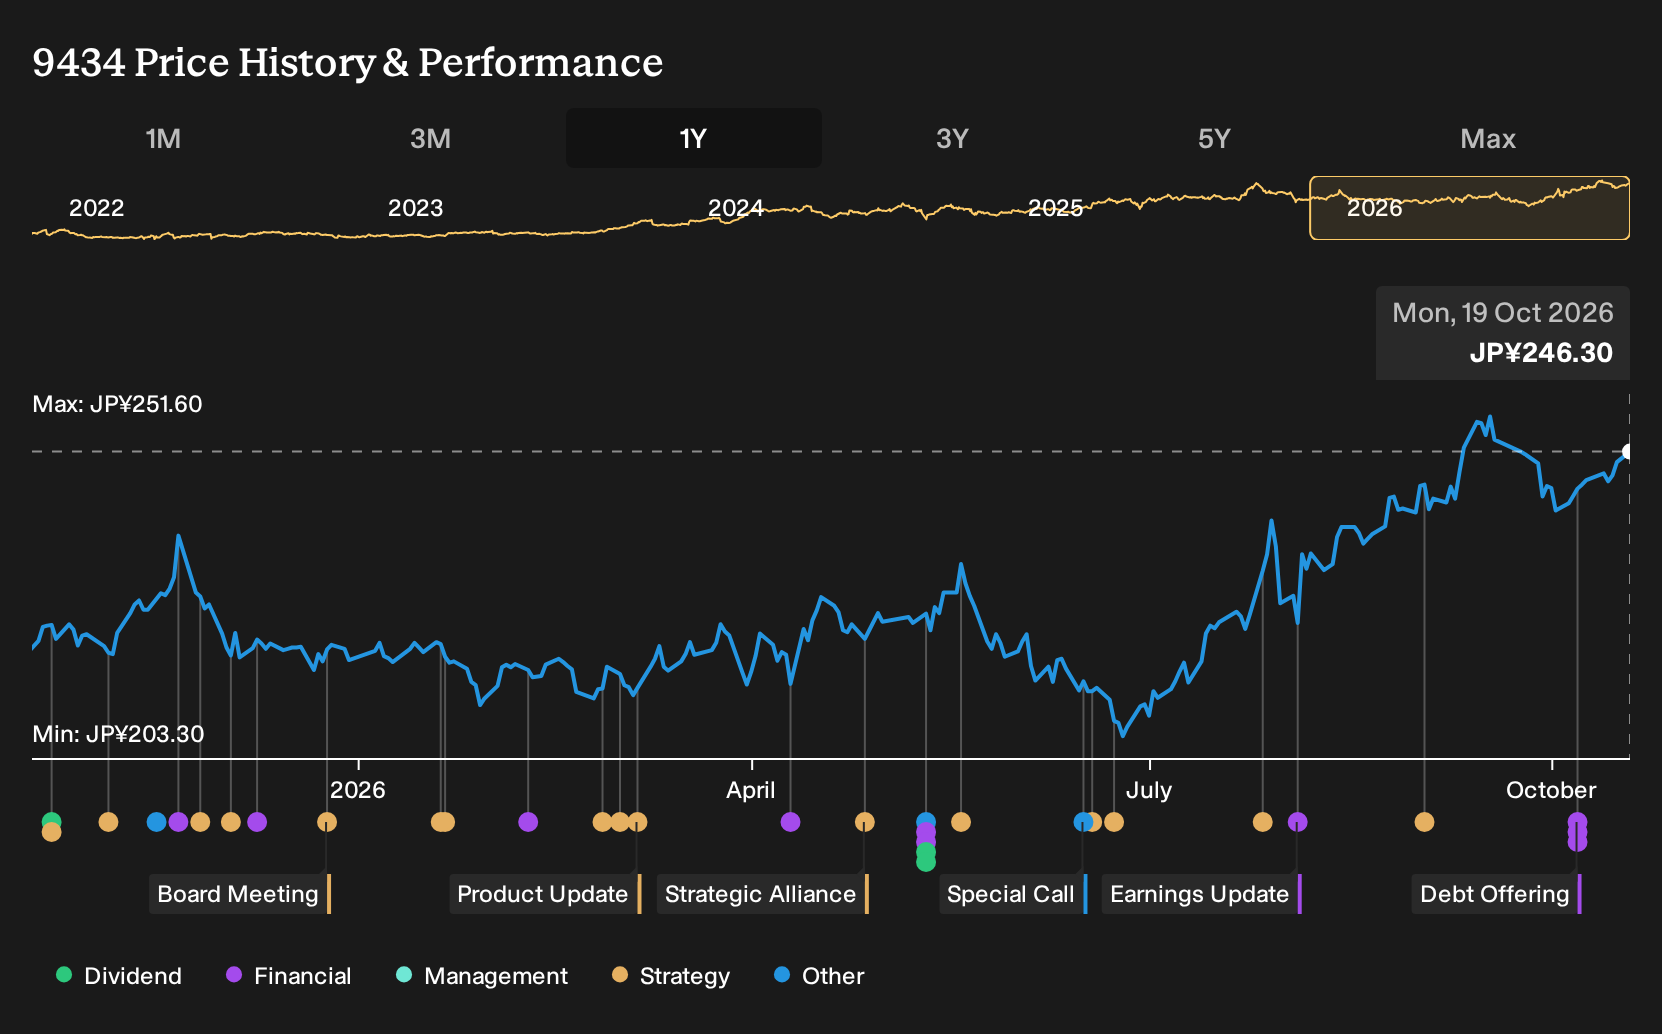
- SoftBank Corp. recently issued unsecured straight corporate bonds in Japan, including ¥2.4b notes due October 14, 2033, and multiple tranches totaling ¥30b maturing October 12, 2029.
- The bond issuance accompanies SoftBank Group’s plan for a 10 GW AI data center complex in Ohio, highlighting sizable funding needs for digital infrastructure and long dated AI capacity build out.
- We will now examine how SoftBank's investment narrative could be reshaped by the 10 GW AI data center project in Ohio.
Scan beyond SoftBank and line up other potential beneficiaries of the AI infrastructure build out by reviewing our curated list of 55 AI infrastructure stocks.
SoftBank Investment Narrative Recap
To own SoftBank, you need to believe the heavy AI and data center push eventually supports steadier earnings and cash generation rather than just a bigger capex bill. The 10 GW Ohio project and fresh unsecured bonds underline that this is an infrastructure heavy story. For now, the near term upside still hinges on executing AI and cloud services without losing focus on the core telecom and payments engine.
The biggest operational risk is that high AI related spending, including SB Neo and now Ohio, keeps free cash flow tight while debt already screens as elevated. These new bonds do not radically change that picture by themselves. What really matters is whether the Enterprise, Financial, and Media & EC segments can keep justifying the higher capital intensity through recurring fees and higher margin digital services.
The straight bonds maturing in 2029 and 2033 are the clearest link between this news and the existing SoftBank catalyst path. Management is leaning on unsecured external funding at a time when analysts already flag that 100% of liabilities come from higher risk sources such as borrowing rather than deposits. That structure can work, but it leaves less room if AI related returns arrive more slowly than anticipated.
For you as a shareholder, the key question is whether incremental bond financed capex into AI data centers shortens or lengthens the path to the earnings profile analysts model. The Ohio plan sits alongside SB Neo, domestic AI computing, and cybersecurity offerings that are designed to deepen enterprise and financial services revenue. Execution on those projects, rather than the funding mix itself, is likely to drive how the next few years feel in this stock.
SoftBank's analyst narrative points to revenues of ¥8,632.9b and earnings of ¥707.8b by 2029, based on 6.3% yearly revenue growth and an earnings increase of about ¥161.7b from ¥546.1b today.
Uncover how SoftBank's fair value indicates an 11% potential upside to its current price before other investors close the gap.
Exploring Other Perspectives
One alternate angle treats the Ohio AI build as a clear upside catalyst. Bullish analysts were already penciling in faster progress, with revenue reaching ¥9,191.3b and earnings of ¥760.1b by 2029, alongside a higher 24.9x P/E. Those forecasts came before this bond funded project, so you may want to explore how views could shift.
Explore another SoftBank fair value estimate, including one that suggests as much as 25% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your SoftBank research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for SoftBank. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SoftBank's overall financial health at a glance.
Looking for more investment ideas beyond SoftBank?
Once you have formed a view on SoftBank, it often helps to compare the opportunity with other businesses that fit different risk and quality profiles. The Simply Wall St Screener can narrow that universe quickly so you spend less time sorting and more time weighing trade offs.
- If you want potential value upside with quality fundamentals, line up candidates using our curated 13 high quality undervalued stocks and see which ones deserve a closer look.
- For investors who care most about capital preservation and steadier profiles, filter the market with a focused 22 resilient stocks with low risk scores that surfaces companies with lower risk scores.
- When you want strong balance sheets and solid business foundations, build a watchlist from the list of solid balance sheet and fundamentals (22 results) and compare them side by side with your current holdings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com