
Gildan Activewear (TSX:GIL) Stock Looks About Right After Its 56% Gain
Gildan Activewear has seen its share price fall sharply this year, and the drop has arrived just as questions around the quality of its reported earnings have become more pointed. With legal scrutiny building and sentiment clearly weaker, the issue for investors is whether the current valuation still lines up with what the business earns.
- Over the past 3 years the stock has gained 56%, which puts earlier buyers in a very different position from anyone weighing up the earnings multiple at today's level.
- Legal actions tied to alleged sales practices and potential chemical use in apparel may affect how investors think about the durability of Gildan Activewear's margins and the reliability of its reported profit stream.
- Your read on Gildan Activewear is one view; the desks covering it have another. See what analysts think Gildan Activewear's shares could be worth.
The stock's next move may depend on whether Gildan Activewear's current share price can be justified by the earnings that support it today.
For a broader read on how other businesses with solid balance sheets and fundamentals are priced on their earnings, compare Gildan Activewear with the solid balance sheet and fundamentals stocks screener (8 results).
Where Does Gildan Activewear Sit on Earnings?
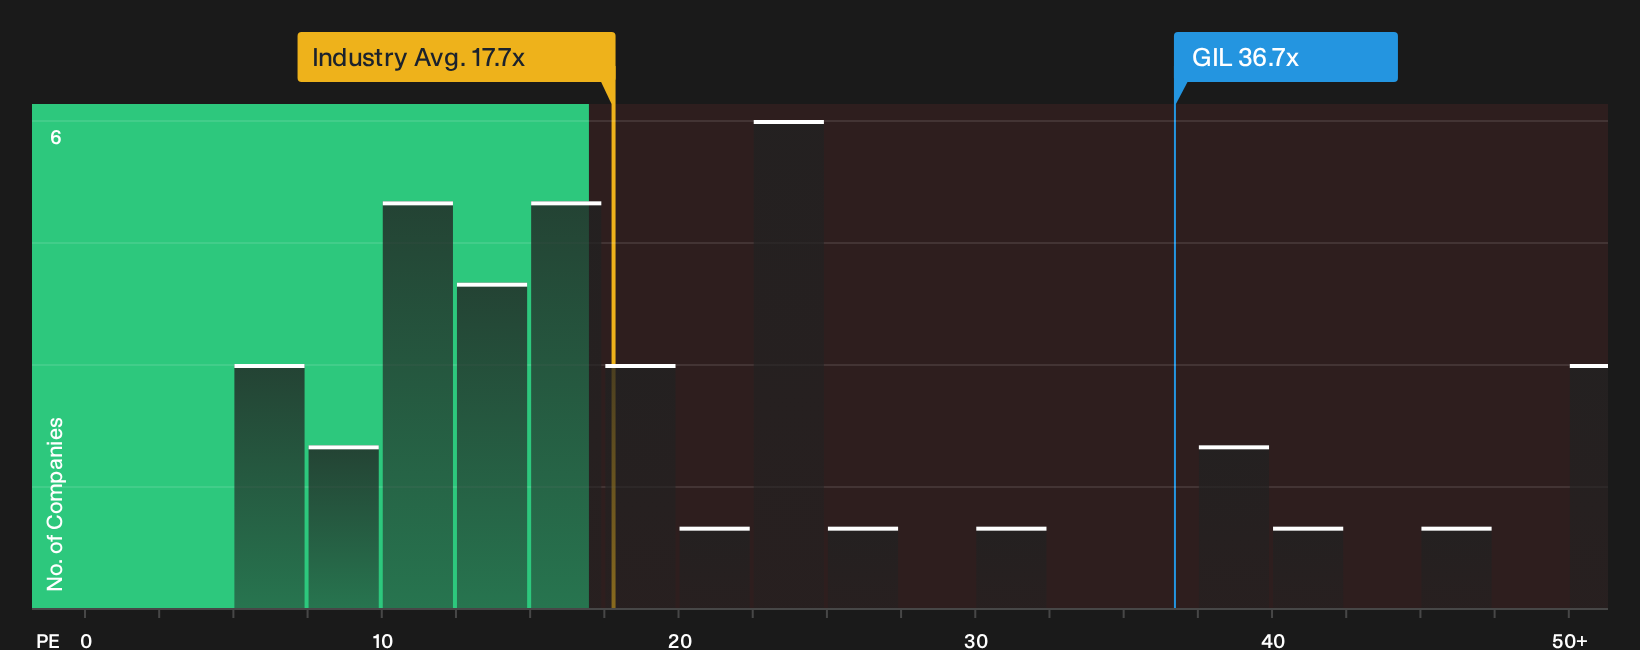
The P/E ratio works well for Gildan Activewear because profit is a key focus for how investors are framing the story. On current numbers, the stock trades on about 36.7x earnings, compared with an industry average near 15.9x for Luxury stocks and a peer group around 29.9x. That points to investors paying a premium for each dollar of profit relative to the broader sector and to direct comparables.
The fair P/E that models Gildan Activewear's growth profile, margins, size and risk comes out slightly above where the shares trade today. As a result, the current multiple sits a little under that tailored benchmark. Because the recent short seller report and related class action have raised questions around the quality of reported growth, this premium against the sector still leaves a lot riding on how those allegations and investigations are resolved. Explore the numbers behind Gildan Activewear's P/E valuation.
The Gildan Activewear Narrative: What Would Justify Today's Price?
Narratives on Gildan Activewear pick up where the valuation puzzle leaves off by spelling out what kind of future growth, margins and earnings profile would need to play out for the stock to be worth materially more or less than it is today, and sit on Simply Wall St's Community page. Rather than stopping at a single P/E or model output, each scenario lays out the moving parts behind its view of fair value so you can compare those assumptions with actual results over time.
One of the top community narratives on Gildan Activewear: 44% undervalued
"Gildan's cost-efficient, ethically focused manufacturing and value-oriented products provide strong competitive advantages and support growth amid shifting consumer and regulatory trends..."
Discover why this Narrative puts Gildan Activewear at 44% undervalued.
One more Gildan Activewear check to weigh alongside the share price
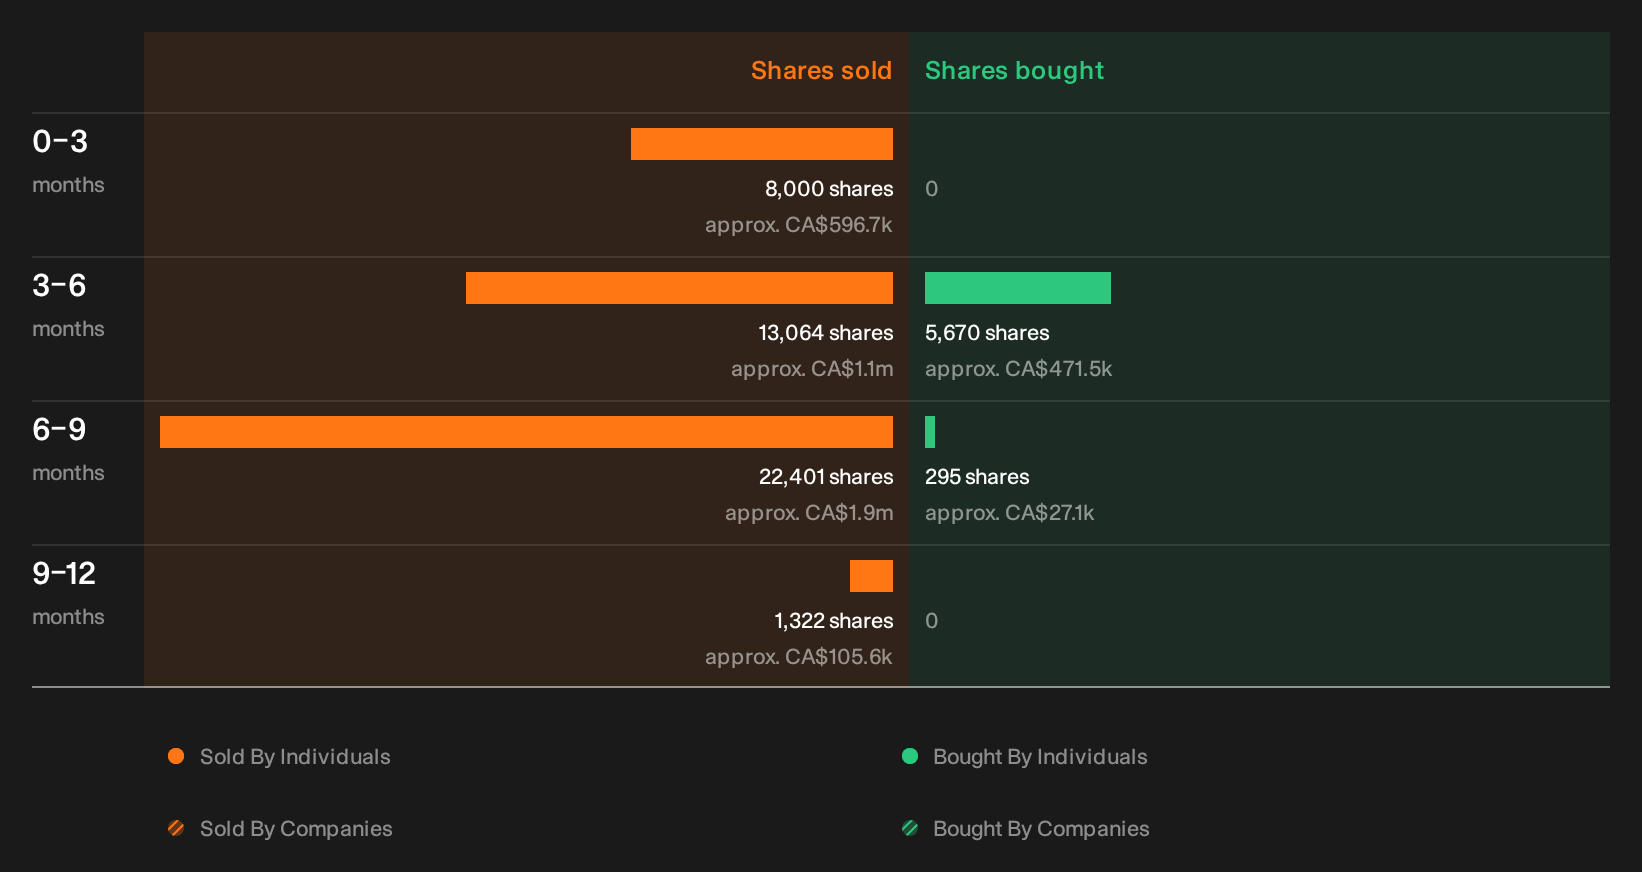
Before closing the file on Gildan Activewear, it is worth knowing that our checks have picked up recent stock sales by people on the inside, with the sellers, scale and possible read throughs left for you to review. See the recent insider selling flagged for Gildan Activewear.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com