
NetScout Systems (NTCT) Could Be 43% Undervalued If Its Growth Story Holds
NetScout Systems (NTCT) drew fresh attention after recent trading left the share price at US$38.07. Investors are weighing that level against the company’s value score of 4 and estimated intrinsic discount of 42.6%.
Recent trading has cooled some of the momentum in NetScout Systems, with the share price return down 1.8% over one day and 4.9% over the past week. However, the year to date share price return of 41.8% and 1 year total shareholder return of 43.8% still point to gains that investors are now comparing closely with its indicated 42.6% intrinsic discount and value score of 4.
Scan beyond NetScout Systems and explore other potential value ideas in our curated list of 33 high quality undervalued stocks that combine solid fundamentals with a discounted price tag.
NetScout Systems appears to be a solid specialist in network assurance and cybersecurity, but the recent pullback complicates the picture. Is this still a strong business offered at a mispriced tag, or has the easy value already been taken?
Most Popular Narrative: 9% Undervalued
NetScout Systems is trading at $38.07 against a widely followed fair value estimate of $41.71, so the narrative implies some remaining upside that hinges on how its growth and capital choices play out.
Market optimism appears to be driven by strong recent growth in NetScout's cybersecurity segment, underpinned by customers prioritizing spending to counter increasingly complex and expanding cyber threats. This may lead investors to expect above-trend long-term revenue and earnings growth. There is a narrative that NetScout's integration of AI-driven capabilities (such as Omnis AI Insights and AI-backed enhancements in DDoS defense) positions the company as a differentiated leader in an expanding observability and cybersecurity market. This in turn may prompt unrealistic expectations for sustained margin expansion and premium revenue multiples.
See why 3 investors see NetScout Systems as 9% undervalued.
Result: Fair Value of $41.71 (UNDERVALUED)
Still, that bullish NetScout Systems narrative could crack if cloud migration accelerates away from its legacy tools, or if IT buyers consolidate security budgets around fewer platforms.
Find out about the key risks to this NetScout Systems narrative.
Another View On NetScout Systems Valuation
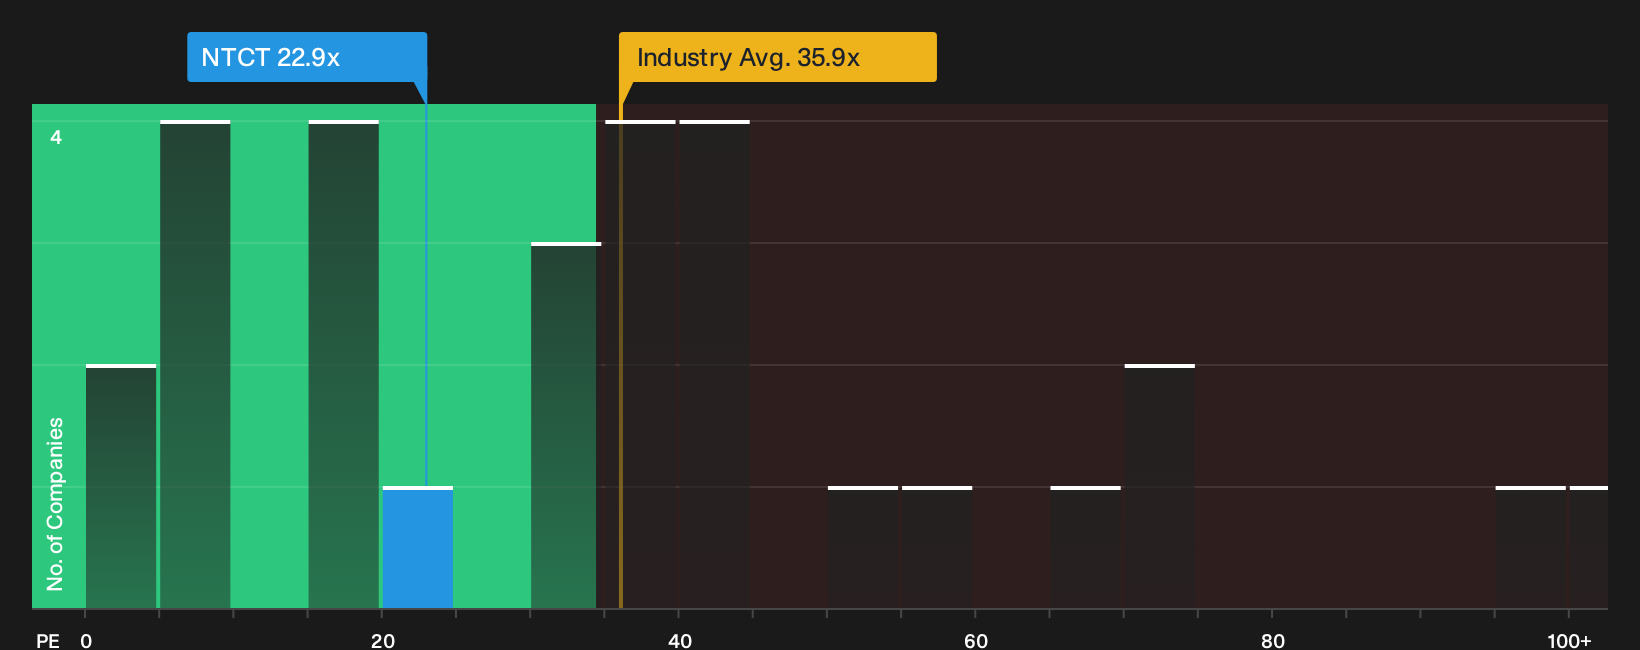
The first story frames NetScout Systems as 42.6% below an assessed fair value of $66.34 using a cash flow model. A different lens tells a cooler story. At a P/E of 22.9x against a fair ratio of 16.4x, the stock screens expensive even though it trades below peers and the wider US Communications industry. Which picture do you think is closer to reality for your own risk tolerance?
See what the numbers say before you lean too hard on either framework by checking the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on NetScout Systems is clearly split, which is exactly why it pays to review the figures yourself and move quickly while opinions are still forming. To weigh both sides of the story in one place, start with the 2 key rewards and 1 important warning sign.
Looking for more NetScout Systems style investment ideas?
Do not stop your research with NetScout Systems. Cast a wider net now using the Simply Wall Street Screener so you do not overlook compelling opportunities with strong fundamentals, income potential, or resilience.
- Target dependable balance sheets and healthier fundamentals by scanning the list of solid balance sheet and fundamentals (25 results) that could help anchor a more resilient portfolio.
- Spot potential mispricings before they attract wider attention by reviewing the 20 high quality undiscovered gems that already clear quality and fundamentals checks.
- Prioritise stability and lower volatility by assessing the 32 resilient stocks with low risk scores that align with a more defensive approach to building long term wealth.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com