
FLSmidth (CPSE:FLS) Could Be 11% Below Fair Value On Mining Order Momentum
FLSmidth (CPSE:FLS) just lined up three sizeable mining equipment orders and a new operational excellence chief, giving investors fresh information on demand for its technology and its execution priorities.
Set against this contract news and the new operational excellence hire, FLSmidth’s share price at DKK588.5 comes after a 90-day share price return of 27.16% and a year-to-date share price gain of 30.72%, while the 5-year total shareholder return of 160.29% points to momentum that has been building over a longer stretch.
Scan how FLSmidth’s recent contract wins compare with peers by reviewing the 42 power grid technology and infrastructure stocks that are feeding into long-horizon infrastructure and resource projects.
The contract pipeline, leadership hire and 30% year-to-date share gain paint two very different stories for FLSmidth. Is this jump mostly about stronger fundamentals, or about investors crowding into the theme?
Most Popular Narrative: 11% Undervalued
FLSmidth’s most followed thesis puts fair value at DKK660.42, above the DKK588.5 last close. This frames the recent contract wins as part of a broader rerating story rather than a short term spike.
The main thing that has to go right is continued execution in Services and Pumps, Cyclones & Valves so that strong order intake, margins and the turnaround in Products translate into sustained cash generation despite current working capital pressure.
The current valuation implies the market is cautious that FLSmidth’s improved margins, mining focus and sizeable share buyback can be maintained. This leaves room for upside if the company’s profitability and capital returns are sustained.
See why 9 investors see FLSmidth as 11% undervalued.
Result: Fair Value of DKK660.42 (UNDERVALUED)
Still, the narrative around FLSmidth can change quickly if cash conversion stays weak or if mining customers delay turning the current project pipeline into firm orders.
Find out about the key risks to this FLSmidth narrative.
Another View: What FLSmidth’s P/E Is Really Saying
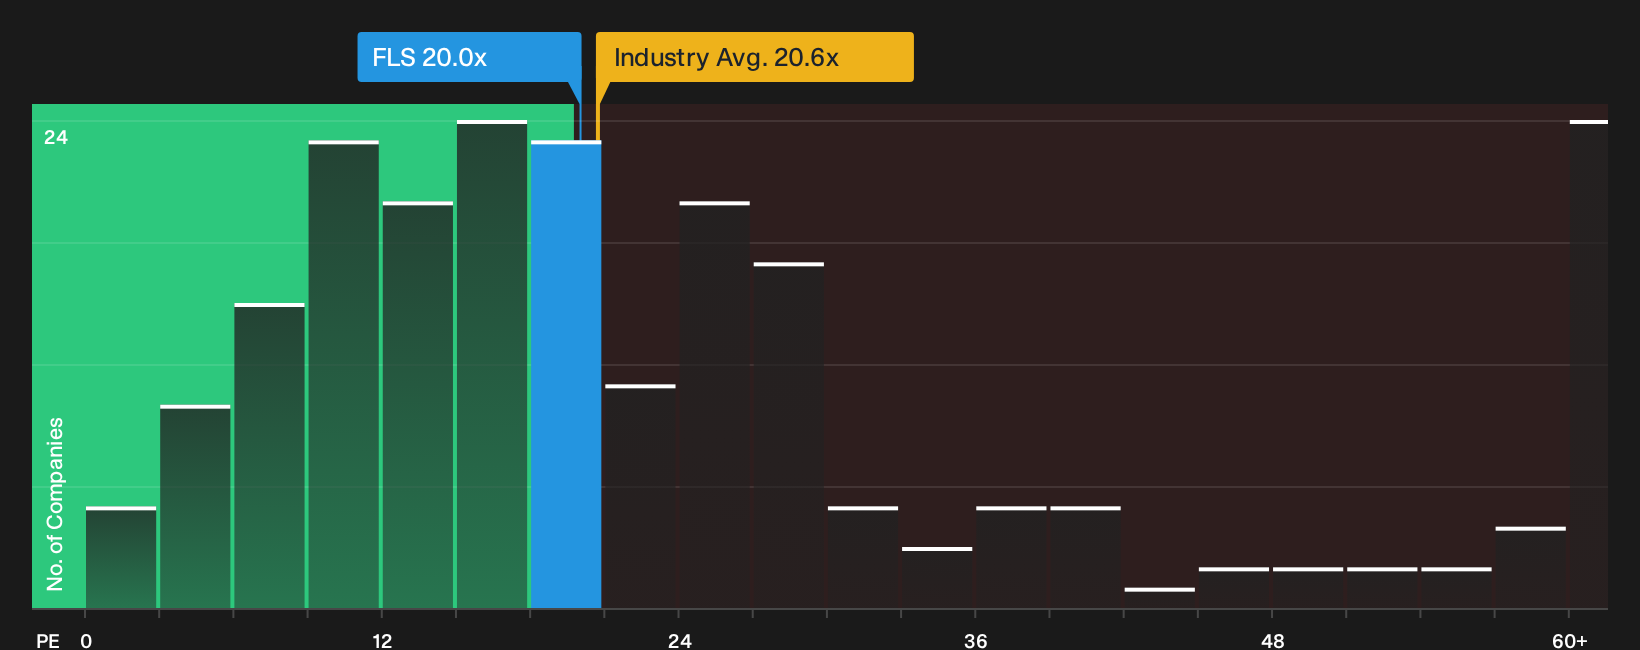
FLSmidth looks cheap on one lens and expensive on another. The shares trade on a P/E of 20x, lower than peers at 29.1x and slightly below the European Machinery group at 20.6x, yet still above a fair ratio of 14.3x.
For an investor, that mix points to a stock that screens attractively against sector rivals but carries valuation risk if the market drifts toward the lower fair ratio. The key question is whether current earnings quality and growth can support the higher multiple or if you want more of a discount first.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on FLSmidth so far. With both risk flags and upside drivers on the table, move quickly, review the details, and weigh the 3 key rewards and 1 important warning sign.
Looking for more FLSmidth investment ideas?
If FLSmidth has caught your attention, do not stop here. Cast a wider net with focused screeners that surface other stocks matching the kind of edge you want.
- Target resilient performers with strong finances by scanning our list of solid balance sheet and fundamentals (203 results) that can handle tougher conditions without stretching their balance sheets.
- Hunt for mispriced opportunities using the 192 high quality undervalued stocks to see which companies combine solid fundamentals with pricing that may not fully reflect them.
- Build your watchlist around stability and sleep-better-at-night positions through the 231 resilient stocks with low risk scores that filters for lower risk profiles across key metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com