
Is Trend Micro (TSE:4704) Fully Priced As It Launches Its Japan Cyber Resilience Initiative?
Trend Micro (TSE:4704) is back in focus after launching the Japan Cyber Resilience Initiative, a ¥10 billion program of licensing credits and free services tied to its TrendAI Vision One cybersecurity platform.
Recent trading tells a mixed story. Trend Micro’s share price has eased in the last week, with a 7-day share price return of 6.58% and a 1-day move of 3.51% lower. However, the 30-day and 90-day share price returns of 7.25% and 11.38% point to building momentum after a softer patch that left the 1-year total shareholder return down 5.87%, compared with stronger 3-year and 5-year total shareholder returns of 46.20% and 35.99%.
Scan how Trend Micro’s AI security push compares with other hand-picked 55 AI infrastructure stocks already positioning for the next wave of cyber defense spending.
After a sharp near term pullback but solid multi year gains, Trend Micro now poses a simple question for anyone looking at the ticker: Does the current valuation still leave enough upside for the risk involved?
Most Popular Narrative: 10% Overvalued
Trend Micro last closed at ¥7,088, while the most followed narrative anchors fair value closer to ¥6,433. The gap comes down to whether the heavy AI and cloud spending can justify paying a premium today.
The main thing that has to go right is that elevated AI, cloud, and incubation costs, such as sovereignty zones, GPU transitions, Magna AI, and VicOne, translate into durable Vision One and Digital Life Protection ARR growth that supports the long term Road to 2028 margin ambitions.
The reaffirmed Road to 2028 targets for 8 to 10% net sales CAGR and 25 to 27% operating margins, despite a 54% decline in operating income in the second quarter of 2026 and lower full year profit guidance tied to AI and cloud costs, could leave Trend Micro’s valuation sensitive to any shortfall in revenue or margin outcomes relative to these ambitions.
See why 2 investors see Trend Micro as 10% overvalued.
Result: Fair Value of ¥6,433 (OVERVALUED)
Still, a faster recovery in Digital Life Protection subscriptions or a stronger mix shift into Vision One ARR could challenge the view that Trend Micro is overvalued.
Find out about the key risks to this Trend Micro narrative.
Another View: Trend Micro Through A Cash Flow Lens
The analyst narrative leans on earnings and a fair value of ¥6,433. Our DCF model tells a very different story. On that framework, Trend Micro at ¥7,088 trades at a steep discount to an estimated future cash flow value of ¥19,689.65. That gap raises a simple question for you: Which set of assumptions feels more realistic for the next decade of AI heavy spending and returns on that capital?
For anyone wanting to see how this cash flow view is built up step by step, Look into how the SWS DCF model arrives at its fair value..
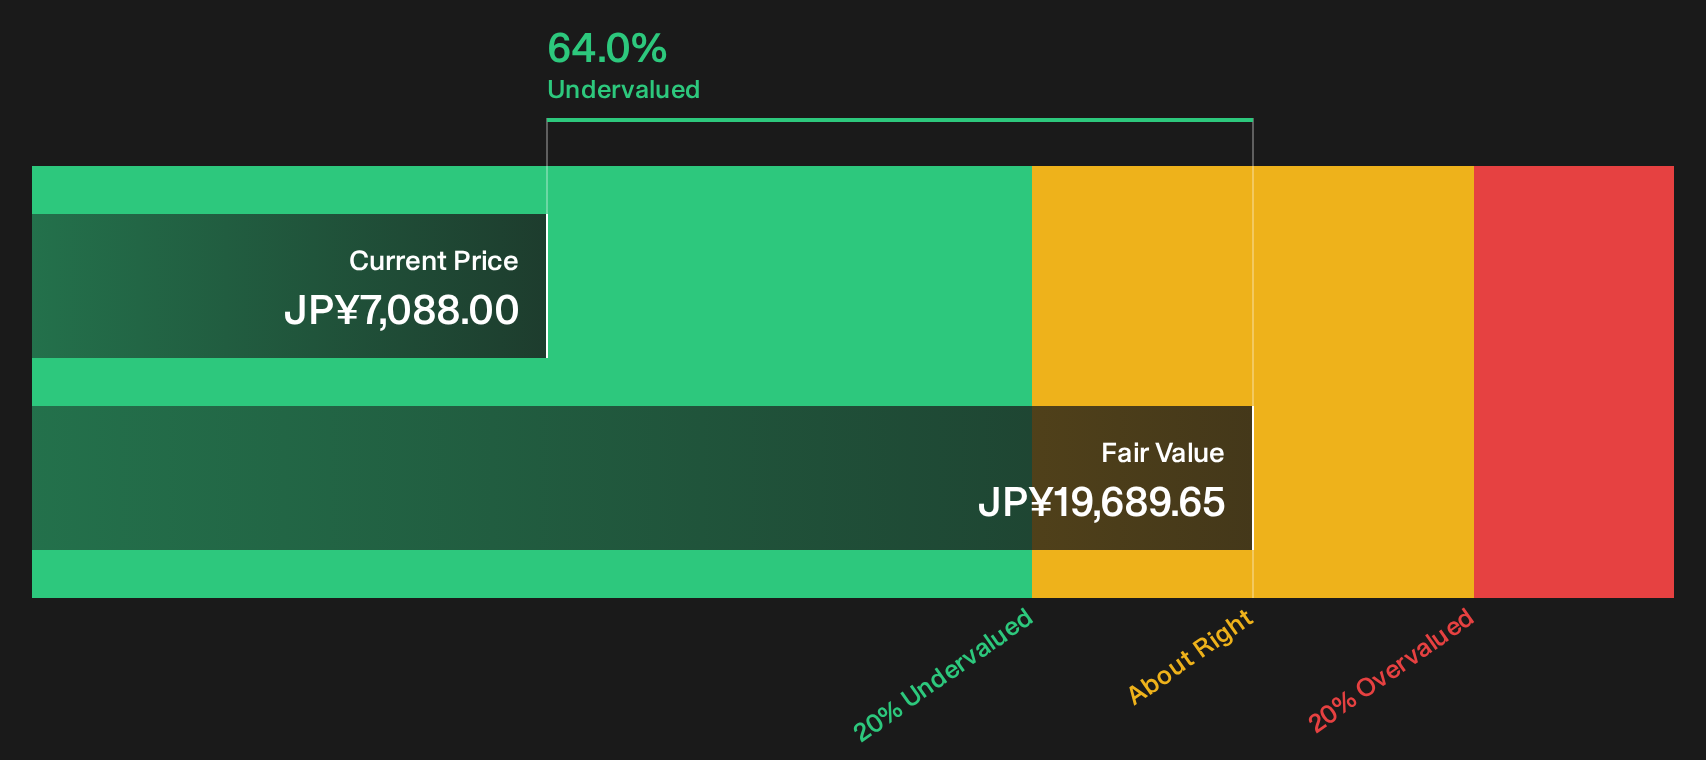
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Trend Micro for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Trend Micro’s valuation and growth story can pull you in both directions, so it may be useful to quickly review the underlying numbers, weigh the concerns and bright spots, then decide where you stand after checking the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Trend Micro?
If Trend Micro has you thinking harder about pricing risk and opportunity, do not stop there. Broader idea hunting can sharpen your next move.
- Target steadier potential returns by reviewing a 22 resilient stocks with low risk scores that screens for resilience when conditions change fast.
- Chase better value by scanning a 13 high quality undervalued stocks that highlights strong businesses trading below their estimated worth.
- Get early to potential future leaders through a 73 high quality undiscovered gems that focuses on quality companies yet to hit the spotlight.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com