
Why S Oil Doubters Were Wrong Before A 133% Gain
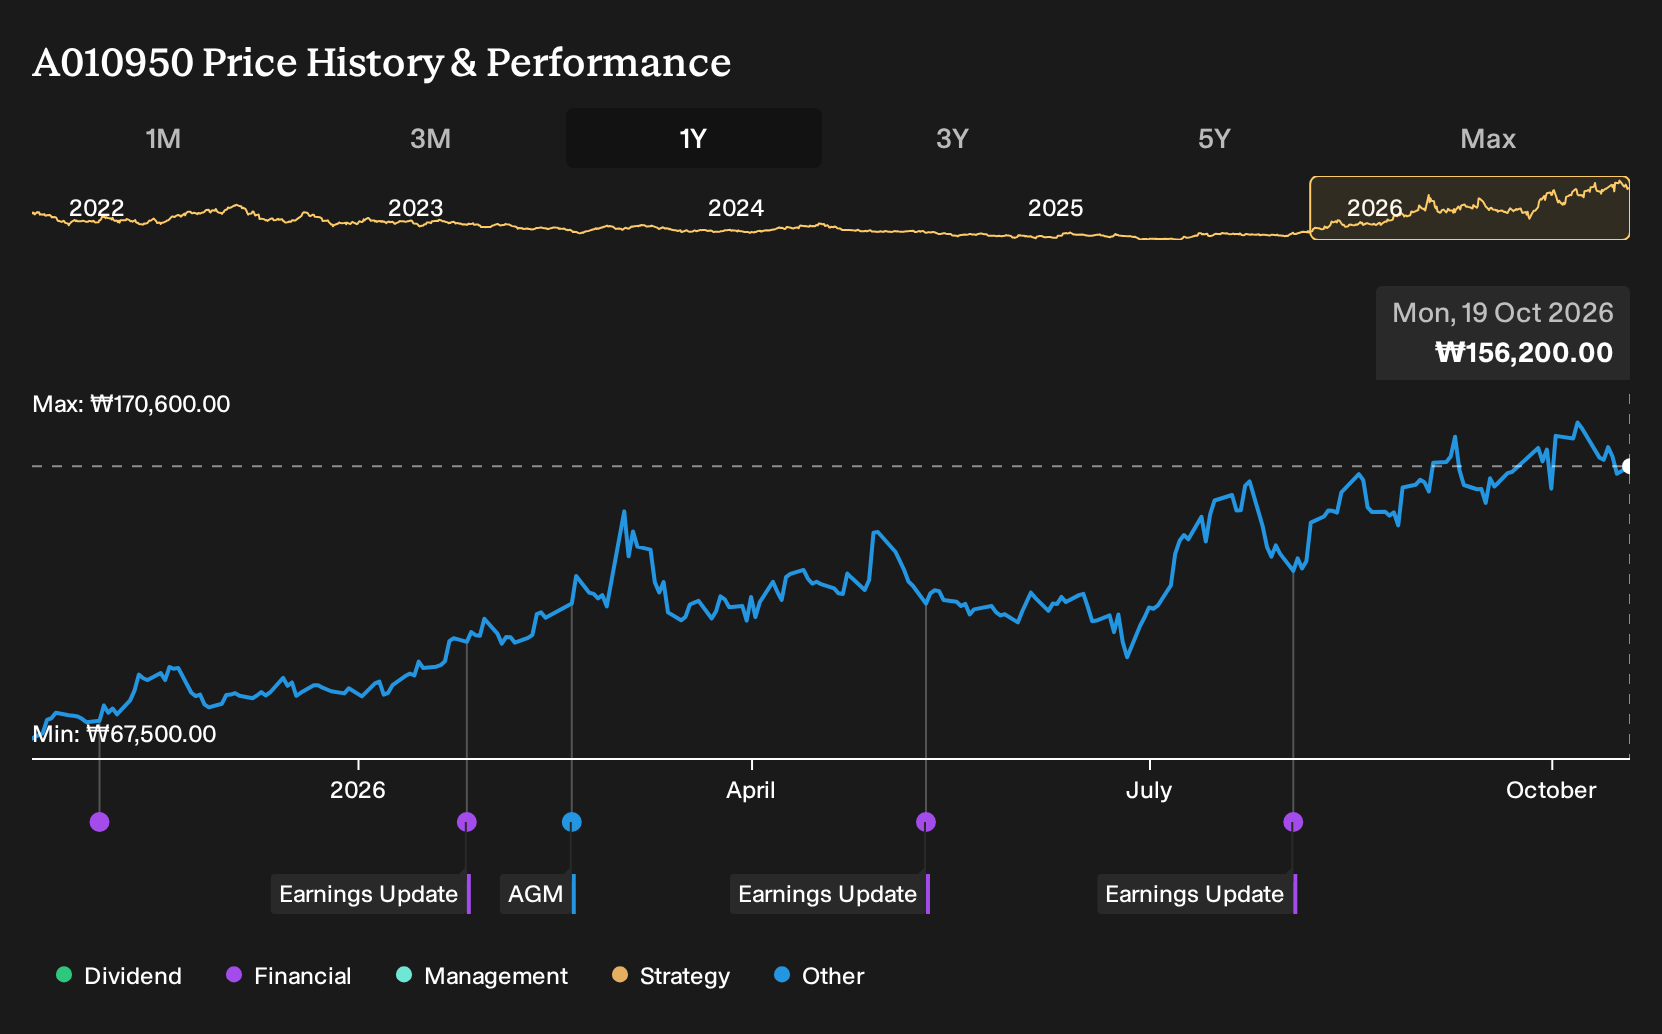
If S-Oil sat on your watchlist instead of in your portfolio, the outcome over the past year may feel like a missed call. For S-Oil shareholders, the return over the past year was 132.9%, including dividends. That move invites a tougher question. Back on 19 October 2025, could a focus on the Shaheen Project and expectations for tighter Southeast Asia fuel supply have helped you judge whether S-Oil’s export growth assumptions were realistic?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
If the move has made S-Oil harder to judge, start where the gap is still open and scan 192 high quality undervalued stocks.
The Two S-Oil Stories Investors Had To Weigh
The shares cost ₩65,200 at the start of the period, and anyone looking at S-Oil then had to decide which future felt more plausible.
The bullish narrative put fair value at ₩74,126, 14% above the start price, and leaned on the Shaheen Project staying on schedule and lifting high margin olefin and petrochemical capacity.
The bearish story pointed to a fair value of ₩52,000, 20% below the start price, and focused on rising carbon prices increasing costs for a fossil-fuel-heavy refiner.
What The Results Changed For The S-Oil Case
The clearest update came from S-Oil’s Q2 2026 figures. Revenue moved from ₩8,048,504m in Q2 2025 to ₩11,343,488m, while a loss of ₩66,782m turned into net income of ₩514,584m and net margin shifted from a decline of 0.8% to a positive 4.5%. That combination supported the optimistic export and margin story more than the cautious one.
The key lesson is simple. When a thesis leans on better profitability, track net margin and absolute profit in each report, and then judge whether those lines move in the direction the original narrative required.
What S-Oil’s Price Already Demands
Today S-Oil trades at ₩155,800. The selected Narrative’s Fair Value estimate sits below that level, which means this view sees more optimism in the market price than in its own model.
The Narrative leans on refining tightness, Shaheen and lube strength. You would need to judge whether refining margins and lube spreads can stay strong enough to cover petrochemical and policy pressure.
"The main thing that has to go right for S-Oil is that tight global refining capacity, the Shaheen petrochemical project and strong lube base oil spreads together generate enough durable earnings to offset regulatory, petrochemical margin and domestic fuel price-cap pressures."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
One Step Beyond S-Oil
S-Oil highlights how refining capacity and export routes shape fuel supply. You could also look at what happens before refineries ever get crude.
Someone has to move natural gas, liquids and oil reliably to buyers. One large operator focuses on long distance pipelines, storage caverns and marine terminals.
Its customers sign long contracts that can keep throughput and fees tied together. Power plants and data centers are already locking in future transport capacity.
As more demand looks for secure flows, that kind of toll road model may matter. The open question is how investors weigh construction risk against those contracted volumes.
One Narrative has already put a figure on it. → Uncover the company trading 16% below one Narrative's Fair Value
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com