
How Undervaluation Could Impact H World Group Stock Investors
- H World Group is drawing attention after a Discounted Cash Flow assessment suggested its intrinsic value sits well above the current share price, with digitalization efforts and the H Rewards ecosystem highlighted as central business drivers.
- The focus on direct digital channels and a more productive H Rewards membership base points to potential efficiency gains in customer acquisition and hotel utilization, which go beyond simple top line expectations.
- We will look at how H World Group's investment narrative is affected by the perceived undervaluation linked to its expanding digital and loyalty platforms.
Look beyond H World Group and compare its potential mispricing with a curated pool of 33 high quality undervalued stocks that also combine strong fundamentals with questioned market valuations.
H World Group Investment Narrative Recap
To own H World Group, an investor needs to believe the push into digital channels and H Rewards can offset softer RevPAR and heavy new supply. In the near term, the swing factor is whether direct booking growth and cost control keep earnings quality intact while the firm leans harder into an asset light mix.
The biggest risk is still overexpansion into lower tier cities in a weak demand patch, which could leave hotels underused and margins under strain. The latest DCF driven undervaluation debate does not change that operational risk. It mainly reframes how much patience an investor might have with execution.
The recent focus on H World Group’s intrinsic value is tied directly to its digitalization and loyalty efforts, since those initiatives underpin the cash flow assumptions used in the DCF work. Direct bookings through H Rewards matter here because lower customer acquisition costs can support profitability even if RevPAR pressure lingers.
DCF models are highly sensitive to long term cash flow forecasts. The key operational question is whether H World Group continues to convert its larger, more active member base into higher occupancy and steadier fee streams. If execution around hotel upgrades, brand mix, and city tier expansion stumbles, the current valuation gap could simply reflect those risks.
H World Group's analyst narrative points to CN¥31.5b in revenue and CN¥7.5b in earnings by 2029, based on a forecast annual revenue growth rate of 5.8%. This implies earnings would need to rise by CN¥2.5b from current earnings of CN¥5.0b to reach the consensus forecast.
Uncover why H World Group's fair value indicates a 32% potential upside to its current price that could narrow quickly.
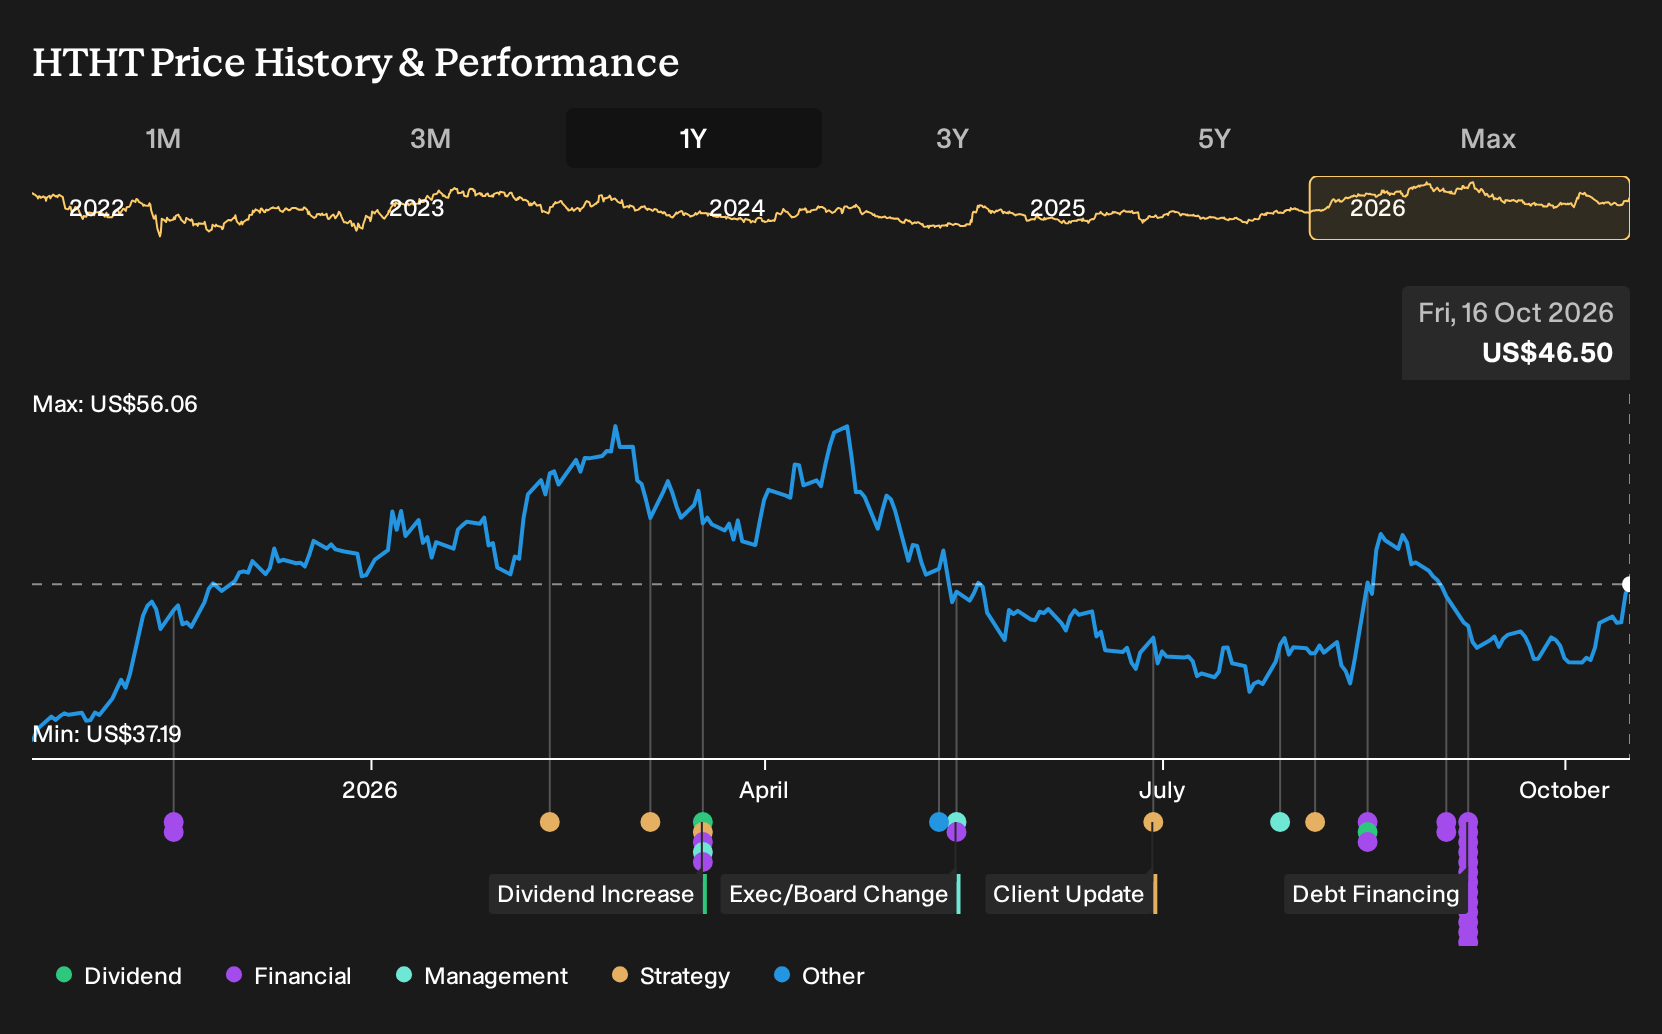
Exploring Other Perspectives
One alternate angle on H World Group puts far more weight on loyalty and brand churn than on the DCF debate. Bullish analysts were already pencilling in CN¥33.2b of revenue and CN¥8.0b of earnings by 2029, assuming stronger asset light fees and a powerful H Rewards flywheel. Those forecasts pre date this news, so you might see them shift as sentiment resets.
Explore another H World Group fair value estimate, including one that suggests potential upside of as much as 43% from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your H World Group research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for H World Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate H World Group's overall financial health at a glance.
Looking for more investment ideas beyond H World Group?
Once you have a view on H World Group, it can help to widen the lens and compare it with other opportunities that match your risk level, time horizon, and income needs. The Simply Wall St Screener gives you a structured way to do that across different styles and financial profiles.
- If you want potential upside without abandoning quality, scan through a curated pool of 20 high quality undiscovered gems that have strong fundamentals but limited market attention so far.
- For investors who care most about resilience and capital preservation, filter for 32 resilient stocks with low risk scores and see which businesses score well on stability and balance sheet strength.
- If rock solid finances are your starting point, build a watchlist from the list of solid balance sheet and fundamentals (25 results) and focus your research on companies with cleaner debt profiles and healthier cash positions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com