
Missed Corbion's Run? What Holders Had To Believe
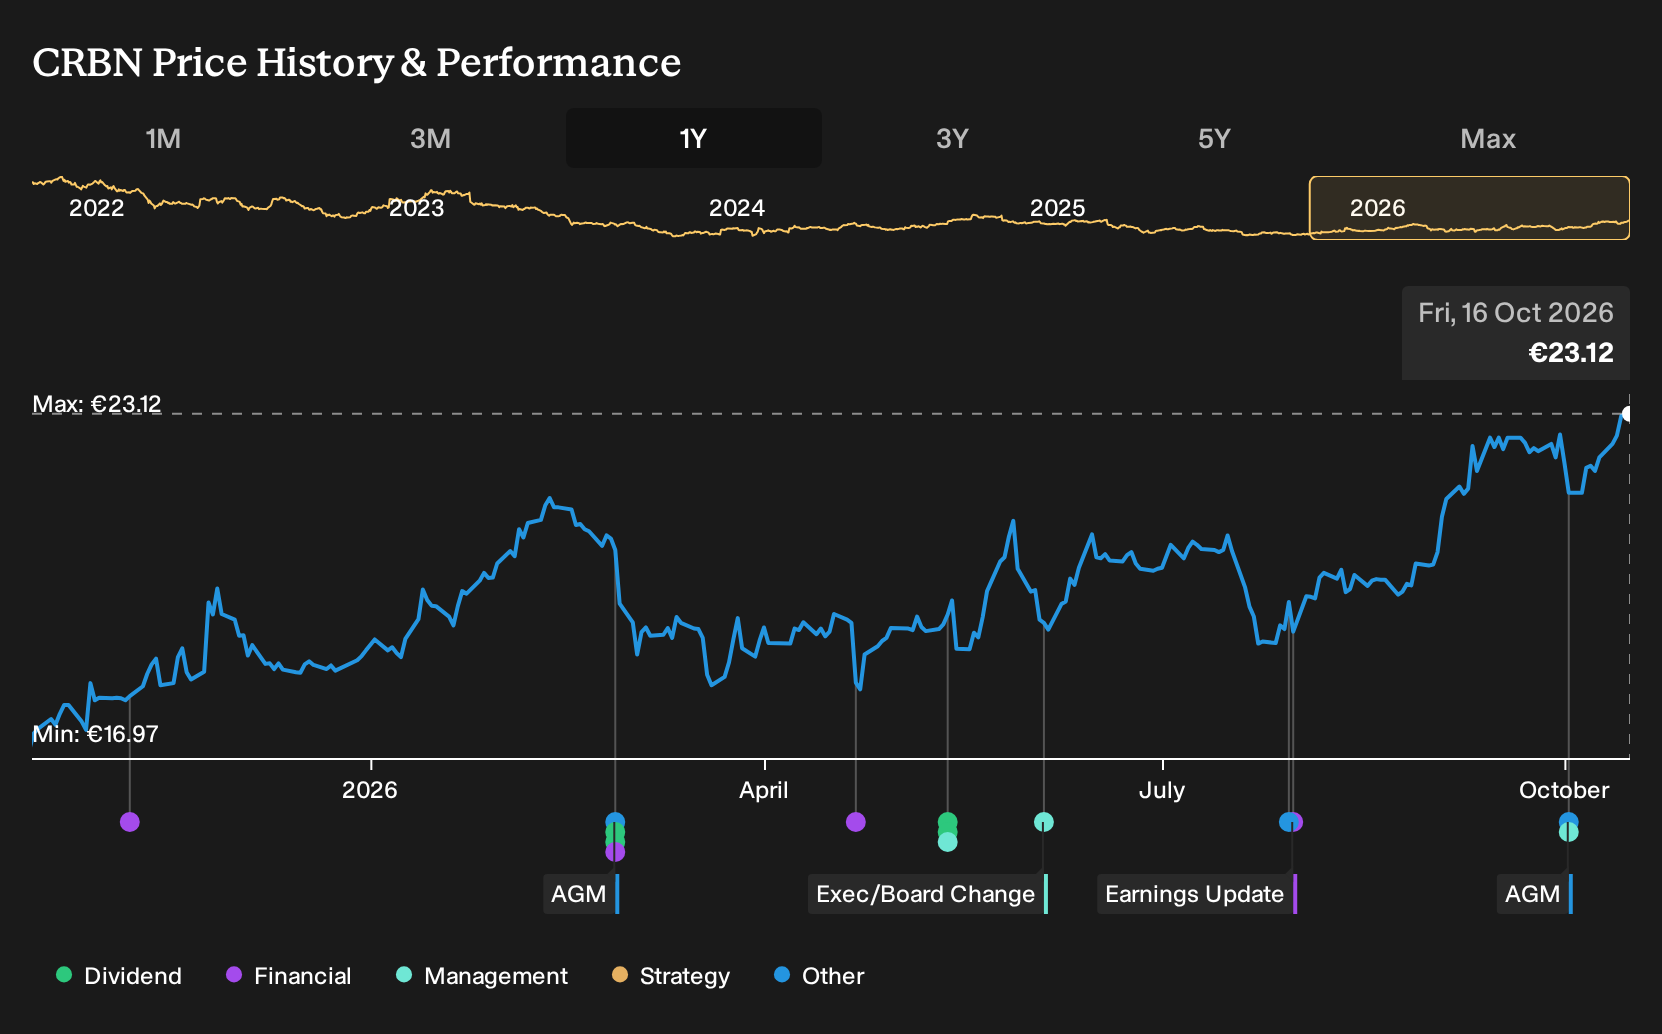
If Corbion was on your watchlist rather than in your portfolio over the last year, the result may sting a little. Investors who held Corbion over the past year are up 41.3%, including dividends. That outcome looks especially striking given Q1 2026 sales were lower than the prior year and H1 2026 net margin moved from 6.6% to 4.7%. If you rewound to October 2025, how confident would you have been that Thai plant ramp up and Chinese approvals would actually translate into better efficiency and earnings power?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind Corbion. Zero in on 192 high quality undervalued stocks for companies trading below our estimates.
The Two Corbion Stories Investors Had To Weigh
The shares cost €16.97 at the start of the period, and anyone looking at Corbion then had to choose between two very different stories about its future.
In the bullish Narrative, the Fair Value was €22.84, or 35% above the start price. Supporters focused on the Thai lactic acid plant ramp up and Chinese approvals for algae omega 3 as potential drivers of higher revenue and EBITDA margins.
The bearish view put Fair Value at €14, or 18% below the start price. That camp worried that rising regulatory and feedstock costs could lift operating expenses and compress margins across Corbion's core lactic acid, PLA and omega 3 lines.
What The Results Changed For Corbion
Corbion’s Q2 2026 update, with organic sales of €337.4m and adjusted EBITDA of €51.0m plus a refined margin outlook above 16%, gave the bullish efficiency story fresh support. The Q1 2026 sales dip to €293.7m and the move in H1 net margin from 6.6% to 4.7% pulled the other way, so the evidence cut both ways.
The key assumption was that Thai capacity, new approvals and cost savings would visibly support profitability. When you test a similar claim elsewhere, track reported EBITDA margin guidance and actual net margin together rather than relying on volume headlines.
What Today's Corbion Price Already Assumes
Corbion now trades at €23.12, and the selected Narrative’s Fair Value sits below that level. The focus has shifted firmly to contract terms, sulfuric acid exposure and the BRIGHT 2030 cost program rather than broad sector themes.
For today’s valuation to hold up, a buyer has to believe that higher value algae omega 3, lactic acid and Functional Ingredients & Solutions volumes consistently offset input cost pressure and keep EBITDA margins near current guidance.
"The numbers imply the share price already reflects successful delivery of mid to high teen EBITDA margins, ongoing free cash flow around the current guided €85 to €90 million range and a smooth exit from non core PLA exposure, leaving limited room for error if these goals are not met."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Before The Next Story Makes Headlines
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 46% below our estimate - accelerates higher grade ore feed while restoring low cost mining capacity.
- Company 2 - 24% below our estimate - adds sales headcount to win maintenance contracts and increase dense route coverage.
- Company 3 - 28% below our estimate - uses a single tech stack and AI tools to scale platform operations efficiency.
Three companies from the same screener. Open the full list of 203 financially solid companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com