
Cellebrite DI (CLBT) Gains AI Forensics Traction, Is It Still 28% Below Fair Value?
Recent coverage of Cellebrite DI (NasdaqGS:CLBT) has focused on its AI-driven digital forensics tools, as public agencies use the platform to handle complex device and cloud evidence in subscription-based deployments.
Cellebrite DI’s recent AI headlines are landing against a weak tape, with the share price at US$11.03 after declining 25% over the past 90 days and 38.2% year to date, while the 3 year total shareholder return of 60.3% shows earlier buyers are still ahead overall.
Spot opportunities alongside Cellebrite DI by scanning a curated set of AI-focused small caps with 38 AI small caps. These companies are also leaning heavily into data-driven platforms and recurring revenue models.Bulls point to Cellebrite DI’s AI strength and recurring contracts, while bears focus on the sharp share price slide and execution risk. The valuation now has to show which side currently has the stronger footing.
Most Popular Narrative: 28% Undervalued
The most followed narrative places Cellebrite DI’s fair value at about $15.36, above the recent $11.03 share price, which frames today’s weakness against a higher long run earnings path and a premium multiple.
The continued transition to a recurring, subscription-based revenue model with over 90% of revenues now from subscriptions and growing SaaS/cloud penetration improves revenue visibility, predictability, and operating leverage, which is already translating into higher EBITDA and free cash flow margins and is likely underappreciated in current valuations. Ongoing innovation in AI-powered analytics and automation, as well as the integration of strategic acquisitions like Corellium, is expected to increase Cellebrite's total addressable market, improve product differentiation, and support both revenue and margin expansion over the long term.
See why 20 investors see Cellebrite DI as 28% undervalued.
Result: Fair Value of $15.36 (UNDERVALUED)
Still, reliance on US federal contracts and ongoing regulatory scrutiny around digital evidence could disrupt Cellebrite DI’s growth plans and challenge the current undervalued narrative.
Find out about the key risks to this Cellebrite DI narrative.
Another Take On Cellebrite DI’s Valuation
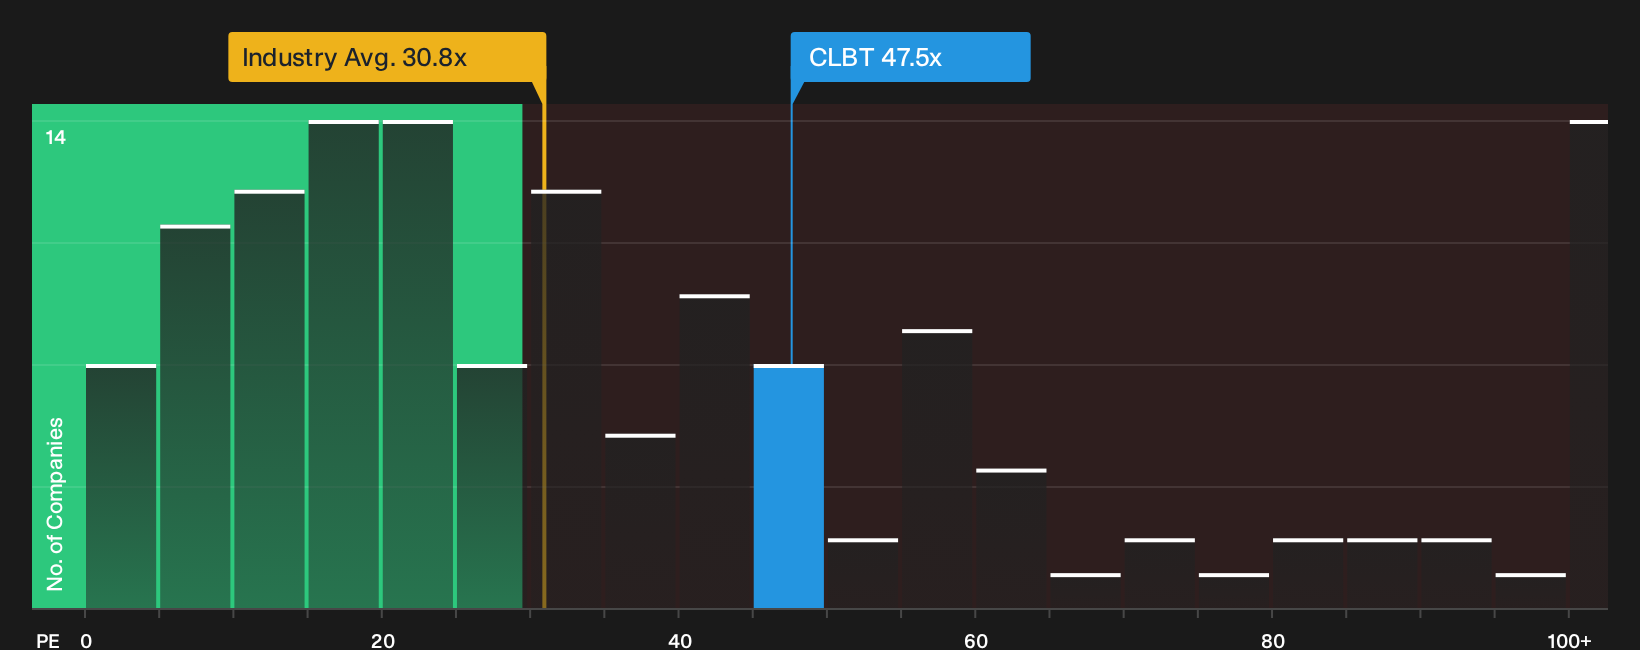
On one hand, Cellebrite DI screens as undervalued against the $15.36 fair value estimate and analyst targets. On the other, the current P/E of 47.5x is higher than the US Software sector at 30.8x and also above a 33.7x fair ratio, which points to heavier valuation risk. Which signal matters more for you?
To pressure test this richer earnings multiple against the underlying numbers and see how it compares with peers, take a closer look at the valuation breakdown with See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Cellebrite DI’s valuation and business momentum will not sort themselves out. Pull up the data, move quickly, and weigh the 4 key rewards and 2 important warning signs.
Looking for more ideas beyond Cellebrite DI?
Do not stop your research with Cellebrite DI. Cast a wider net across quality, yield, and resilience so you are not relying on a single story.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (25 results) that can better handle shocks and funding pressure.
- Hunt for value by reviewing a 33 high quality undervalued stocks where price and fundamentals still look out of sync.
- Stack potential income streams by focusing on a 8 dividend fortresses that prioritizes higher yields with sturdier cash flows.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com