
How Investors May Respond To Philip Morris International (PM) Dividend Hike
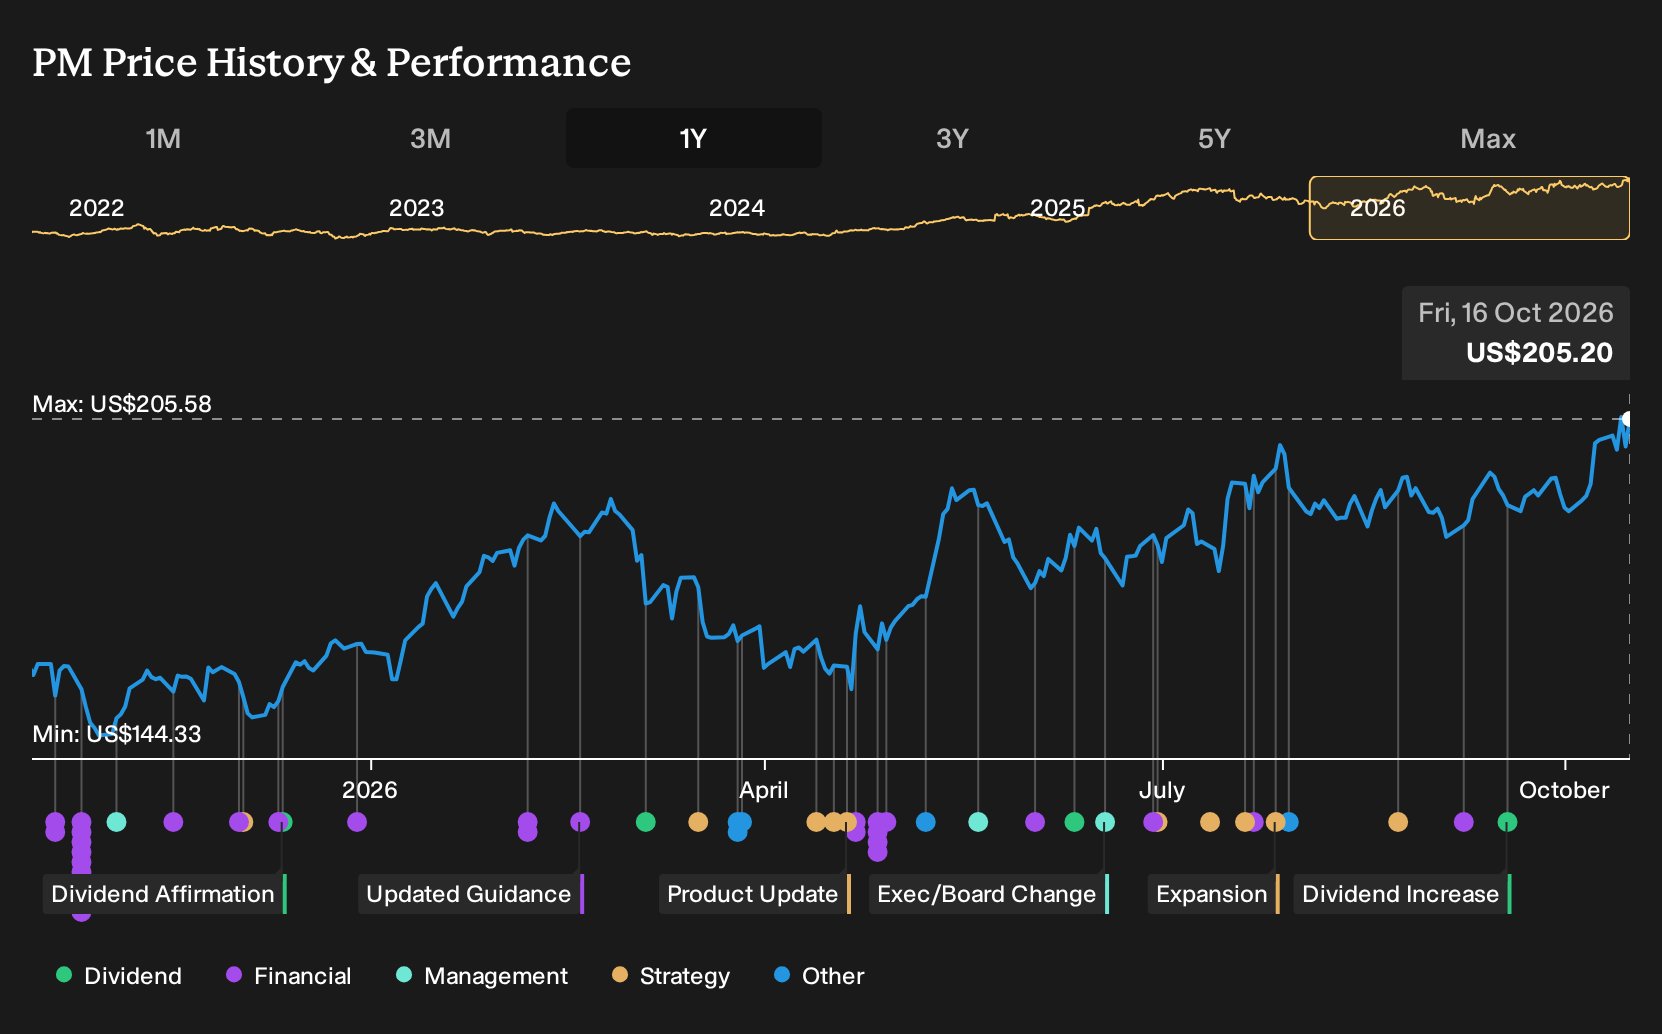
- Philip Morris International increased its quarterly dividend by 8.8% in September 2026 after reporting Q2 2026 revenue growth of 10%, supported by smoke free products.
- The combination of a higher cash payout and faster expansion in smoke free categories reflects how Philip Morris International is balancing income needs with its product transition.
- The focus now is on how Philip Morris International's investment narrative adapts to this 8.8% dividend rise and faster revenue momentum.
Scan how Philip Morris International's dividend move compares by lining it up against 8 dividend fortresses for ideas on other income-focused stocks with hefty yields.
Philip Morris International Investment Narrative Recap
To own Philip Morris International, you need to believe its shift toward smoke free products can offset a gradual decline in cigarettes while still funding a large dividend. The 8.8% dividend increase signals management’s confidence in current cash generation, but it does not change the core near term catalyst: execution on IQOS, ZYN and other reduced risk lines.
The biggest operational risk right now is that high U.S. spending on ZYN campaigns and IQOS ILUMA preparation erodes the roughly 70% smoke free gross margin advantage, so earnings growth from the transition comes through more slowly. The latest dividend step up does not remove that risk; it simply increases the importance of consistent cash flow delivery.
The most relevant recent development for this dividend move is the 10% Q2 2026 revenue growth, supported by smoke free categories such as IQOS, ZYN and VEEV. That top line performance, combined with H1 2026 combustible gross margin of 67.7% and pricing at 9.2%, gives Philip Morris International room to both invest in the transition and lift cash returns.
For you, the key question is whether that smoke free momentum and multi category model can continue to offset cigarette volume declines while servicing a high level of debt. Management is already well into a US$2b cost saving program, with more than US$1.8b delivered by mid 2026, so execution on efficiencies, leverage reduction and U.S. expansion will likely remain the main operational swing factors around the richer dividend.
What The Philip Morris International Dividend Hike Is Asking You To Believe
Philip Morris International's narrative projects US$49.8b revenue and US$15.4b earnings by 2029, based on analysts' assumption of 5.4% yearly revenue growth and an earnings increase of about US$4.6b from the current US$10.8b level.
Uncover why Philip Morris International's fair value is essentially aligned with its current price.
Exploring Other Perspectives
You might view the same Philip Morris International story through a different lens. The most optimistic analysts highlight ZYN as the swing factor, pointing to pre news forecasts of US$52.6b revenue and US$16.4b earnings by 2029. That is far above consensus, and the latest dividend hike could push these narratives to shift again.
Explore 4 other Philip Morris International fair value estimates, including one that suggests a potential 12% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Philip Morris International research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Philip Morris International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Philip Morris International's overall financial health at a glance.
Looking For More Investment Ideas Beyond Philip Morris International?
If the Philip Morris International story has sharpened your thinking about income, growth and balance sheet strength, it can help to line it up against a wider watchlist of stocks with different strengths.
- For investors who want potential mispricing with quality fundamentals, scan a curated set of 33 high quality undervalued stocks that may warrant a closer look.
- If capital preservation sits high on your priority list, focus on resilience first by filtering for 32 resilient stocks with low risk scores that score well on stability metrics.
- When you care as much about financial robustness as headline yield, start with a list of solid balance sheet and fundamentals (25 results) and see which candidates fit your income and risk profile.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com