
How Price Fixing Claims At Vail Resorts (MTN) Have Changed Its Investment Story
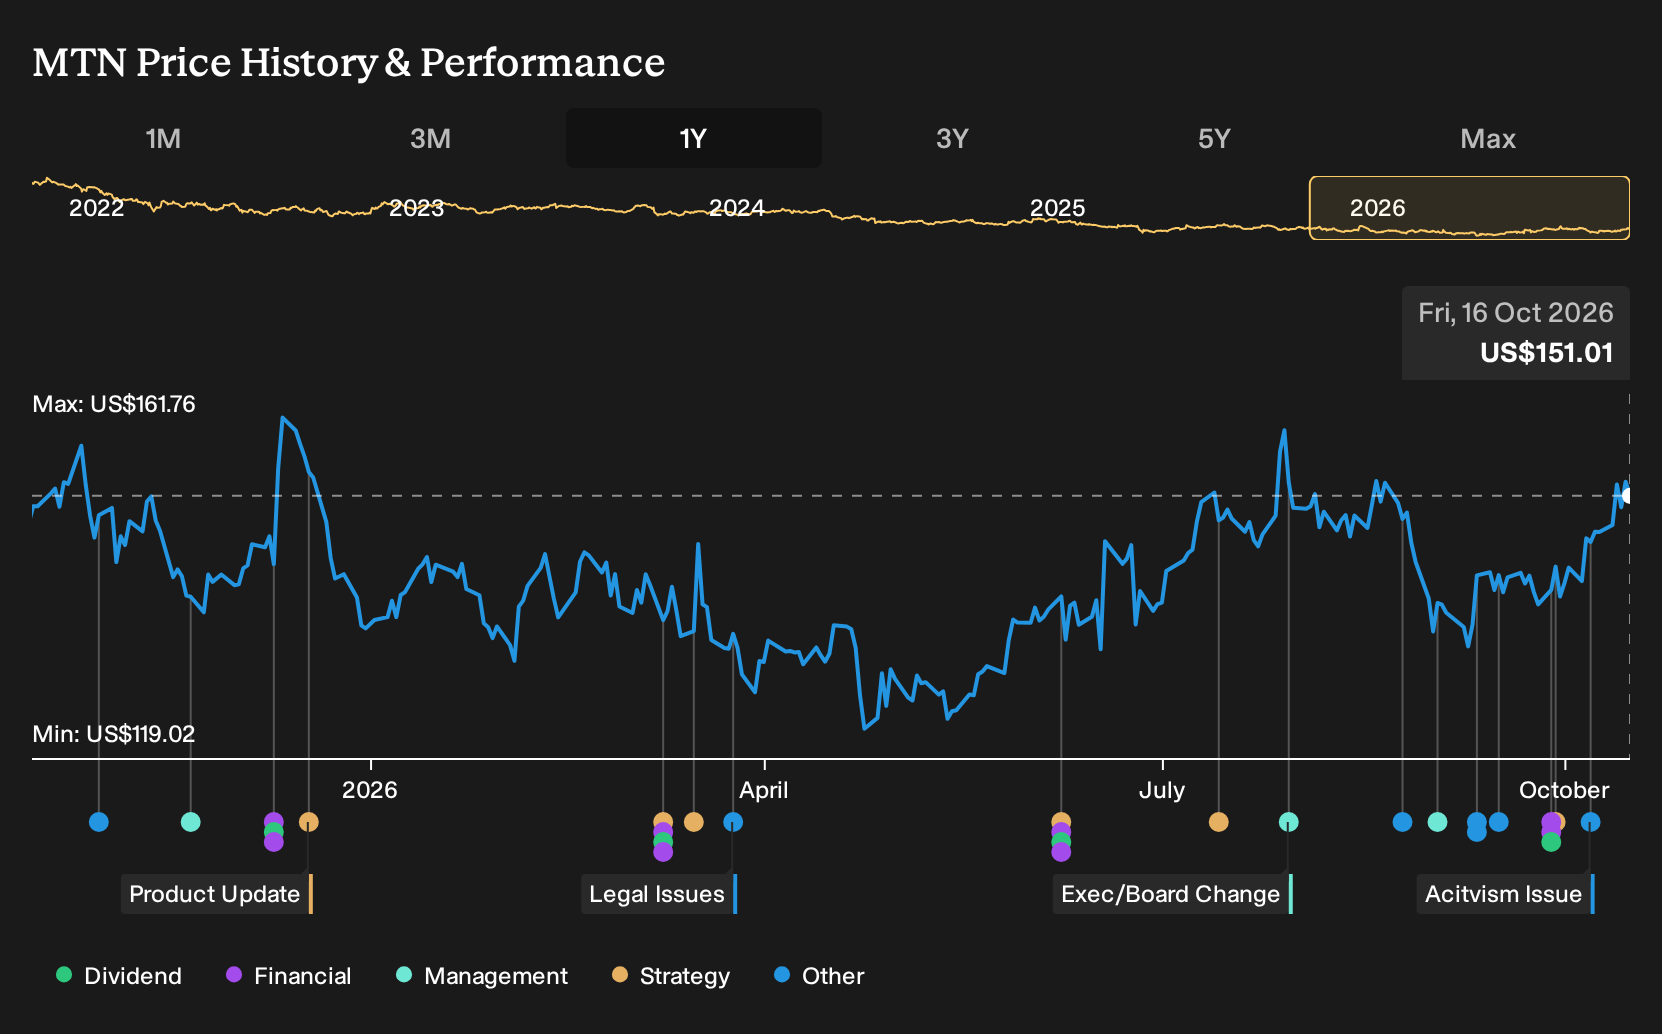
- On October 6, 2026, a Vail Resorts shareholder filed a derivative suit accusing executives and directors of permitting participation in a horizontal price fixing scheme with competitors, which allegedly exposed the business to antitrust litigation risk.
- The lawsuit points to potential pressure on Vail Resorts' cost structure and resource allocation, as management may need to devote cash, leadership attention and process changes to address antitrust exposure in addition to existing efficiency and guest-experience commitments.
- We will now look at how Vail Resorts' investment narrative could be affected by the alleged price fixing conduct flagged in this derivative suit.
Balance any concern around Vail Resorts' antitrust headlines by scanning a curated set of companies with stronger risk profiles through the 32 resilient stocks with low risk scores.
Vail Resorts Investment Narrative Recap
To own Vail Resorts, you need to believe the ski portfolio, Epic products and guest experience investments can keep earnings resilient through choppy snow seasons and changing skier habits. The antitrust derivative suit adds noise around governance and pricing practices but does not directly alter lift demand, weather exposure or foreign exchange headwinds driving the next few years.
The more immediate swing factors still look operational. Management is targeting efficiency savings while dealing with softer Epic pass units, later bookings risk and leverage near 3.9x EBITDA. Any extra legal costs or management distraction could make it harder to align costs with visitation or support the current dividend if conditions stay tough.
The new shareholder derivative suit is the clearest recent development linked to these themes. It focuses on alleged horizontal price fixing and argues that executives allowed behavior that increased antitrust litigation exposure. That concentrates attention on how Vail Resorts approaches pricing across Epic passes and lift tickets at a time when the model is already under scrutiny.
For investors, the link to catalysts is practical. Resource Efficiency Transformation Plan savings, product mix tweaks such as Epic Friend Tickets and the push through the My Epic app all rely on consistent pricing discipline and clear governance. Any regulatory or board reaction that alters discount structures, coordination with competitors or capital allocation could influence margins and how quickly those initiatives appear in financial results.
What The Antitrust Claims Mean For The Numbers
Vail Resorts' narrative projects US$3.2b revenue and US$269.9m earnings by 2029. This assumes 4.5% yearly revenue growth and an earnings increase of about US$122m from current earnings of US$147.5m.
Uncover why Vail Resorts' fair value indicates that Vail Resorts is roughly in line with its current price.
Exploring Other Perspectives
One alternate view says dividend risk matters more than the antitrust headlines. The most cautious analysts were already modeling only 3.3% annual revenue growth and earnings of about US$242.5 million by 2029. You can see how their more pessimistic story could shift again as the Vail Resorts governance fight unfolds.
Explore 2 other Vail Resorts fair value estimates, including one that suggests it could be worth just $148.36.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own with Vail Resorts.
- A great starting point for your Vail Resorts research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Vail Resorts. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vail Resorts' overall financial health at a glance.
Looking For More Investment Ideas Beyond Vail Resorts?
Once you have a view on Vail Resorts, it can help to compare that thesis with other opportunities that line up with your risk tolerance, income needs and balance sheet comfort level. The Simply Wall St Screener lets you scan for stocks that fit those preferences in a few clicks.
- If capital preservation sits high on your checklist, you can filter for companies that score well on stability and downside risk using the 32 resilient stocks with low risk scores.
- For readers looking for quality at a reasonable price, you can sort through businesses that pair stronger fundamentals with more modest valuations via the 33 high quality undervalued stocks.
- Income focused investors can narrow in on higher yielding candidates with robust payout profiles by checking the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com