
3 Dividend Stocks With Yields Over 3%
Rising global food inflation is squeezing household budgets, so dependable cash payouts from shares look more valuable than ever. Regular dividend income can help offset higher grocery bills and smooth out returns when markets feel choppy. This article focuses on large, reliable dividend payers yielding above 3% with solid coverage and steady track records. It highlights three of the most compelling stocks from this group that may be worth a closer look today.
The three stocks highlighted here offer a compelling starting point if you want exposure to companies with higher than 3% dividend yields that are well covered, growing and stable. However, if you want the absolute best, these 8 dividend aristocrats stocks are the cream of the crop.
Fulton Financial (FULT)
Overview: Fulton Financial is a regional US bank that collects deposits, makes consumer and commercial loans, and provides fee-based wealth management services that generate cash to support its dividend.
Operations: Fulton Financial generates about US$1.3b in banking revenue entirely from the United States, primarily through lending, deposits and related services.
Market Cap: US$4.3b
Fulton Financial fits the Dividend Powerhouses theme because its traditional lending and deposit franchise produces steady earnings that help fund a 3%+ payout, while fee income adds another layer of support for dividend coverage.
"Fulton Financial is progressing its acquisition led expansion in Philadelphia and Northern New Jersey, where the Blue Foundry deal has already added about US$1.6b of loans and US$1.5b of deposits. Management still expects cost saves to move the acquired quarterly expense base from about US$10.5 million to under US$7 million, which could support higher earnings as integration benefits are reflected."
What happens to margins and dividend headroom depends on how one unseen pressure on future funding costs ultimately resolves.
With that funding question hanging over future earnings, the full narrative for Fulton Financial lays out how Fulton Financial could balance dividend strength with acquisition driven growth potential.

Brown-Forman (BF.B)
Overview: Brown-Forman manufactures and sells Jack Daniel’s and a broad portfolio of premium spirits worldwide, generating steady cash flows that support its dividend.
Operations: Brown-Forman generates about US$3.9b in beverage alcohol consumer product revenue, with US$1.9b reported in the United States and the rest internationally.
Market Cap: US$13.3b
Brown-Forman matters for a 3%+ yield screen because the global whiskey and premium spirits portfolio creates recurring cash flow that can underpin regular dividends.
"Growth in ready to drink products like New Mix, el Jimador Spritz and Jack Daniel’s Tennessee Blackberry, which together are adding multi point value growth contributions in key markets, is creating a higher volume platform that can add to revenue while partially offsetting the impact of softer full strength spirits demand on operating income."
What happens to margins and dividend headroom depends on how one unseen pressure on future input costs and debt servicing ultimately resolves.
That pressure point is exactly where the full narrative for Brown-Forman shows how Brown-Forman could turn cost headwinds into accelerating dividend resilience and premium brand strength.

Hershey (HSY)
Overview: Hershey manufactures and sells chocolate, confectionery and salty snacks worldwide, using its household brands to support consistent dividend income.
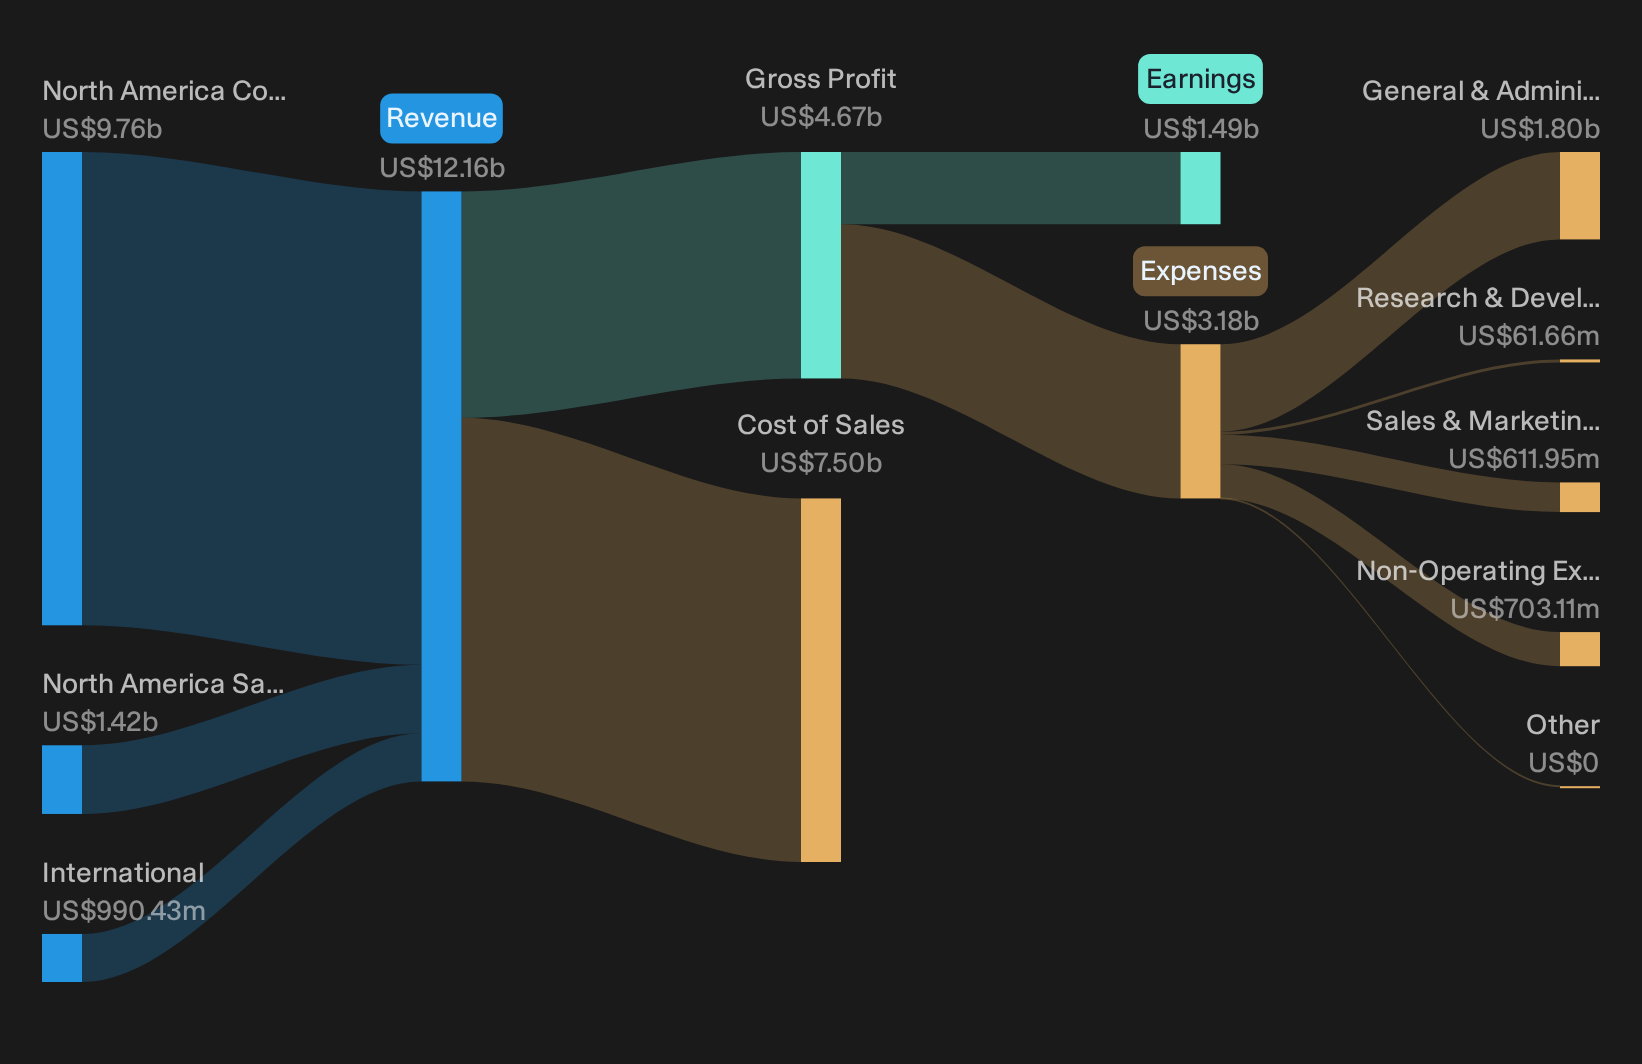
Operations: Hershey generates about US$9.8b from North America Confectionery, US$1.4b from North America Salty Snacks and US$1.0b from International markets, mostly in the United States.
Market Cap: US$34.3b
For income investors, Hershey matters because its familiar treats translate into steady cash flow that has supported a long history of regular, growing dividends.
"The forward thesis rests on three assumptions: that cocoa is structurally elevated but normalizing, allowing operating margin to recover toward a ~24% ceiling over the decade; that the One Hershey strategy extends the moat into salty, functional, and international adjacencies to sustain mid-single-digit (~3.5%) revenue growth."
What happens if a single cost pressure fails to ease could make a material difference to how secure that dividend stream feels.
If that cost pressure keeps biting, the full narrative for Hershey shows how Hershey could still turn cocoa volatility into accelerating cash generation and an overlooked income story.
Seeking Fresh Alternatives With Real Potential
Fresh opportunities move first. The strongest ideas gain momentum while the rest of the market is still looking back. Scan these curated lists before they are crowded and get in early.
- Target reliable cash generators by scanning a curated 8 dividend fortresses that focuses on companies aiming to keep payouts flowing while share prices are still catching up.
- Hunt for accelerating themes with a focused 55 AI infrastructure stocks featuring businesses positioned around the hardware and backbone that supports rising AI demand while it is still under the radar for now.
- Zero in on future materials demand through a refined 17 top copper producer stocks that highlights producers tied to long term electrification trends before momentum traders pile in.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com