
Shibuya (TSE:6340) Jumped, But What Is Behind The Fresh Attention?
Shibuya (TSE:6340) is back in focus after a U.S. federal court in Delaware entered final judgment in a patent infringement case, awarding Steuben Foods US$48.6 million including interest.
The legal setback occurred in a context where Shibuya’s share price has already moved sharply this year, with a 90-day share price return of 40.10% and a year-to-date gain of 68.60%. This far outpaces the recent 7-day dip of 1.69% and points to strong momentum backed by a 1-year total shareholder return of 75.04%.
Spot 22 resilient stocks with low risk scores that, like Shibuya after this court ruling, pair established operations with a focus on resilience when legal or operational shocks hit.After a 75.04% 1-year total return and a legal bill that is now quantified rather than hypothetical, is Shibuya still pricing in fresh upside, or has most of the rerating already happened before you even run the numbers?
Preferred P/E of 15.7x: Is it justified for Shibuya?
On current numbers, Shibuya trades on a P/E of 15.7x, which prices the stock above both its Machinery peers and the level suggested by fair value models built off fundamentals.
The P/E ratio compares the share price to earnings per share, so a higher multiple means investors are paying more today for each unit of profit. For a machinery manufacturer with established operations in packaging, mechatronics and agricultural equipment, that matters because earnings can be cyclical, and a rich valuation leaves less room for disappointment if results soften or legal costs bite.
Against its closest peers, Shibuya carries a premium. The P/E of 15.7x sits above the peer average of 13.8x and above the Japan Machinery industry average of 13x. This signals the market is willing to pay extra for this ticker. Compared to an estimated fair P/E of 14.5x, the current multiple is also higher, suggesting the valuation could compress if sentiment cools or if earnings do not track the expectations implied by this richer pricing.
Explore the SWS fair ratio for Shibuya.
Result: Price-to-earnings of 15.7x (OVERVALUED)
Still, the Delaware judgment and any further legal or operational surprises could undercut the premium P/E that Shibuya currently enjoys.
Find out about the key risks to this Shibuya narrative.
Another view on Shibuya's value
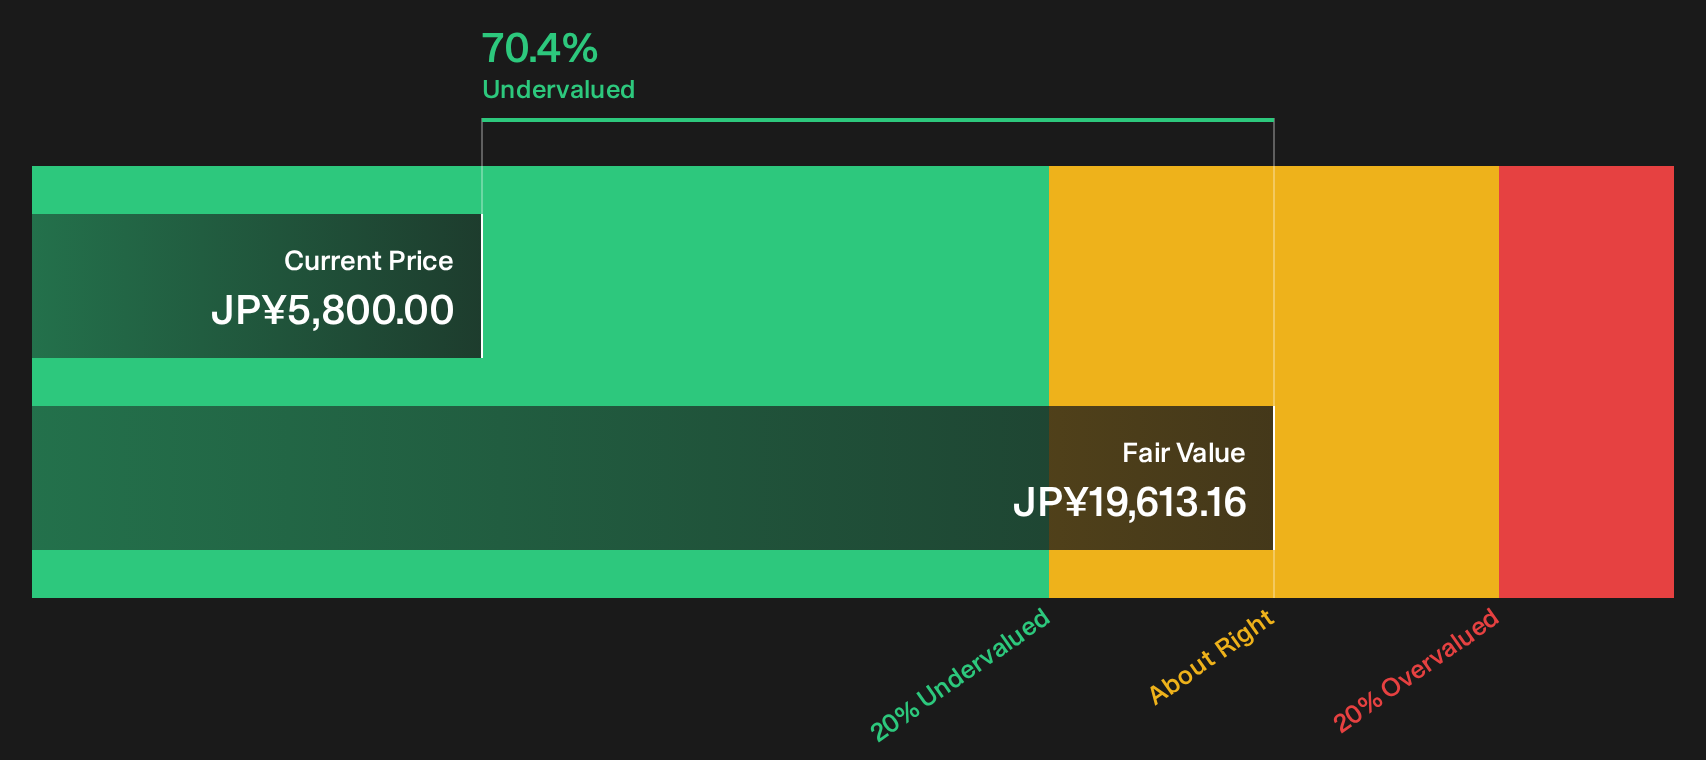
The SWS DCF model points in the opposite direction. On that framework, Shibuya at ¥5,800 screens as deeply undervalued compared with an estimated future cash flow value of ¥19,613.16. That is a wide gap. Is the market discounting legal and earnings risks too heavily, or is the model too generous?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Shibuya for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Shibuya's valuation and risk profile can make it hard to know which signal to trust, so move quickly, look through the underlying data, and then weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Shibuya?
Once you have a view on Shibuya, do not stop there. Broader context from other opportunities can sharpen your judgment and reveal potential uses of your capital.
- Look for steadier compounding by scanning companies with strong balance sheets and healthy fundamentals through the list of solid balance sheet and fundamentals (22 results).
- Explore potential pricing gaps where quality and valuation intersect by checking the 13 high quality undervalued stocks.
- Identify income ideas that aim to combine resilience with yield by reviewing the 29 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com