
Is Raised Revenue Outlook Altering The Investment Case For VF Corp (VFC)?
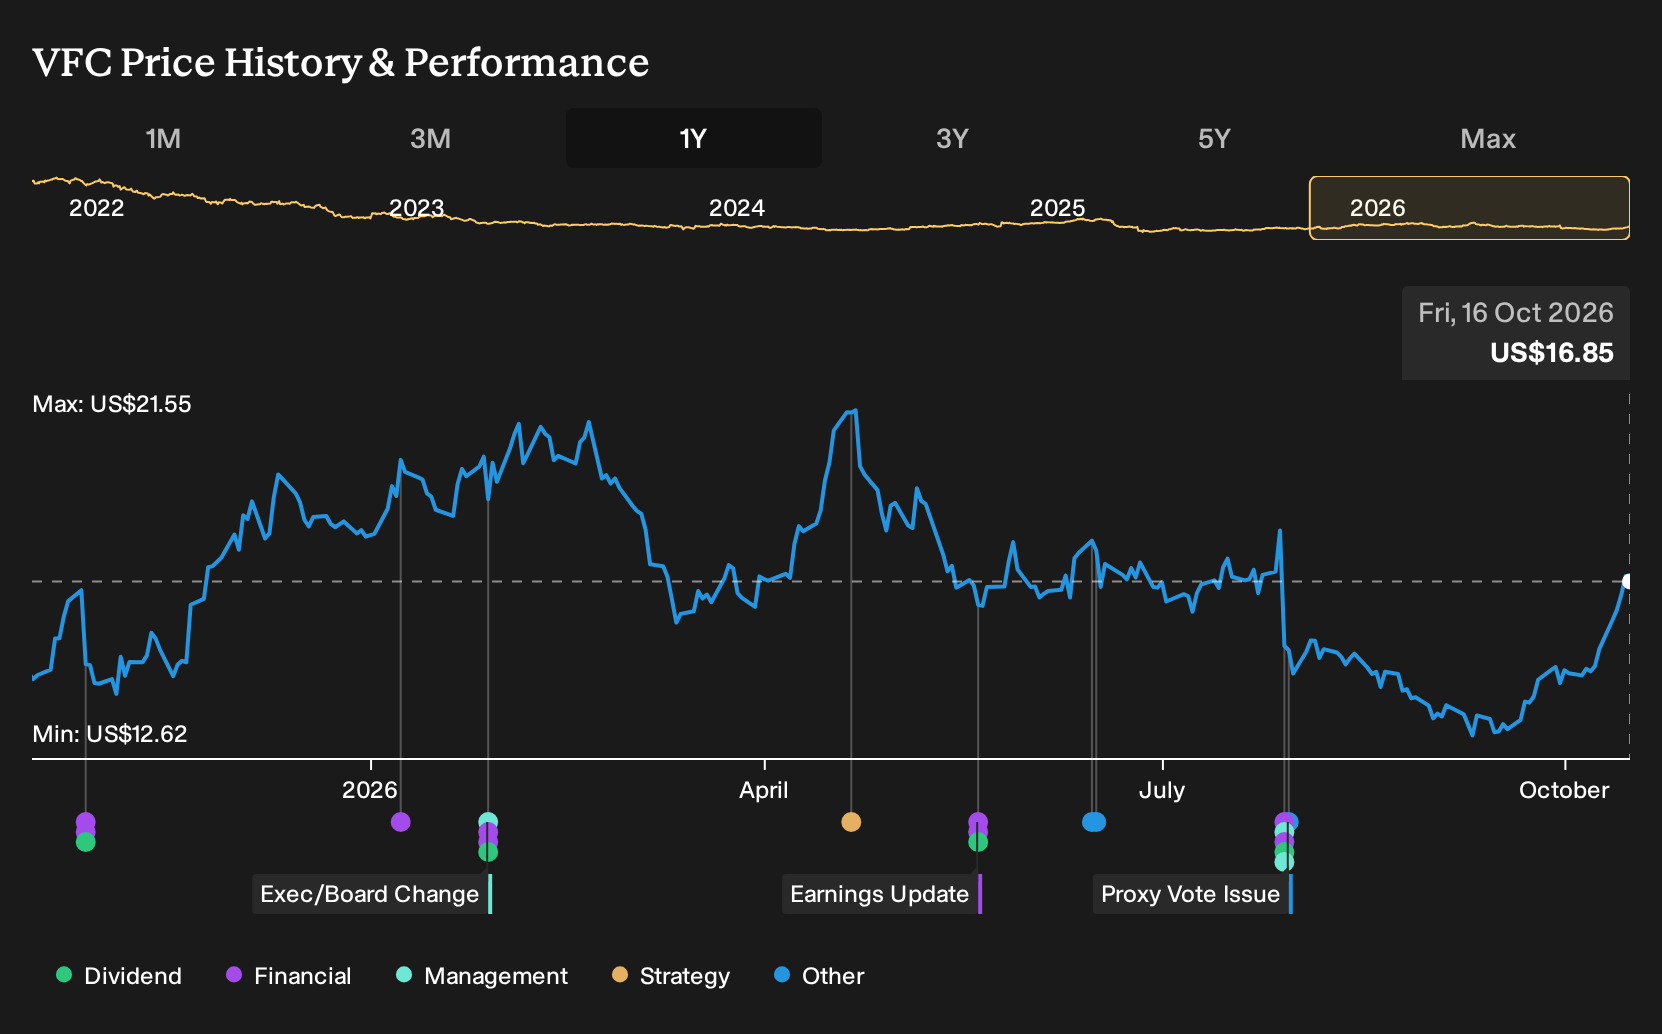
- VF Corp recently gained attention after management raised its revenue outlook, pointing to healthier demand trends at Vans, The North Face and Timberland, alongside tighter control of product, channels and inventory across the group.
- The shift in conversation around Vans from a pressure point to part of a more balanced brand mix highlights how VF Corp’s portfolio diversification could reduce reliance on any single label over time.
- We will look at how VF Corp’s investment narrative is affected by management’s higher revenue outlook and early signs of Vans stabilization.
V.F Investment Narrative Recap
To own V.F stock, belief needs to center on a cleanup story. The thesis is that Vans stabilizes, while The North Face and Timberland carry more weight, and that direct to consumer, portfolio pruning and tighter inventory keep margins from slipping. Management’s higher revenue outlook points to some traction, but the short term swing factor still looks like Vans consistency.
The biggest near term risk remains weak execution across the turnaround plan, especially if new product and marketing do not stick with consumers while tariffs, debt and wholesale caution hang over profits. The recent outlook upgrade helps sentiment, yet does not remove those operational and balance sheet pressures.
The most relevant recent development is V.F lifting its revenue outlook after seeing healthier demand at Vans, The North Face and Timberland and better control over product, channels and inventory. That kind of guidance change gives investors a concrete checkpoint for whether the reset around higher margin channels and cleaner stock is working.
For catalysts, that outlook now becomes a reference point. Delivery against it would support the argument that earnings, which analysts already expect to grow strongly over the next few years, are being backed by real operating progress. Falling short would bring the focus straight back to Vans brand health, tariff costs, leverage and the ability to sustain any improvement.
V.F's narrative projects US$10.3b revenue and US$724.7m earnings by 2029. This assumes 2.6% yearly revenue growth and an earnings increase of about US$450.5m from the current US$274.2m level.
Discover why V.F's fair value indicates an 11% potential upside to its current price, a discount that could narrow quickly as sentiment improves.
Exploring Other Perspectives
One alternate view leans hard on the risk that Vans never really recovers. That bearish group expected V.F revenue around US$9.3b and earnings of roughly US$398.3m by 2029, far below the US$724.7m consensus. Those lower forecasts reflect a much more cautious Vans narrative that may get revisited after this outlook upgrade.
Explore 2 other V.F fair value estimates, including one that suggests it could be worth just $18.77.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your V.F research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for V.F. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake. This makes it easy to evaluate V.F's overall financial health at a glance.
Looking For More Investment Ideas Beyond V.F?
If the V.F story has you thinking about where turnarounds or steadier compounders might show up next, the Simply Wall St Screener can help you move from one ticker to a broader watchlist built around clear financial traits.
- For investors who want quality at a discount, start with a curated pool of companies trading on appealing fundamentals using the 33 high quality undervalued stocks.
- If capital preservation matters as much as upside, filter for businesses with more resilient profiles and lower risk scores through the 32 resilient stocks with low risk scores.
- When balance sheet strength is the priority, focus on companies with solid financial footing and robust fundamentals by scanning the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com