
NP3 Fastigheter (OM:NP3) Lifts Earnings And Expands Portfolio, Is The Discount Enough?
NP3 Fastigheter (OM:NP3) has landed in focus after its third quarter 2026 report, which combined higher sales, a one off gain, and fresh property acquisitions with lingering concerns around refinancing costs and leverage.
The fresh earnings and acquisition headlines have arrived against a mixed tape for NP3 Fastigheter. The latest SEK227.5 share price comes after a 1 day share price return of 2.71% and a 7 day share price return of 4.36%. However, the 30 day share price return declined 5.99% and the year to date share price return fell 10.96%, while the 1 year total shareholder return is down 13.06% and the 3 year total shareholder return is up 64.69%. This suggests that shorter term momentum has cooled even as longer term holders still sit on sizeable gains.
Scan beyond NP3 Fastigheter and compare this refinancing story with other property owners facing similar pressure on debt costs using our hand picked list of solid balance sheet and fundamentals (203 results).
Stronger recent earnings, fresh properties in the portfolio and a share price that has lost ground this year put NP3 Fastigheter at an awkward crossroads. Does that mix still tilt the risk reward in favour of new buyers or not?
Price-to-Earnings of 8.9x: Is it justified?
On the latest numbers, NP3 Fastigheter trades on a P/E of 8.9x, which sits below both peer averages and some internal fair value markers, while the share price sits at SEK227.5.
The P/E ratio compares what investors pay for each unit of current earnings. For a property owner like NP3 Fastigheter, this metric often reflects how the market weighs recurring rental income, refinancing risk and the quality of reported profit.
Here, the stock screens as good value compared to both its direct peers on 15.1x and the wider Swedish real estate group on 10.6x. It also sits slightly below an estimated fair P/E of 9.1x, which indicates the current valuation could still move closer to that level if the market grows more comfortable with NP3 Fastigheter's earnings profile.
Explore the SWS fair ratio for NP3 Fastigheter.
Result: Price-to-Earnings of 8.9x (UNDERVALUED)
Still, NP3 Fastigheter faces clear risks if refinancing costs stay elevated or if weaker rental demand pressures its SEK2,453m rental income base.
Find out about the key risks to this NP3 Fastigheter narrative.
Another view of NP3 Fastigheter’s value
The P/E points to NP3 Fastigheter being attractively priced, yet our DCF model paints a similar but more conservative picture. On that framework, SEK227.5 compares with an estimated future cash flow value of SEK277.95, which implies the shares trade about 18% below that mark. Does that gap reflect risk or potential mispricing in your view?
Look into how the SWS DCF model arrives at its fair value.
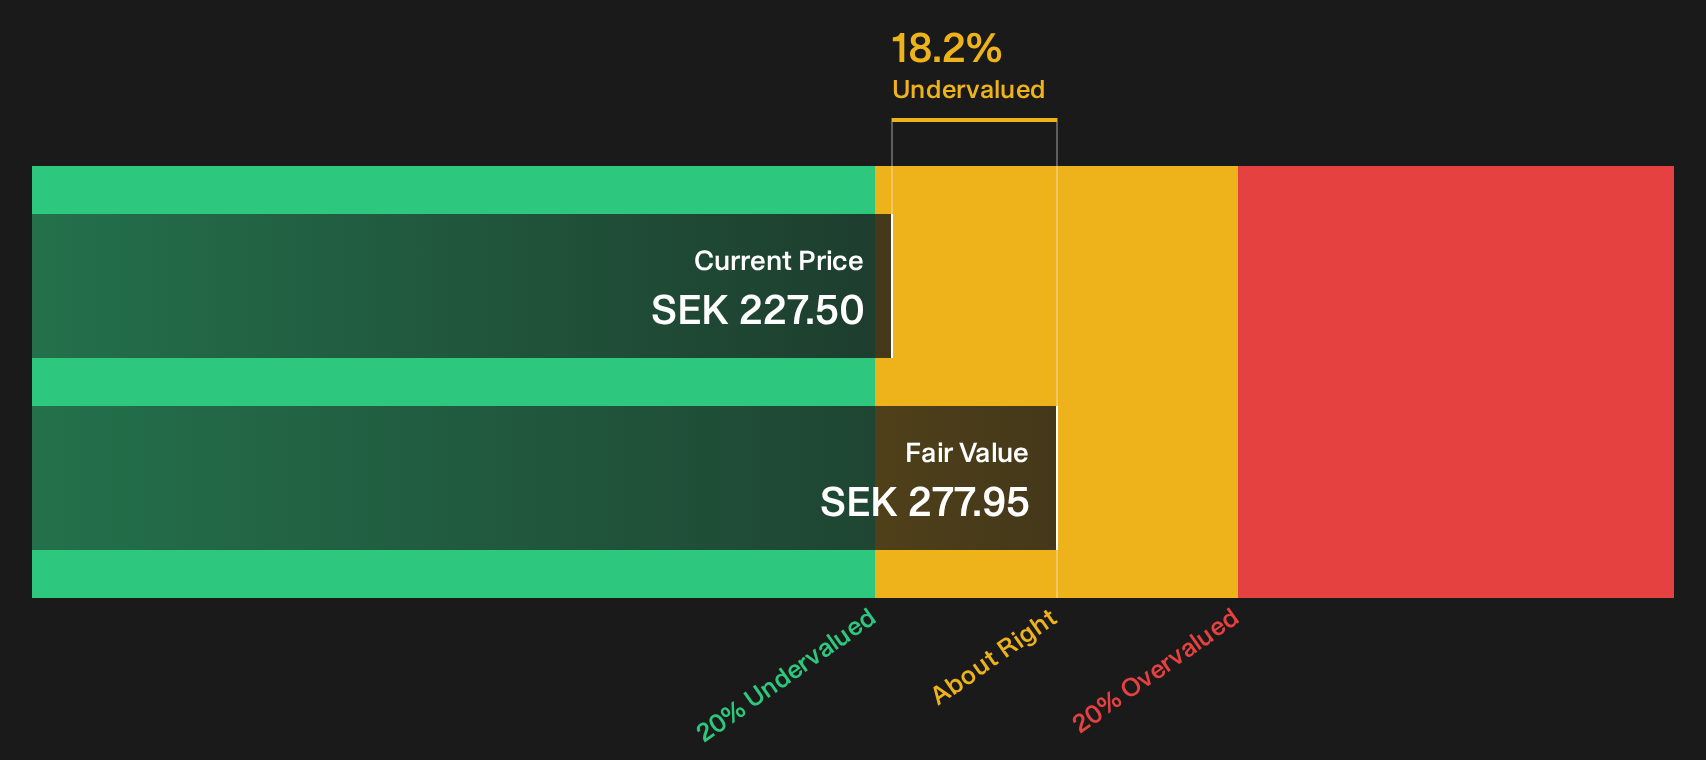
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out NP3 Fastigheter for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around NP3 Fastigheter can easily sway opinion in either direction. Check the underlying data now and decide where you stand by weighing its 4 key rewards and 4 important warning signs.
Looking for more investment ideas beyond NP3 Fastigheter?
If NP3 Fastigheter has sharpened your focus on value and risk, you can use that same mindset to look for other opportunities before the crowd gets there.
- Target potential mispricing by scanning a 195 high quality undervalued stocks that filters for strong fundamentals backed by healthy cash flows.
- Strengthen income potential with a 216 dividend fortresses that highlights companies pairing higher yields with resilient payout histories.
- Dial down portfolio stress by reviewing a 231 resilient stocks with low risk scores built around resilient balance sheets and lower risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com