
How Investors Are Reacting To Nissan (TSE:7201) AI Vehicle Software Partnership
- Applied Intuition announced that it is deploying its AI-powered Vehicle OS and software-development tools with Nissan Motor to support a scalable, open in-vehicle software platform across multiple powertrains.
- This deeper software partnership gives Nissan Motor external support to modernize its in-house engineering workflows, which could influence development speed, complexity management and long term product economics for AI-defined vehicles.
- The focus now turns to how Nissan Motor's AI-defined vehicle initiatives with Applied Intuition could influence the broader investment narrative.
Scan how Nissan Motor's AI-defined vehicle push compares with other potential beneficiaries of the same trend by zeroing in on 55 AI infrastructure stocks in your research short list.
Nissan Motor Investment Narrative Recap
Nissan Motor still appeals to investors who believe the turnaround story is about fixing costs and raising earnings quality through electrified and software defined vehicles. The Applied Intuition deal mostly supports that longer term thesis rather than shifting the near term picture. In the short term, the key catalyst remains progress on the Re Nissan savings and evidence that cash generation can hold up.
The biggest risk stays the same. Pressure in China, tariff and logistics costs and execution risk around plant consolidation can all offset efficiency wins. This new AI software partnership does not remove those issues, so position sizing and patience matter if you are watching this stock closely.
The Applied Intuition announcement connects directly to the earlier push Nissan Motor made around electrified and software focused models such as Leaf, e POWER variants and N series NEVs. The idea is simple: a more unified Vehicle OS and development toolkit can support that product roadmap and potentially make over the air feature updates and complexity management easier.
For catalysts, this matters only if it feeds back into margins and free cash flow alongside the Re Nissan cost reset. Execution risk sits in integrating external tools with legacy platforms while the group is restructuring plants and managing tariff headwinds. That mix keeps operational delivery more important than any single AI headline.
Nissan Motor's current analyst narrative points to revenues of ¥13.4b and earnings of ¥191.3b by 2029, based on a 3.1% yearly revenue growth assumption. This would mean earnings today, which show a loss of ¥413.6b, would need an earnings increase of about ¥605b to reach the 2029 consensus figure.
Uncover why Nissan Motor's fair value indicates a 37% potential upside to its current price that could narrow quickly.
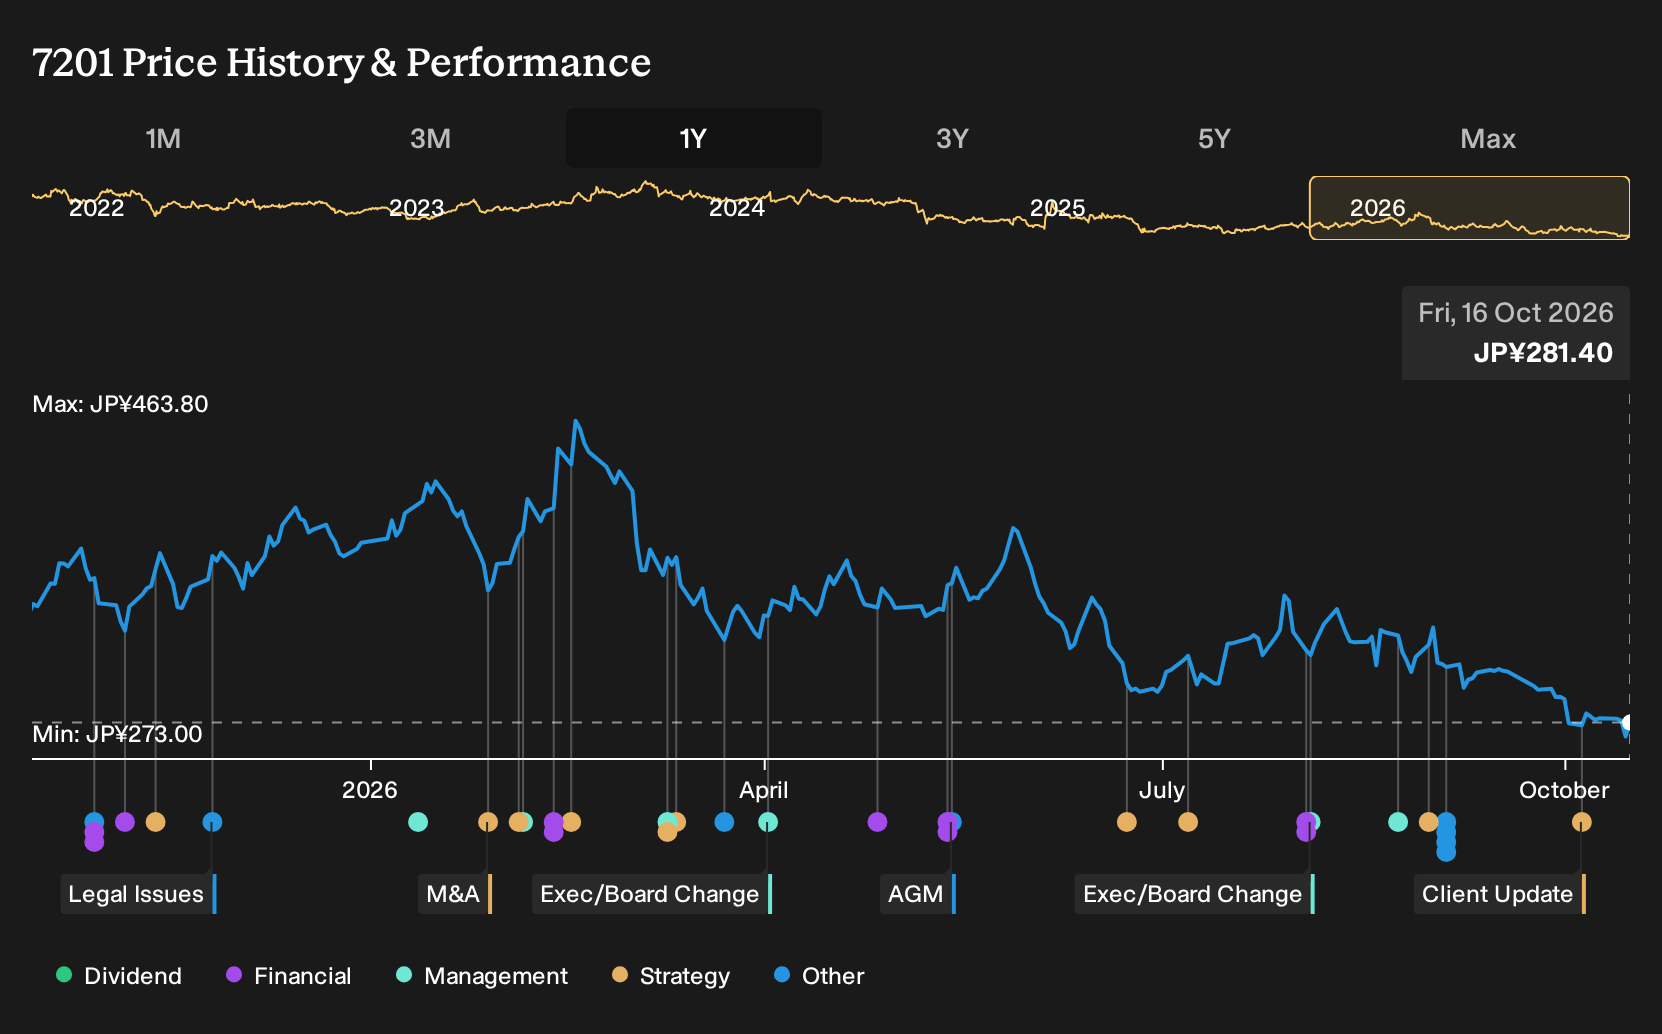
Exploring Other Perspectives
You see a very different angle if you focus on tariff and logistics pressure instead of cost savings. The most bearish Nissan Motor analysts were only looking for ¥12,401.6b of revenue and about ¥141.2b of earnings by 2029 before this news. That is a far more cautious story, and the new AI partnership could eventually push those expectations in either direction.
Explore 4 other Nissan Motor fair value estimates, including one that suggests it could be worth just ¥285.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Nissan Motor research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Nissan Motor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nissan Motor's overall financial health at a glance.
Looking For More Nissan Motor Investment Ideas?
If the Nissan Motor story has you thinking more broadly about where to put fresh capital to work, it can help to line it up against a wider field of opportunities using the Simply Wall St Screener.
- For readers who want potential value combined with quality fundamentals, compare Nissan Motor against a basket of 13 high quality undervalued stocks that share stronger balance sheets and cash generation profiles.
- If your priority is resilience and you care more about durability than excitement, weigh Nissan Motor alongside a curated 22 resilient stocks with low risk scores that aim to keep business risk contained.
- For investors hunting for less crowded ideas with solid underlying metrics, broaden your watchlist beyond Nissan Motor by scanning a 73 high quality undiscovered gems that often receive less day to day attention from the market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com