
Gilead Sciences (GILD) Could Be 22% Overvalued On Fresh Drug Approvals
Fresh regulatory decisions have put Gilead Sciences (GILD) back in focus for investors, following approvals for HIV therapy Bixlenvo, an expanded Trodelvy cancer indication, and Hepcludex in hepatitis delta.
Those approvals have landed during a period of strong momentum for Gilead Sciences, with the share price gaining 19.9% over 90 days and 28.5% year to date, while long-term total shareholder return of 175.8% over five years shows the impact of compounding.
Spot opportunities beyond Gilead Sciences by scanning a hand picked 33 healthcare AI stocks that tap into similar healthcare breakthroughs and regulatory catalysts.Gilead Sciences now trades close to its recent highs after a sharp run driven by fresh approvals. The next consideration is whether the current valuation already reflects that progress or still leaves room for a better entry at a later time.
Most Popular Narrative: 21.7% Overvalued
The most followed narrative on Gilead Sciences puts fair value at $128.38, compared with a last close of $156.19, so it frames the recent rally as moving ahead of that estimate.
Gilead is transitioning from a “single-franchise HIV company” into a multi-platform biopharma with high-probability growth drivers in lenacapavir and Trodelvy, as well as high-upside optionality in cell therapy and immunology. Temporary earnings headwinds from acquisition-related charges and integration work are obscuring what could be a stronger medium-term earnings profile once the current investment phase normalizes.
See why 19 investors see Gilead Sciences as 22% overvalued.
Result: Fair Value of $128.38 (OVERVALUED)
Still, this storyline for Gilead Sciences could be knocked off course if key late stage trials disappoint or if recent acquisitions create harder than expected integration drag.
Find out about the key risks to this Gilead Sciences narrative.
Another View: Cash Flow Signals A Different Story
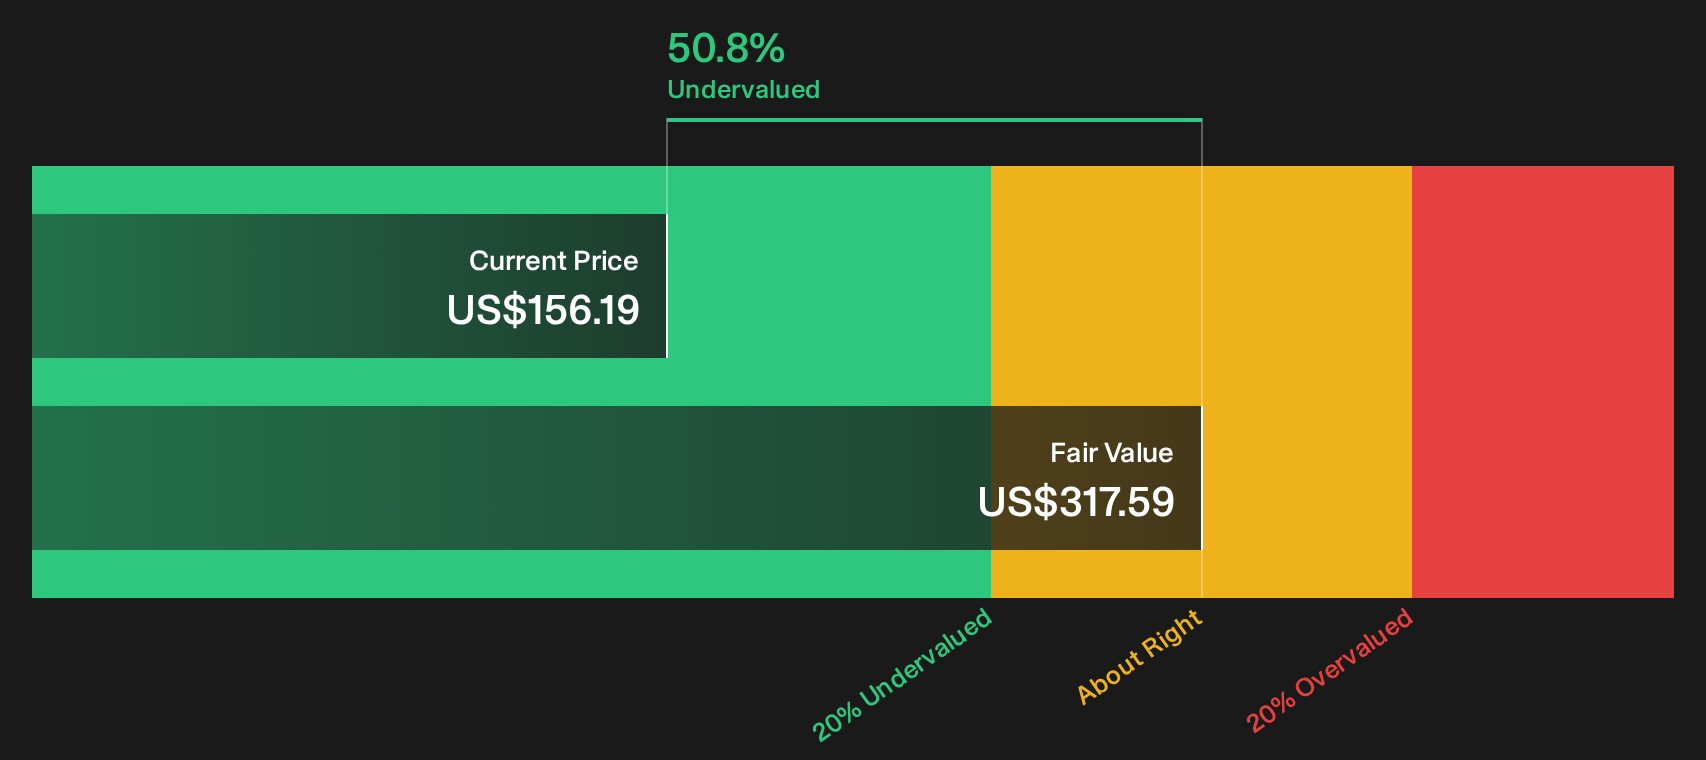
The popular Gilead Sciences narrative frames the stock as 21.7% above a $128.38 fair value, yet our DCF model points in a very different direction. On this view, GILD at $156.19 trades well below an estimated future cash flow value of $317.59, which raises a simple question. Which lens do you trust when the gap is this wide?
For investors comparing story versus spreadsheet, the SWS DCF model acts as a reality check on where long term cash generation might justify today’s $156.19 price, or a very different one tomorrow. Look into how the SWS DCF model arrives at its fair value.
Next Steps
Conflicting signals around Gilead Sciences often reflect a mix of enthusiasm and caution. Act quickly, test the assumptions against your own expectations, then weigh the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Gilead Sciences?
Do not stop with Gilead Sciences. Use this momentum to broaden your watchlist and pressure test your thesis against other opportunities that might suit your approach even better.
- Target resilient income by reviewing a hand picked group of dividend payers through 8 dividend fortresses.
- Hunt for value by screening companies that pair quality fundamentals with appealing entry points using 33 high quality undervalued stocks.
- Prioritize capital preservation and steadier rides by focusing on financially robust businesses with the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com