
James Halstead And 2 Other UK Penny Stocks To Consider
The London stock market has recently experienced some turbulence, with the FTSE 100 index closing lower due to weak trade data from China, highlighting ongoing global economic challenges. Amid such fluctuations, investors often seek opportunities in less conventional areas like penny stocks. Although the term may seem outdated, these smaller or newer companies can offer significant growth potential when backed by solid financials.
Below we spotlight a couple of our favorites from our exclusive screener.
James Halstead (AIM:JHD)
Simply Wall St Financial Health Rating: ★★★★★★
Overview: James Halstead plc is a manufacturer and supplier of flooring products for both commercial and domestic uses across the UK, Europe, Scandinavia, Australasia, Asia, and other international markets with a market cap of £558.82 million.
Operations: The company generates £259.91 million in revenue from the production and distribution of flooring products.
Market Cap: £558.82M
James Halstead plc, with a market cap of £558.82 million, faces challenges as its recent earnings report shows a decline in net income to £35.42 million from £40.61 million the previous year, and sales slightly decreased to £259.91 million. Despite this, the company maintains strong financial health with more cash than total debt and short-term assets significantly exceeding liabilities. However, negative earnings growth and declining profit margins present concerns for potential investors in penny stocks. The board is experienced but the management team is relatively new, which may impact strategic direction moving forward.
- Jump into the full analysis health report here for a deeper understanding of James Halstead.
- Examine James Halstead's earnings growth report to understand how analysts expect it to perform.

Card Factory (LSE:CARD)
Simply Wall St Financial Health Rating: ★★★★☆☆
Overview: Card Factory plc is a specialist retailer of cards, gifts, and celebration essentials with operations in the UK, South Africa, Republic of Ireland, the United States, and internationally; it has a market cap of £310.26 million.
Operations: The company's revenue is primarily generated from its Cardfactory Stores segment at £512.8 million, followed by Wholesale Partnerships at £49.4 million and Digital sales contributing £33.4 million.
Market Cap: £310.26M
Card Factory plc, with a market cap of £310.26 million, has shown robust revenue generation primarily from its Cardfactory Stores at £512.8 million. The recent half-year earnings report highlights an increase in sales to £260.8 million and net income rising to £9.2 million from the previous year, indicating financial improvement despite a decrease in profit margins to 5.8%. The company's debt is well covered by operating cash flow, and it has reduced its debt-to-equity ratio over five years. However, short-term assets do not cover liabilities, and negative earnings growth poses challenges for investors considering penny stocks.
- Unlock comprehensive insights into our analysis of Card Factory stock in this financial health report.
- Understand Card Factory's earnings outlook by examining our growth report.
PZ Cussons (LSE:PZC)
Simply Wall St Financial Health Rating: ★★★★☆☆
Overview: PZ Cussons plc is a company that manufactures, distributes, markets, and sells baby, beauty, and hygiene products across Europe, the Asia Pacific, the Americas, and Africa with a market cap of £415.43 million.
Operations: The company's revenue is derived from several regions, with £168 million from Africa, £46.4 million from Central, £176.4 million from Asia Pacific, and £202.2 million from Europe & The Americas.
Market Cap: £415.43M
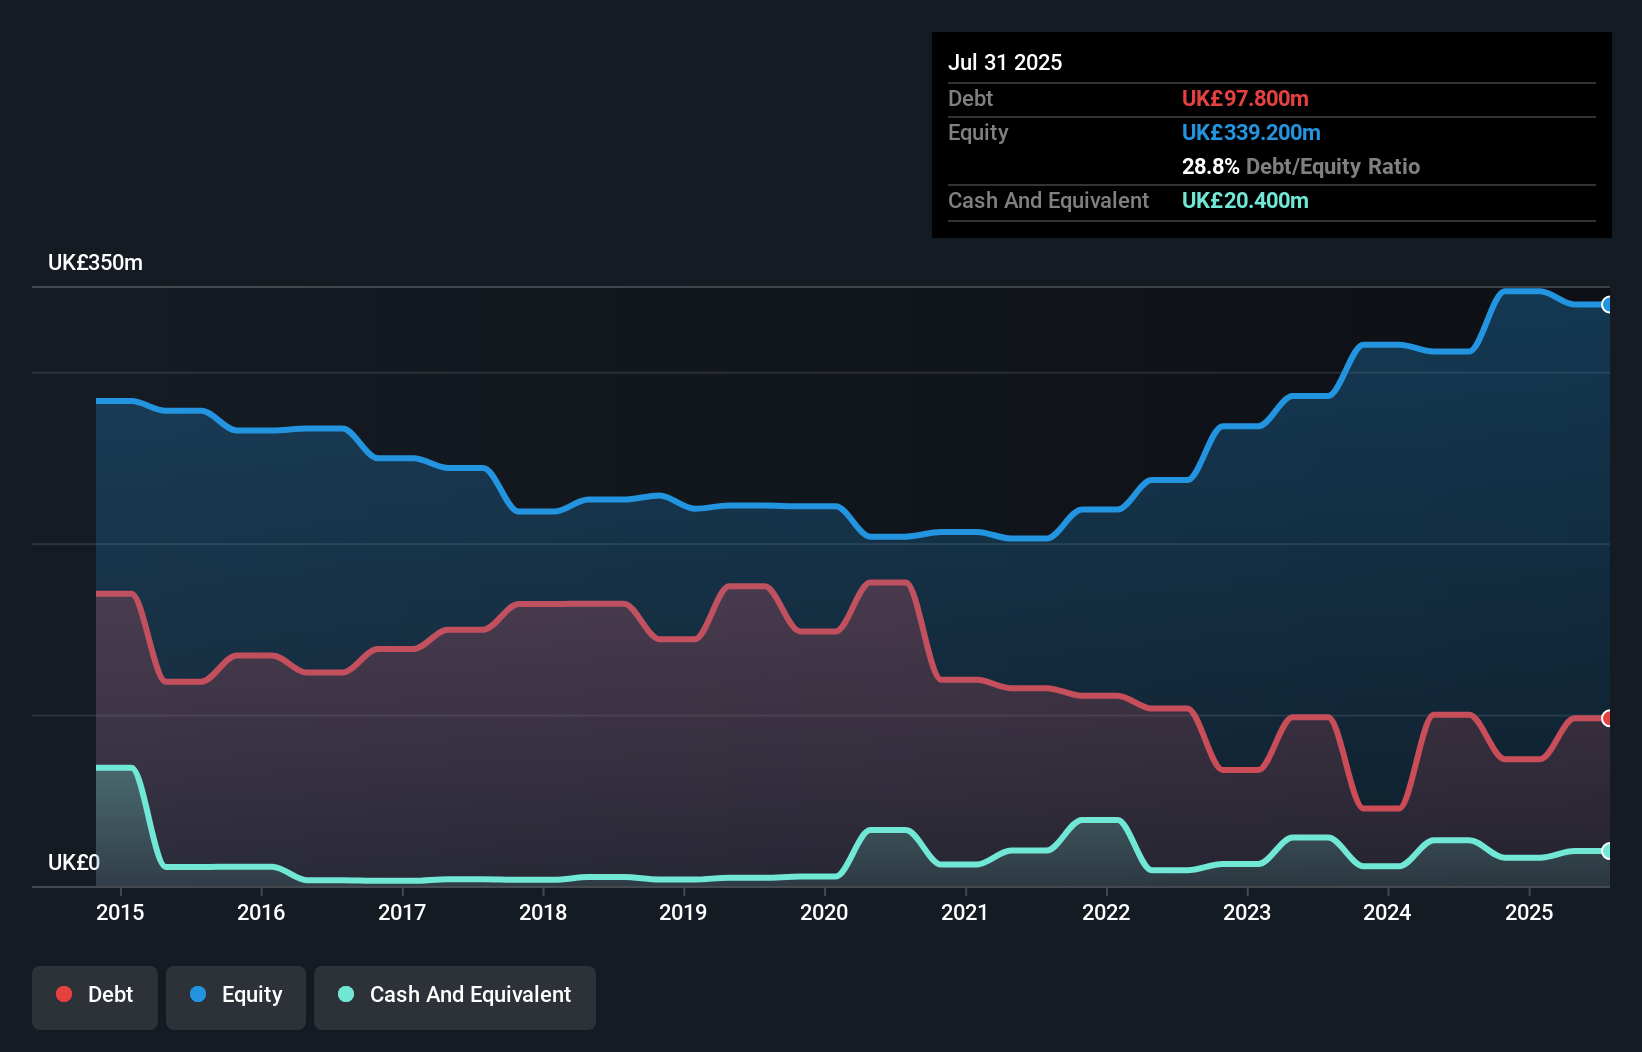
PZ Cussons plc, with a market cap of £415.43 million, has recently turned profitable, reporting sales of £541.4 million and net income of £19.8 million for the year ended May 31, 2026. Despite a satisfactory net debt to equity ratio of 10.3%, short-term assets (£231.3M) fall short of covering liabilities (£277M). The board's inexperience is notable with an average tenure of 2.4 years, while management shows more stability at 3.8 years. A proposed dividend increase and stable weekly volatility offer some positives; however, the company faces challenges such as low return on equity at 11.7% and reliance on one-off gains impacting financial results.
- Dive into the specifics of PZ Cussons here with our thorough balance sheet health report.
- Explore PZ Cussons' analyst forecasts in our growth report.

Turning Ideas Into Actions
- Take a closer look at our UK Penny Stocks list of 256 companies by clicking here.
- Ready To Venture Into Other Investment Styles? Rare earth metals are an input to most high-tech devices, military and defence systems and electric vehicles. The global race is on to secure supply of these critical minerals. Beat the pack to uncover the 32 best rare earth metal stocks of the very few that mine this essential strategic resource.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com