
Global Partners (GLP) Could Be 9% Overvalued On Credit Facility Extension
Global Partners (GLP) extended the maturity of its US$1.5b credit facility to 2031, a move that lengthens its debt timeline and reduces near term refinancing pressure for investors monitoring the stock’s balance sheet flexibility.
Recent price action already reflects some of this shift in perceived risk, with a 17.6% year-to-date share price return and a 17.4% one-year total shareholder return, while the three-year total shareholder return of 104.4% signals stronger momentum over a longer stretch for Global Partners.
Scan other balance sheet focused opportunities with 32 resilient stocks with low risk scores that share Global Partners’ emphasis on refinancing visibility and lender confidence.
The credit extension has helped Global Partners, yet the unit price of US$49.71 still screens at roughly a 55% discount to one intrinsic value estimate. Is that gap mispricing, or is it a fair reflection of risk?
Most Popular Narrative: 9% Overvalued
Analysts following Global Partners see fair value at $45.50, which sits below the latest close of $49.71 and frames the current valuation as slightly rich against their long term assumptions built on an 8.26% discount rate.
Acquisitions, divestments, and demographic trends are expected to support revenue stability, margin improvement, and stronger market positioning across core segments.
Refinancing efforts enhance financial flexibility, allowing for continued investment, expansion, and resilience amid changing energy and retail landscapes.
See why 4 investors see Global Partners as 9% overvalued.
Result: Fair Value of $45.50 (OVERVALUED)
Still, Global Partners carries clear pressure points, including dependence on fossil fuel volumes and the risk that long life fuel assets underperform as the energy transition progresses.
Find out about the key risks to this Global Partners narrative.
Another View: Market Pricing Versus SWS Fair Ratio
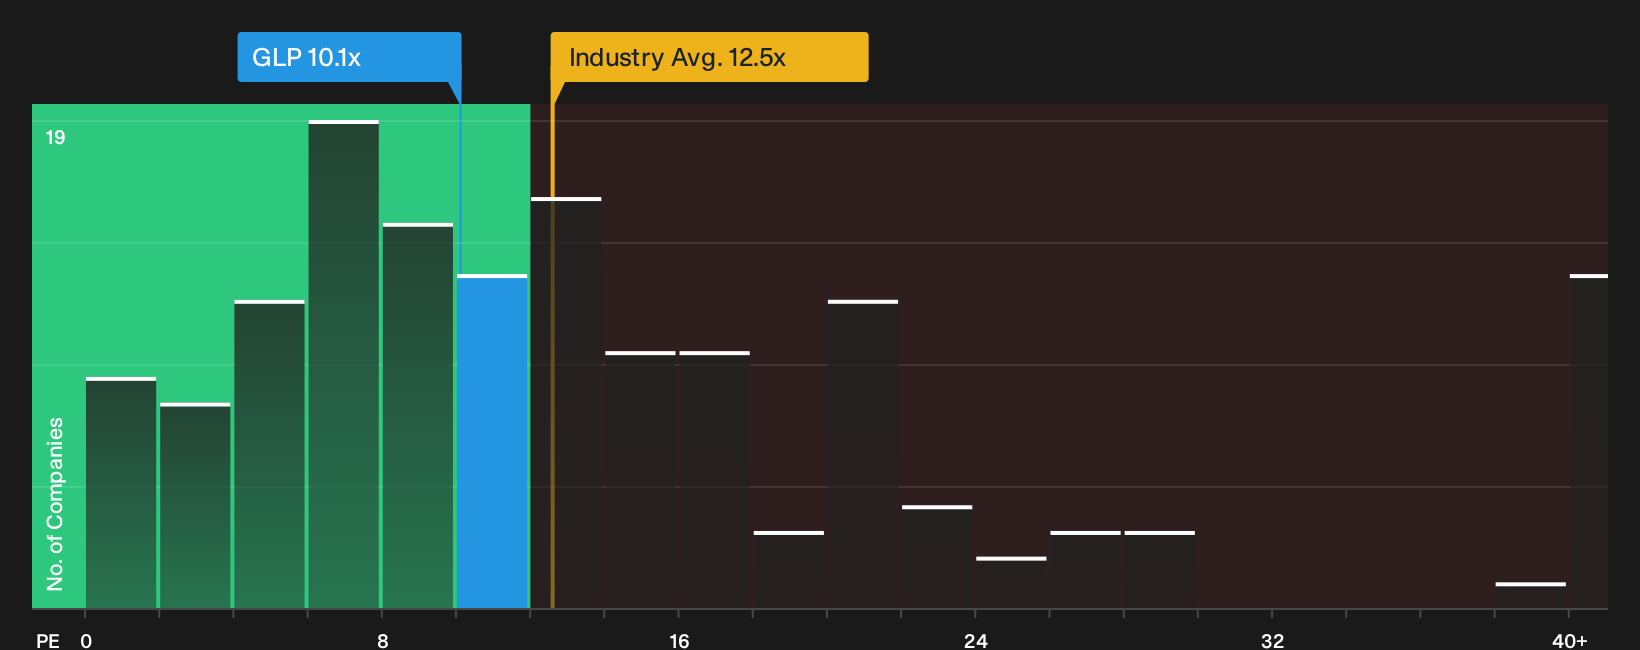
While the analyst narrative tags Global Partners as roughly 9% overvalued against a $45.50 fair value, the market is telling a different story when you look at the P/E. At about 10.1x earnings, the stock trades well below peers at 14.1x and under the Simply Wall St fair ratio of 11.8x.
That gap suggests investors are applying a clear discount despite earnings quality and recent profit growth, which cuts in the opposite direction to the analyst fair value call. Is this a cushion against the transition risks, or a sign that the consensus model is too cautious on Global Partners?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Global Partners so far. If you want to move from headline takes to your own judgment, start with the 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Global Partners?
You have seen how Global Partners stacks up. Now widen your watchlist with a few targeted hunting grounds that match different investing priorities.
- Target potential upside by running through a curated pool of quality candidates with pricing that still looks appealing using the 33 high quality undervalued stocks.
- Strengthen your income stream by focusing on companies that pair higher yields with balance sheet support through the 8 dividend fortresses.
- Dial down risk by filtering for businesses screened for financial resilience and clean fundamentals using the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com